Investment & Market Trends

Investment & Market Trends

Public Mutual Declares RM96mil+ In Distributions Across Five Funds

Public Mutual, a wholly-owned subsidiary of Public Bank Bhd, has declared total distributions amounting to more than RM96 million for five of its funds for the financial year ended June 30, 2026. In a statement, the unit trust manager said the distributions reflect the performance of its fixed income and income-focused funds over the period under review. Among the funds, the PB Islamic Bond Fund led with a gross distribution of 5.50 sen per unit. This was followed by the PB Infrastructure Bond Fund at 5.00 sen per unit, and the PB Fixed Income Fund at 4.50 sen per unit. Meanwhile, the Public Institutional Bond Fund declared a distribution of 0.90 sen per unit, while the Public Islamic Savings Fund recorded a payout of 0.10 sen per unit. Public Mutual noted that the PB Islamic Bond Fund, PB Infrastructure Bond Fund, PB Fixed Income Fund, and Public Institutional Bond Fund follow an annual distribution policy. In contrast, the Public Islamic Savings Fund distributes income on a semi-annual basis, providing investors with more frequent payout cycles. The group said the latest distributions underscore its continued focus on delivering consistent returns through a diversified range of fixed income and savings-oriented investment solutions, catering to both retail and institutional investors. Public Mutual currently manages more than 180 unit trust funds across various asset classes and investment strategies. It is also an approved Private Retirement Scheme (PRS) provider, managing nine PRS funds nationwide, further strengthening its position as one of Malaysia’s largest private unit trust managers.

Investment & Market Trends

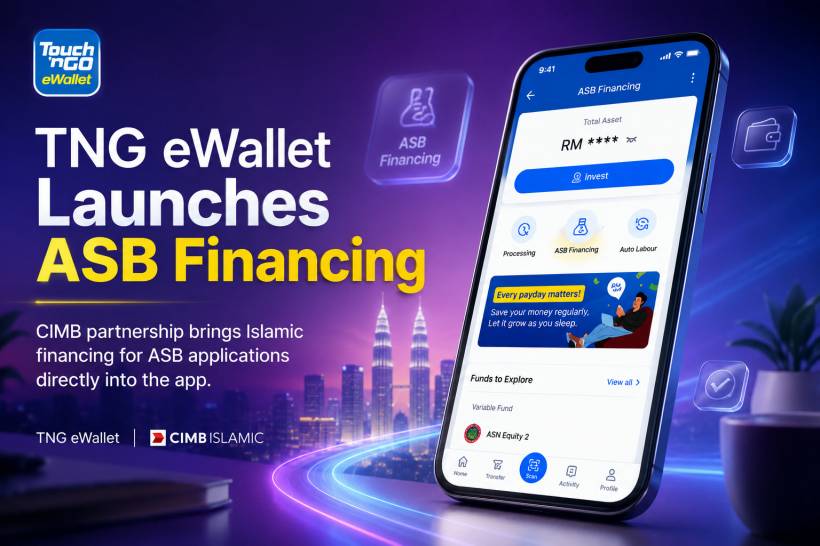
TNG Digital Introduces ASB Financing On TNG eWallet With CIMB

TNG Digital Sdn Bhd, the operator of the TNG eWallet, has launched its first Islamic financing product, ASB Financing, in collaboration with CIMB. In a statement, the company said the new offering allows users to invest in Amanah Saham Bumiputera (ASB) through a more seamless and integrated financing experience within the TNG eWallet ecosystem. Instead of requiring a large upfront payment, users can now participate in ASB investments through structured monthly repayment commitments. TNG Digital said the initiative is aimed at improving accessibility to wealth-building tools, particularly for users who may prefer a more flexible approach to long-term investing. According to the company, Bumiputera users currently account for 70% of TNG eWallet’s Amanah Saham Nasional Bhd (ASNB) investor base, contributing 52% of total investment value on the platform. This reflects strong demand for simplified and digitally enabled investment solutions within the segment. TNG Digital chief financial services officer Desmond Teoh said the launch marks an important milestone in expanding the range of financial services available under the platform’s GOfinance feature. “The strong adoption of ASNB investments on our platform clearly reflects growing interest in accessible and digitally connected wealth-building solutions among Malaysians,” he said. Since integrating ASNB services in 2023, TNG Digital said the TNG eWallet has continued to record steady growth in its digital investment offerings, with active investment users rising by 44% year-on-year as of May 2026. The ASB Financing product offers financing ranging from RM10,000 to RM200,000, with flexible repayment tenures of between five and 40 years. This allows users to select financing plans tailored to their financial goals and repayment capacity. TNG Digital said the collaboration with CIMB further strengthens its position in the digital financial services space, as it continues to expand its ecosystem beyond payments into investment and wealth management solutions.

Investment & Market Trends

ACE Market-Listed Pekat Plans Move To Main Market

Pekat Group Bhd, an ACE Market-listed solar company, is planning to transfer its listing to Bursa Malaysia’s Main Market. In a filing on Thursday, the company said it has met the key requirements for the move, including a strong profit track record, solid financial position, and positive net cash from operating activities. Pekat said the proposed transfer is expected to strengthen its credibility, reputation, and visibility among investors, particularly institutional investors, while reflecting the group’s growth and profitability since its ACE Market listing. Under Bursa Malaysia requirements, companies seeking a Main Market transfer must record at least RM30 million in aggregate net profit over the past three financial years, including a minimum of RM15 million in the most recent year. Pekat reported an aggregate net profit of RM80.78 million for FY2023 to FY2025, with FY2025 net profit alone at RM45.05 million. The company also confirmed it has met the requirement for a healthy financial position, with no accumulated losses and retained earnings of RM153.91 million as at end-December 2025. It added that it has maintained positive operating cash flow over the past three years and sufficient working capital for at least 12 months. As at end-December 2025, Pekat held cash and bank balances of RM87.62 million, alongside unutilised banking facilities of up to RM172.77 million. The proposed transfer is subject to approval from the Securities Commission Malaysia and Bursa Malaysia, and is expected to be completed by the fourth quarter of the year. Public Investment Bank Bhd is acting as the principal adviser for the exercise. Pekat was listed on the ACE Market in June 2021. Shares in the company closed six sen or 3.66% lower at RM1.58 on Thursday, valuing the group at RM1.12 billion.

Investment & Market Trends

Apple Raises MacBook And iPad Prices As Memory Costs Rise

Apple has raised prices of its iPad and MacBook lineup, saying it can no longer absorb rapidly rising memory and storage chip costs driven by the artificial intelligence-driven expansion of data centres. The price changes do not affect the iPhone, Apple’s main revenue generator. However, the increase pushes the starting price of the MacBook Neo, its entry-level laptop designed to compete with affordable Windows and Chromebook devices, from US$599 to US$699 (RM2,464 to RM2,875) just months after its launch. The move underscores how even Apple, the world’s most valuable consumer electronics company with a highly efficient supply chain, is not insulated from the sharp surge in memory prices that is reshaping the outlook for smartphones and personal computers. Memory manufacturers such as Micron have recently prioritised orders from AI chipmakers like Nvidia, which has boosted their profits but constrained supply for consumer electronics firms. This imbalance has forced device makers to pass on higher costs to customers. “We have never seen a component price increase this much, this quickly,” Apple said in a statement. “We have shielded our customers from these increases so far, but we have now reached a point where we need to begin raising prices on a number of products, including today’s increases for iPad and Mac.” Under the new pricing, the MacBook Air with 512GB storage now costs US$1,299, up from US$1,099, while the MacBook Pro with 1TB storage has risen to US$1,999 from US$1,699. The iPad Air with 128GB storage has also increased from US$599 to US$749, among other adjustments. Apple has also raised prices for its HomePod smart speaker and Apple TV set-top box. The announcement weighed on investor sentiment, with Apple shares falling nearly 5%, while Dell declined more than 8%. Analysts said rival device makers may be forced to implement even steeper price increases, as Apple’s strong supplier relationships have helped cushion part of the impact. “The memory environment is tough and remains structurally tough for the foreseeable future,” said Ben Bajarin, CEO of technology consultancy Creative Strategies. Apple said in April that existing inventory had helped maintain gross margins above Wall Street expectations, but warned that rising memory costs would begin to weigh on profitability by the end of the month. “We expect significantly higher memory costs,” CEO Tim Cook said during an April earnings call, adding that the pressure would continue beyond the June quarter. Apple has not disclosed additional measures beyond price increases to offset rising costs. “We know this is not welcome news, and we are working tirelessly to find solutions,” the company said. Analysts expect further price adjustments, including potential increases for the iPhone in the coming months. Some also believe the latest hikes may encourage consumers to bring forward purchases ahead of future increases. “The iPhone isn’t spared, its hike is coming,” said Nabila Popal, senior research director at IDC. She added that Apple’s timing of the price adjustments ahead of its fall iPhone launch was strategic, allowing the company to shift focus toward product value rather than pricing concerns during the launch cycle. Prices for dynamic random access memory (DRAM), used in most electronic devices, have surged sharply due to AI-driven demand. Industry tracker TrendForce reported increases of up to 98% in the first quarter of 2026, with further gains of 58% to 63% expected in the current quarter. The surge, described by some analysts as “RAMageddon,” has been driven by aggressive expansion of AI data centres, with firms such as Nvidia locking in long-term supply deals. Micron recently disclosed US$22 billion in such agreements. The rising cost environment is expected to weigh on global device demand. IDC estimates the smartphone market could see its steepest annual decline of nearly 14% this year, while the PC market may fall 11.3%. One bright spot had been Apple’s MacBook Neo, launched in March, which supported stronger-than-expected sales forecasts for the June quarter. However, the latest price increase has eroded its pricing advantage over competitors, including Dell’s XPS 13, as well as entry-level Chromebooks from Lenovo and Asus.

Investment & Market Trends

Samsung To Invest US$648 Billion In South Korea

Samsung Group is expected to announce plans to invest 1,000 trillion won (US$647.53 billion or RM2.7 trillion) in South Korea over the next decade, including a potential 300 trillion won commitment to build semiconductor manufacturing facilities in the country’s southwest region, according to a media report on Friday. The investment plan is set to be unveiled during a meeting with South Korean President Lee Jae Myung at the presidential office on Monday, the Maeil Business Newspaper reported, citing unnamed sources. Senior executives from major technology companies, including Samsung Electronics Co Ltd and rival SK Hynix Inc, are expected to attend the meeting, where they will present investment initiatives aimed at promoting economic growth beyond Seoul and its surrounding metropolitan areas. The reported investment push comes as South Korea seeks to encourage large corporations to expand operations outside the capital region. Samsung and SK Hynix currently have the bulk of their semiconductor production facilities concentrated around Seoul, and have faced increasing calls to support regional development through new investments. A significant portion of Samsung’s proposed spending is expected to be directed towards the semiconductor sector, reinforcing the country’s ambitions to strengthen its position in the global chip industry amid rising competition and growing demand for advanced technologies. South Korea’s presidential office said on Thursday that it plans to hold a public briefing on “three mega-projects for South Korea’s great leap forward”, adding that further details on the meeting would be announced in due course. Samsung had not issued an official comment on the report as of Friday, as the announcement was made outside regular business hours. If confirmed, the proposed 1,000 trillion won investment programme would rank among the largest corporate investment commitments in South Korea’s history and underscore Samsung’s long-term confidence in the country’s technology and manufacturing ecosystem.

Investment & Market Trends

GuocoLand Sells 20% Interest In Tower REIT Manager To Hong Leong Unit

GuocoLand (Malaysia) Bhd has disposed of a 20% stake in GLM REIT Management Sdn Bhd, the manager of Tower Real Estate Investment Trust, according to filings on Bursa Malaysia on Tuesday. Tower REIT said the stake was acquired by HL Management Co Sdn Bhd, a wholly owned subsidiary of Hong Leong Company (Malaysia) Bhd. Hong Leong Company is also the ultimate holding company of Hong Leong Bank Bhd. Following the transaction, GuocoLand retains an 80% equity interest in GLM REIT Management. The filing did not disclose the rationale for the partial divestment. Tower REIT added that the Securities Commission Malaysia has approved the change in shareholding, clearing the regulatory requirement for the transaction to proceed. GuocoLand is a subsidiary of Guoco Group Ltd, the overseas investment arm of the Hong Leong Group, which is ultimately controlled by the Kwek family. GLM REIT Management Sdn Bhd serves as the manager of Tower REIT, overseeing its operations and strategic direction. The divestment represents a change in the ownership structure of the REIT’s management company but does not affect the listed REIT itself. Market reaction was muted, with Tower REIT closing unchanged at 30 sen on Tuesday, valuing the company at RM147.3 million. GuocoLand also ended the session flat at RM1.09, giving it a market capitalisation of RM763.5 million.

Investment & Market Trends

Japanese Parent To Take Ajinomoto Malaysia Private At RM20 A Share

Japan’s Ajinomoto Co Inc will take its Malaysia-listed unit private at RM20 per share, representing a 31.6% premium over its last traded price of RM15.20. In a Bursa Malaysia filing, Ajinomoto (Malaysia) Bhd (KL:AJI) said the privatisation exercise, valued at RM603.4 million, will be carried out via a selective capital repayment. As at March 31, Ajinomoto Malaysia held cash of RM74 million, equivalent to about RM1.23 per share. Based on a preliminary estimate, the Japanese parent is expected to inject more than RM500 million to fund the transaction. The company said the exercise will be funded through its excess funds, with the remaining portion to be financed by the parent company. However, no detailed breakdown was disclosed. The board of Ajinomoto Malaysia, excluding conflicted directors, will deliberate on the proposal and determine the next course of action. If completed, Ajinomoto Co does not intend to maintain the listing of Ajinomoto Malaysia, which is primarily involved in food seasonings, including monosodium glutamate (MSG). Ajinomoto Co currently holds a 50.38% stake, or 30.63 million shares, in the Malaysian unit. The privatisation will involve acquiring the remaining 30.17 million shares, or 49.62% interest, via a selective capital reduction and repayment exercise. Under the proposal, the group will pay RM603.4 million in total at RM20 per share to cancel the minority shareholding. As at June 22, Ajinomoto Malaysia had an issued share capital of RM65.1 million comprising 60.8 million shares. As at end-March, the group had RM74.24 million in cash and bank balances and about RM273.5 million in liquid investments. Retained earnings stood at around RM805 million, against total equity of RM867.6 million. It has no material borrowings aside from lease liabilities of about RM5.16 million. To facilitate the transaction, Ajinomoto Malaysia will first issue 571.1 million bonus shares, as the proposed repayment exceeds its existing share capital. However, these shares will not be credited to shareholders or listed. The subsequent capital reduction will see all minority-held shares, along with the bonus shares, cancelled. Ajinomoto Co said the offer provides shareholders an attractive exit opportunity given the company’s historically low trading liquidity, with average daily volume accounting for just about 0.13% of its free float. It added that Ajinomoto Malaysia has derived limited benefit from its listing status, as it has not raised funds from the capital market for over a decade while still incurring listing-related costs. The proposal requires approval from at least 75% of votes cast by independent shareholders, with dissenting votes not exceeding 10%, along with other regulatory approvals. Trading in the stock will resume at 9am on Tuesday.

Investment & Market Trends

Malaysia Airlines, Singapore Airlines To Introduce Joint Fares For KL–Singapore Route

Malaysia Airlines and Singapore Airlines will introduce new joint fare products for travel between Kuala Lumpur and Singapore as part of an expanded partnership. The new offerings build on their existing codeshare arrangement and aim to provide travellers with more fare options between the two capital cities, while enhancing connectivity across both carriers’ wider networks, according to a joint statement. Both airlines are also working towards introducing additional customer benefits in phases, including reciprocal lounge access, coordinated flight schedules and joint corporate travel arrangements. No further details on the fare products were disclosed. “This joint business partnership with Singapore Airlines marks a significant milestone in the expansion of our commercial collaboration,” said Bryan Foong Chee Yeong, head of airline business at Malaysian Aviation Group Bhd, the parent company of Malaysia Airlines. Singapore Airlines chief commercial officer Lee Lik Hsin said the new fare products would broaden travel options for passengers flying between Singapore and Kuala Lumpur. Malaysia Airlines and Singapore Airlines have been strengthening cooperation since signing a commercial framework agreement in October 2019. Both national carriers currently maintain codeshare agreements across routes in Malaysia, Singapore, Europe and South Africa. In February 2024, they also introduced reciprocal mileage accrual and redemption between Malaysia Airlines’ Enrich programme and Singapore Airlines’ KrisFlyer programme, allowing members to earn and redeem points on selected flights operated by either airline.

Investment & Market Trends

Berjaya Corp Sells Entire Citaglobal Stake To Detik Ria For RM42.6m

Berjaya Corporation Bhd has disposed of its entire 8.64% stake in Citaglobal Bhd to Detik Ria Sdn Bhd for RM42.56 million. In a Bursa Malaysia filing on Monday, Berjaya Corp said its wholly owned subsidiary, Berjaya Securities Sdn Bhd, sold 46.77 million Citaglobal shares to Detik Ria via a direct business transaction on June 19 at 91 sen per share. Detik Ria is controlled by Johor princess Tunku Tun Aminah Sultan Ibrahim, who is also Berjaya Corp’s non-executive chairman, a director of Berjaya Securities and chairman of Detik Ria. As a result, the disposal is considered a related-party transaction. The shares were originally acquired at 90 sen each through Citaglobal’s private placement exercise completed on June 8, with the carrying value in Berjaya Corp’s books also standing at 90 sen per share. Following the sale, Berjaya Securities has ceased to be a shareholder of Citaglobal. Berjaya Corp said the disposal price was determined based on Citaglobal’s prevailing market price at the time of the transaction. Proceeds from the sale will be used for working capital purposes, including administrative, marketing and operating expenses. The group added that the disposal is not expected to have a material impact on its net assets, earnings or gearing for the financial year ending June 30, 2026, nor will it affect its issued share capital or substantial shareholders’ holdings. Tunku Aminah abstained from all board discussions and voting related to the transaction. Berjaya Corp’s audit committee deemed the disposal fair, reasonable and conducted on normal commercial terms, adding that it is not detrimental to minority shareholders. Berjaya Corp shares closed 0.5 sen higher at 25.5 sen on Monday, giving the group a market capitalisation of RM1.55 billion. The stock has declined 3.8% over the past year. Citaglobal ended unchanged at 90.5 sen, valuing the company at RM489.9 million, with its shares up 12.4% over the same period.

Investment & Market Trends

Sunview To Divest Winstar Stake For RM30 Million At 43 Sen Per Share

Sunview Group Bhd has proposed to sell its entire 22.44% interest in Winstar Capital Bhd for RM30.1 million in cash to nine investors. In a Bursa Malaysia filing on Monday, Sunview said the disposal involves 70.03 million Winstar shares at 43 sen apiece under nine separate share sale agreements. The offer price is 23.9% below Winstar’s closing price of 56.5 sen on Monday. Among the buyers are four key management personnel and substantial shareholders of Winstar, namely vice-chairman Chua Nyok Chong, chief executive officer Chua Boon Hong, chief operating officer Lee Yong Zhi and chief marketing officer Khoo Nee Cheng. The other purchasers comprise Datuk Low Chin Koon, non-executive chairman of Tex Cycle Technology (M) Bhd and independent non-executive director of Mestron Holdings Bhd; Por Teong Eng, managing director of Mestron; Chu Kerd Yee, executive director of ES Sunlogy Bhd; as well as Ng Cheng Keng, Phuah Hue Shun and K Seng Seng Corporation Bhd. Sunview noted that the disposal price represents a 65.4% premium to its original investment cost of 26 sen per share and a 16.2% premium to the stake’s net book value of 37 sen per share as at Sept 30, 2025. The company expects to recognise a disposal gain of approximately RM6.8 million upon completion. Proceeds from the transaction will mainly be channelled towards working capital and debt reduction. About RM18.1 million will be allocated for engineering, procurement, construction and commissioning (EPCC) projects, while RM11.8 million will be used to repay bank borrowings. Sunview invested RM18 million in Winstar Aluminium Manufacturing Sdn Bhd in 2023 and said the proposed sale allows it to unlock the value of its investment, improve cash flow, lower gearing and retain borrowing capacity for future undertakings. The group added that disposing of the shares through the open market could have exerted significant downward pressure on Winstar’s share price due to the stock’s relatively low trading liquidity. The 70.03 million shares involved are equivalent to 21.3 times Winstar’s average monthly trading volume over the past six months and 6.4 times its average monthly trading volume over the past year. The proposed disposal is subject to shareholders’ approval and is targeted for completion by the first quarter of 2027. Based on Sunview’s audited financial statements as at Sept 30, 2025, the transaction is expected to raise its net asset per share to 19 sen from 17 sen and reduce its gearing ratio to 1.58 times from 1.82 times on a pro forma basis. Sunview shares closed 0.5 sen lower at 37 sen on Monday, valuing the company at RM223.3 million. The stock has declined 5.1% over the past year. Winstar shares finished unchanged at 56.5 sen, giving it a market capitalisation of RM176.4 million, with the stock up 4.6% over the same period.

Scroll to Top

Subscribe
FREE Newsletter