Author name: theexchangeasia admin

ESG

What Consumers Want Is Constantly Changing

Consumers are notoriously difficult to stand still for. What tastes good today may feel ordinary tomorrow. Price still matters, but so do ingredients, convenience, dietary preferences and increasingly, confidence in how a product was made. Food manufacturers are not simply competing against other brands; they are trying to keep pace with customers whose expectations continue to evolve. Director of CWP Food Manufacturing – Yanice Cheong Ming Yan. For CWP Food Manufacturing Sdn Bhd, that change is shaping what comes off the production line — and what happens behind it. Established in 2008 and based in Ipoh, Perak, CWP manufactures traditional and plant-based products for domestic and export markets. Its strategy increasingly combines differentiated products with something less visible to consumers: stronger manufacturing standards. The company believes the next stage of competition will not be won on taste or price alone.   Giving the Market Something Different CWP sees an opportunity in consumers looking for alternatives to conventional products. Its Double Triple Sweet Potato product, for example, uses sweet potato and is positioned around characteristics including naturally occurring anthocyanins, higher fibre, lower oil content and no artificial colouring. Its SeaVit seaweed product approaches the market differently. The plant-based offering is positioned around higher protein and fibre content, zero cholesterol and Halal recognition. Both reflect CWP’s attempt to create products with a clearer reason to exist in an already crowded market. That distinction matters. Consumers walking through a supermarket have no shortage of choices. A new product therefore has to compete not only for taste, but for attention, perceived value and relevance to changing preferences. For CWP, product development is consequently becoming more closely connected to identifying gaps in what consumers want rather than simply producing another variation of what already sells. But getting someone to try a product is only half the challenge.   Taste Gets You In. Consistency Keeps You There. Behind CWP’s product strategy is a less glamorous problem: making sure the same product can be produced reliably at scale. Buyers expect repeatable taste and texture. Distributors need stable supply. Larger customers increasingly require documentation and traceability alongside the product itself. That makes manufacturing discipline part of the commercial proposition. CWP operates with Halal compliance as a baseline and is strengthening its Food Safety Management System through ISO 22000 implementation. Its focus includes supplier controls, standard operating procedures, quality checkpoints, documentation, traceability and staff competency. As production volumes increase, those systems become more important. Scaling creates greater opportunities for variation and human error. CWP has therefore strengthened coordination between production, quality assurance and warehousing while clarifying responsibility for inspections and approvals. The objective is simple: growth should not make the product less predictable.   The Higher Price of Bigger Markets CWP’s ambitions also explain its emphasis on compliance. The company wants to expand into new markets and ultimately reach customers with more demanding procurement requirements. ISO 22000 is part of that preparation, with CWP looking longer term towards internationally recognised schemes such as FSSC 22000 to support access to higher-requirement channels and international chain retailers. That changes how growth has to be measured. Revenue remains important, but CWP also considers repeat orders, customer retention, delivery performance, consistency and reductions in non-conformities. It is deliberately avoiding expansion that would require compromises in food safety, Halal integrity or documentation. For smaller manufacturers, that discipline can determine how far they are ultimately able to travel. Selling into more sophisticated markets does not simply require a product consumers like. Buyers need confidence that the manufacturer behind it can repeatedly meet their requirements.   Less Waste, More Discipline The same operational thinking extends to sustainability. CWP has tightened production planning to reduce material losses and improved handling processes to minimise damaged products. Waste streams are separated for appropriate disposal, while used cooking oil is handled through registered recycling vendors. None of these initiatives is particularly dramatic on its own. But reducing waste also reduces cost, while better handling can improve hygiene, efficiency and product quality. Responsible manufacturing and commercial efficiency do not necessarily have to pull in opposite directions. For CWP, both depend on better processes. That may ultimately be the more important transformation taking place inside the company. CWP started as a manufacturer responding to demand for food products. Its next phase requires it to become increasingly sophisticated in understanding not only what consumers want, but what retailers, distributors and international buyers expect from the companies supplying them. Those expectations will continue moving. Today’s differentiator can become tomorrow’s minimum requirement. Plant-based products become more common. Food safety standards rise. Traceability becomes expected. Consumers discover new ingredients and move on to the next preference. Manufacturers cannot predict every change. They can, however, build businesses capable of responding to them. For CWP, that means combining product development with stronger systems, better-trained people and manufacturing standards capable of supporting larger ambitions. Because what consumers want is constantly changing. The real competitive advantage may be building a company capable of changing with them.
Investment & Market Trends

Li Ka-shing Sticks To US$23 Billion Ports Asking Price Despite Panama Loss

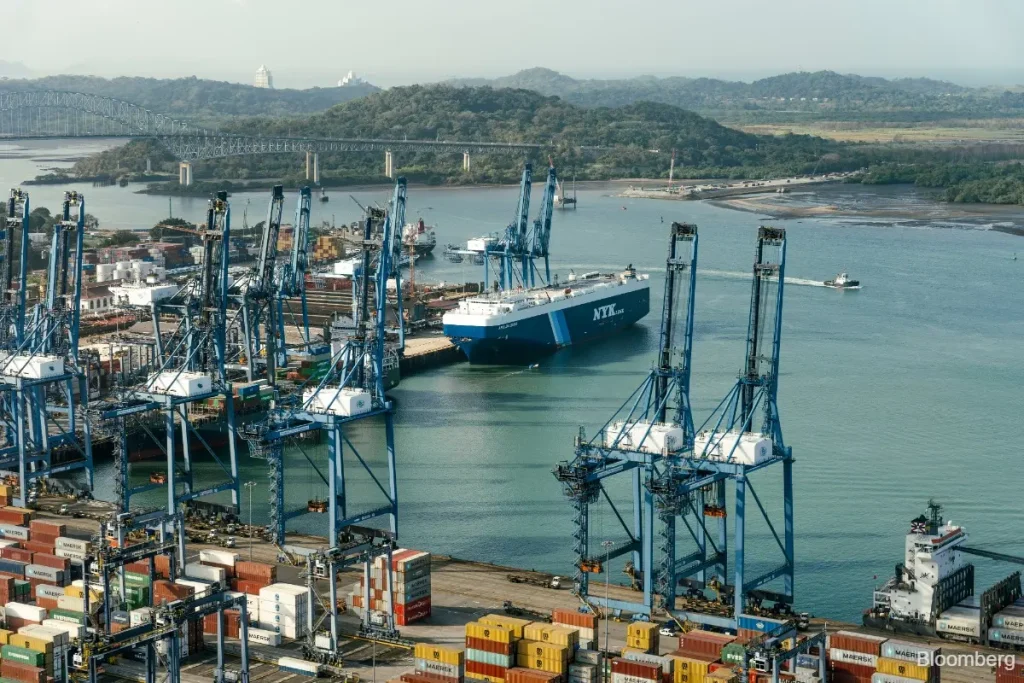
Li Ka-shing’s CK Hutchison Holdings Ltd expects to sell what remains of its global ports portfolio for its original US$22.8 billion (RM91.82 billion) valuation, even after losing two Panama terminals that had originally been included, according to people familiar with the matter. The proposed sale of 43 global ports, to a buyer consortium that includes US investment firm BlackRock Inc, was expected to net CK Hutchison more than US$19 billion in cash when it was first announced in March 2025. That expectation has not changed, even with the Panama Canal facilities excluded from the package, the people said, speaking on condition of anonymity as the deliberations are private. The talks are ongoing, and final details, including pricing, could still shift given the complexity of the deal, they added. Panama invalidated CK Hutchison’s contract to operate the ports earlier this year following pressure from US President Donald Trump. The Hong Kong conglomerate and its unit, Panama Ports Co, have since launched separate international arbitration claims challenging the decision, seeking damages of at least US$3.5 billion. Any compensation arising from those cases is expected to be shared between CK Hutchison and the buyers, one of the people said. The Panama facilities had accounted for only about 4% of the portfolio’s original price. According to one of the people, the price of the remaining 41 ports is believed to have risen enough to offset their loss, as buyers increasingly view them as logistical assets generating stable income amid rising geopolitical tension. Company representatives, bankers and lawyers continue to meet weekly to negotiate deal terms, the people familiar with the matter said. The sale has become a flashpoint in the broader US-China rivalry, with tensions running especially high over the Panama terminals, as Washington vows to protect its interests in Latin America while Beijing expands its influence in the region. Hopes for a political breakthrough have been renewed following news that Chinese leader Xi Jinping plans to meet Trump during his September trip to the US, though the parties remain cautious given that a similar high-level meeting in May between the two failed to yield results, according to the people. A spokesperson for BlackRock declined to comment. CK Hutchison and members of the buyer consortium — including China Cosco Shipping Corp, China Merchants Bank Co and Italian billionaire Gianluigi Aponte’s MSC Mediterranean Shipping Co — did not respond to requests for comment. Mired Down The deal hit roadblocks soon after it was announced, with CK Hutchison drawing Beijing’s ire over its agreement to sell ports in strategically significant global locations to a consortium backed by BlackRock. To secure China’s approval, the group invited state-owned companies, including Cosco, to join the buyer consortium. Discussions have remained bogged down as the parties navigate regulatory hurdles across the various countries where the ports are located, while also attempting to reconcile competing demands from prospective buyers. Talks have centred on a proposal to split the ports into different ownership structures, according to reports. That arrangement could give Chinese buyers larger stakes and greater control in certain locations, while other consortium members take the lead elsewhere. Panama’s forced takeover of the two terminals added further uncertainty to the deal, with Beijing warning that the country could pay a “heavy price” for the move. Parties involved in the sale are likely to seek positive signals from both China and the US before finalising the transaction’s terms, according to reports. There are signs, however, that tensions between Beijing and Panama may be easing. The two sides are reportedly moving toward renewing an agreement that gives Panama-flagged vessels favourable treatment at Chinese ports, according to local media reports in August, citing China’s ambassador to the country.

Investment & Market Trends

SBC Weighs Consolidating Singapore Operations Under Single Entity

HSBC Holdings plc is considering merging its wholesale, retail and private banking businesses in Singapore into one unified entity as part of a broader effort to simplify its structure, according to sources close to the matter who spoke on condition of anonymity. This potential restructuring is part of a larger transformation effort led by CEO Georges Elhedery, who has been streamlining the bank’s operations, closing or divesting several units, and cutting costs since taking the helm in September 2024. Earlier this year, HSBC sold its Singapore insurance arm for US$2.1 billion (RM8.46 billion). Responding to the reports, an HSBC spokesperson said the bank regularly evaluates its organizational setup for ways to simplify, while stressing that all Asia-Pacific entities remain under the oversight of The Hongkong and Shanghai Banking Corporation, with no changes planned to that arrangement. Currently, HSBC’s Singapore retail and wealth management business operates as a separately incorporated entity, HSBC Bank (Singapore) Ltd, established in 2016, alongside a separate branch under its main Asia arm, The Hongkong and Shanghai Banking Corp. Despite the potential restructuring, HSBC continues to expand its presence in Singapore, including plans for a new global AI hub and the hiring of over 100 AI specialists. The possible shake-up comes as HSBC faces scrutiny over its heavy reliance on Hong Kong, where it holds the largest exposure among global banks amid rising geopolitical tension. The bank recently expanded further in the territory through its US$14 billion buyout of Hang Seng Bank Ltd, reinforcing Hong Kong’s role as its top profit source and one of the city’s three banknote-issuing institutions. By comparison, HSBC’s Singapore business remains far smaller. In the first half of 2026, Singapore contributed US$774 million in pretax profit, against Hong Kong’s US$7.8 billion. Hong Kong also employs over 30,000 HSBC staff with US$144 billion in wholesale loans, compared to roughly 3,600 employees and US$21.8 billion in wholesale lending in Singapore. Such restructuring wouldn’t be unprecedented — in 2019, Standard Chartered plc took a similar step, consolidating into a locally incorporated subsidiary and establishing twin hubs in Singapore and Hong Kong to cut costs and simplify operations.

ESG

A Simple Purchase Can Give A Child Fighting Cancer A Second Chance

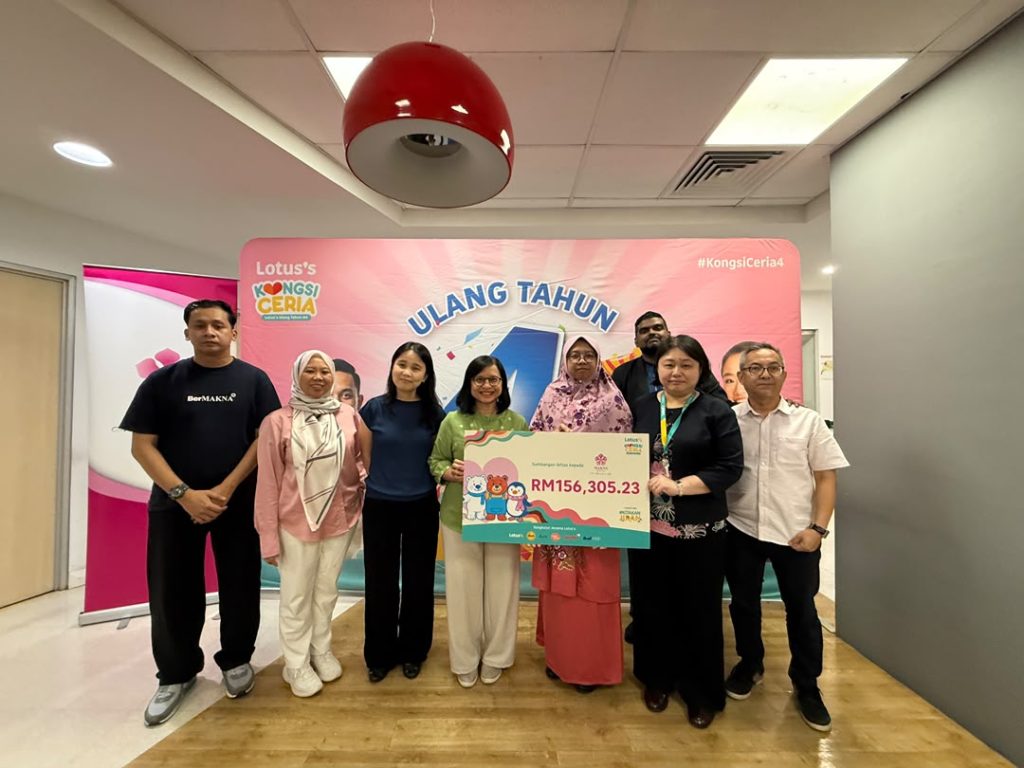
Thousands of everyday purchases have helped support children undergoing cancer treatment, with RM156,305.23 raised for Majlis Kanser Nasional (MAKNA) through Lotus’s Malaysia’s fourth anniversary campaign. For a child, school, friends and everyday routines are simply part of growing up. But cancer can suddenly put those simple joys on hold, bringing fear and uncertainty into a young life. The diagnosis can also bring emotional distress to patients and their families, while the demands of treatment can add financial pressure to households already struggling to make ends meet. From left to right: Rais Asraf, MAKNA Executive; Hanita Hanim, MAKNA Assistant Project Manager; Erica Tam Lotus’s Commercial Director (Grocery); Azliza Baizura Azmel Lotus’s Executive Director Corporate Services; May Li Lotus’s Commercial Director; Azlina Mohd Rashid, MAKNA Head of Department; Ravi Varman, MAKNA Assistant Head of Division; Tarmizi Abdul Rahman, MAKNA Assistant Project Manager. Through its Bursary Assistance, MAKNA helps patients and families meet some of the practical costs of cancer care, including transportation to hospitals, medical appliances and other treatment related needs. The assistance can help patients continue treatment when these costs become barriers to care. The funds will also support MAKNA’s Scholarship Programme for children from cancer affected families, helping those whose education may be disrupted by illness and financial difficulties to continue their studies and work towards better opportunities. Through its annual Kongsi Ceria anniversary initiative, Lotus’s contributes 0.5 per cent of sales from its Own Brand products during the anniversary month towards children’s healthcare needs. The campaign ran from 7 May to 6 June 2026. “MAKNA is committed to supporting cancer patients at every stage of life, from children to the elderly. Cancer does not discriminate by age, and neither should access to care. We are not just helping patients through today’s challenges; we are giving them the strength and opportunity to look towards a better tomorrow,” said Puan Farahida Mohd Farid, General Manager of MAKNA. Childhood cancer can disrupt schooling and everyday life, with time spent in hospital often meaning missed classes, time with friends and other childhood activities. Parents also have to balance treatment costs with household expenses. For underprivileged families, these pressures can make it harder to maintain continuity of care and education. MAKNA’s bursary and scholarship assistance addresses some of these practical and financial challenges. Fifi Nurdianna (L), MAKNA Executive and Noor Suhaila, MAKNA Executive with a pediatric cancer patient. The contribution came from customers who bought Lotus’s Own Brand products during the anniversary month. While individual purchases may have seemed small, collectively they generated funds that can be channelled towards children and families receiving support from MAKNA. The initiative demonstrates the value of long term collaborations between charitable organisations and corporate partners. By combining Lotus’s broad customer reach with MAKNA’s experience supporting cancer patients and their families, the partnership helps ensure assistance reaches those who need it most. Lotus’s Malaysia said its anniversary is an opportunity to give back to the communities it serves. “Through our customers’ everyday purchases, we hope to ease the burden on families and give children fighting cancer a better chance at recovery,” said Azliza Baizura Azmel, Executive Director Corporate Services of Lotus’s Malaysia. Lotus’s has also extended its anniversary giving beyond cancer care. As part of its wider 2026 initiative, brand partner P&G raised funds through product sales at Lotus’s stores to support children with special needs under the care of Tender Touch Rehabilitation Center and Gabungan Anak Anak Palsy Sereberum (GAPS) Malaysia. For children and families navigating cancer, such support can help maintain access to treatment and education while easing some of the financial pressures that come with care.

Energy & Technology

MUFG Highlights Japan-Malaysia Partnership As Key To Asia’s Energy Transition

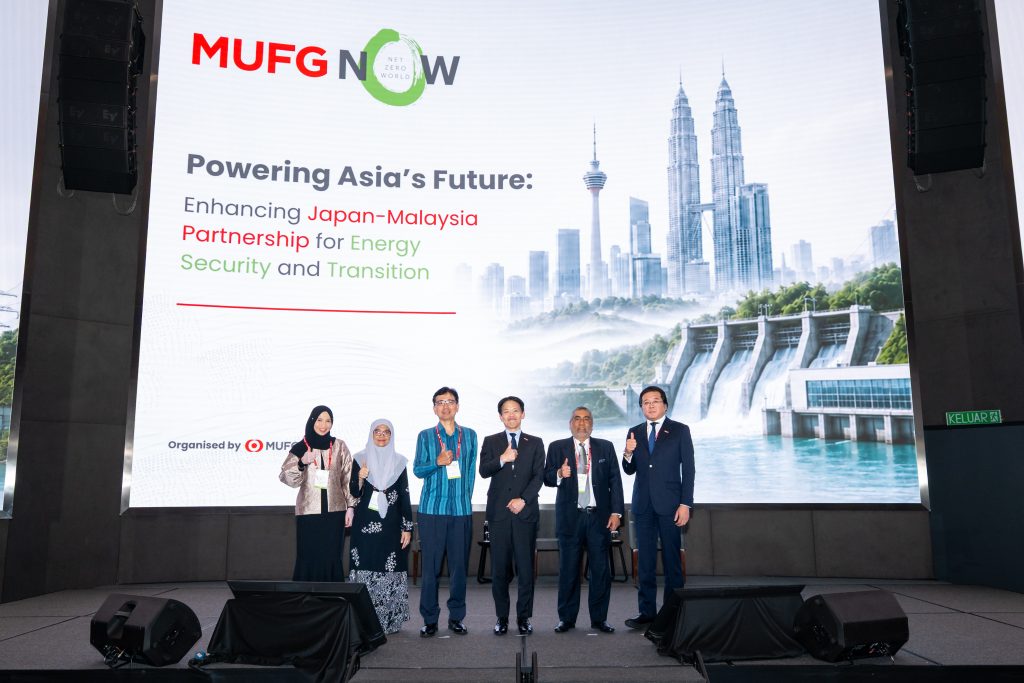
Close to 200 business leaders, policymakers and industry  experts convened at MUFG Net Zero World (MUFG N0W) Malaysia 2026 at Kuala Lumpur on Tuesday (Sept 15) to explore how closer Japan-Malaysia collaboration can strengthen regional energy security, accelerate the deployment of transition technologies and  mobilise financing for commercially viable projects.  MUFG N0W is MUFG’s flagship regional networking and thought leadership platform  bringing together public and private-sector leaders to advance practical responses to the  challenges and opportunities shaping Asia’s sustainable development.   [L-R] Puan Harmizan Mansor, General Manager of Group Corporate Finance, Petronas;  Puan Zuaida Abdullah, Deputy CEO, Investment Development, MIDA; His Excellency Noriyuki  Shikata, Ambassador of Japan to Malaysia; Yukinobu Saeki, MUFG’s Chief Executive for APAC;  YBhg. Dato’ Noorazman bin Abd Aziz, Chairman of MUFG Bank (Malaysia) Berhad; Motohide  Okuda, CEO and Country Head for MUFG Malaysia. Held under the theme “Powering Asia’s Future: Enhancing Japan-Malaysia Partnership  for Energy Security and Transition”, the event examined three connected priorities:  strengthening the Japan-Malaysia energy and industrial corridor; building Malaysia’s future  energy ecosystem; and making energy security bankable through transition finance.  The event programme covered emerging opportunities in areas including carbon capture  and storage, hydrogen, renewable energy, sustainable aviation fuel, power infrastructure  and transition finance, with a focus on moving from dialogue to investable projects.  His Excellency Noriyuki Shikata, Ambassador of Japan to Malaysia, highlighted the strength  of the Japan-Malaysia partnership in his keynote speech: “Japan’s advanced technology  and capital are actively flowing into Malaysia through proactive investments in AI,  semiconductors, supply chain resilience, and green transformation, as well as in almost all  of the 17 strategic sectors identified by the country as crucial for its growth. This is clear  evidence of the qualitative and quantitative expansion of our economic ties and presents a  bright outlook for the future.”   Puan Zuaida Abdullah, Deputy CEO, Investment Development, Malaysian Investment  Development Authority (MIDA), said in her policy address: “The global energy transition is  reshaping economic competitiveness and investment priorities. Building on decades of  partnership, Malaysia and Japan can leverage technology and green industries to   strengthen our industrial capabilities, directly supporting the New Industrial Master Plan  2030, National Energy Transition Roadmap, and Green Investment Strategy.   “MIDA is committed to turning these opportunities into high-quality investments that drive  lasting value for Malaysia,” she added.   Motohide Okuda, MUFG Malaysia’s Chief Executive Officer and Country Head said: “The  opportunities ahead are significant, but real progress will depend on our ability to move from  discussion to implementation. At MUFG, we are committed to connecting stakeholders,  mobilising capital and supporting strategic partnerships that can transform promising ideas into investable projects. By working together, we can strengthen energy security, advance  the transition journey and support sustainable economic growth across the region.”  Attendees at MUFG N0W Malaysia included speakers from leading energy players as well  as experts from the Institute of Energy Economics Japan, Asian Development Bank and  Japan Bank for International Cooperation.  MUFG’s presence in Malaysia dates to 1957, and the bank will mark its 70th year of service  in the market in 2027. Over this period, MUFG has supported Japanese companies investing  and expanding in Malaysia, while connecting Malaysian clients with opportunities across  Japan, ASEAN and its wider global network. Its capabilities span conventional and Islamic  banking, including establishing an Islamic banking arm in 2008 – the first Japanese bank to  do so in Malaysia – and contributing to the world’s first Yen-denominated Sukuk.  In addition to engaging corporate clients through MUFG N0W, the bank has also actively  collaborated with them on transactions ranging from green financing and sustainability linked loans to green trade. MUFG Malaysia was awarded Best Sustainable Bank (International) by FinanceAsia in 2024 and “Best Sustainable Finance Deal (Malaysia)” in  2025 for its collaboration with AEON Credit Service (M) Berhad, recognising Malaysia’s  largest social loan by a non-bank financial institution to date. 

Energy & Technology

CIMB Completes Malaysia’s First Tokenised Sukuk Settlement Using Tokenised Deposits

CIMB Group Holdings Bhd has completed a pilot to test the settlement of tokenised sukuk using tokenised deposits in a controlled environment, paving the way for broader applications enabled by blockchain technology. These potential applications include instant, or atomic, settlement for cross-border transactions, as well as the democratisation of investment assets — such as enabling bonds to be sold in smaller amounts that retail investors can more easily afford. The pilot was carried out through CIMB Islamic Bank Bhd in connection with a RM1.68 billion issuance under CIMB Islamic’s existing RM10 billion senior sukuk wakalah programme, with tenors of five, seven, 10 and 15 years. Of the total issuance, RM1.38 billion was issued in tokenised form and subscribed to by 12 institutional investors, while the remaining RM300 million was issued as a traditional sukuk. The order book was covered 1.73 times, with the pricing date set at Aug 19 and settlement completed on Aug 27, according to Sylvia Wong, regional head of tokenisation at CIMB Group Wholesale Banking. The key distinction between CIMB’s pilot and an earlier pilot conducted by Khazanah Nasional Bhd lies in how settlement occurred. CIMB’s pilot involved settling both the tokenised sukuk and tokenised deposits, meaning the financial asset and the cash were both settled on-chain — though the tokens mirror legal records that continue to exist within the traditional system. A tokenised deposit refers to a bank deposit recorded as a digital token on a blockchain, effectively representing commercial bank money in digital form. In contrast, Khazanah’s tokenised sukuk, which settled in mid-May, was paid for using fiat currency, or the ringgit, through traditional payment rails rather than blockchain. In that case, only the financial asset was settled on-chain, while the cash portion moved through conventional channels. “For our pilot, we created tokenised deposits to settle the tokenised sukuk, so both of these settlements are on the blockchain,” Wong said, adding that the blockchain used for the settlement is called CIMB Blockchain Connect. The digital asset custodian (DAC) involved in the pilot — the entity responsible for safeguarding clients’ tokenised assets — is not among the two DACs currently registered with the Securities Commission Malaysia (SC). “For this pilot, we cleared with the SC that a DAC licence is not required. We just need the ability to custodise these assets and the deposits,” Wong said during a press conference. What It Means for Ordinary People Wong explained that the central feature of the pilot is atomic settlement, where a buyer’s money and a seller’s asset change hands at exactly the same instant. She noted, however, that this concept holds limited relevance for individual consumers, who can already transfer and settle smaller sums instantly through existing payment infrastructure such as DuitNow. Settlement remains far from instantaneous in the institutional market, though. When large sums of money are sent overseas — for purposes such as funding a child’s education — the process can take several days as funds move through traditional channels involving multiple banks. “Now, with blockchain technology, if everyone is on the same blockchain, it happens literally instantaneously,” she said. The pilot nonetheless follows a “digital twin” approach, meaning the on-chain token mirrors traditional legal records rather than replacing them entirely; the process is therefore not conducted wholly on-chain. “The technological capability [for atomic settlement] is there, but are we ready to go [completely] instantaneous? We may not be ready just yet. Imagine, it is fine if it is RM100, but it is a different story if the amount is RM100 million, for a bank. Banks are looking for less friction, but not frictionless for now,” she said. Adopting a digital twin model means banks such as CIMB are investing in testing tokenised solutions through blockchain technology, even as traditional legal records and processes continue to run in parallel — meaning cost savings have yet to materialise. However, as more processes shift on-chain in the years ahead, banking operations could become faster and more efficient, while tokenisation could also help democratise asset classes by making them more accessible to retail investors. Making Financial Markets More Efficient According to a press release, the pilot was carried out as part of CIMB’s participation in Bank Negara Malaysia’s Digital Asset Innovation Hub, which offers a controlled environment for financial institutions to test new digital asset applications. CIMB has also been engaging with the SC on the broader development of tokenised capital market products. The completion of the pilot was announced at Menara CIMB in Kuala Lumpur, at an event attended by Finance Minister II Senator Datuk Seri Amir Hamzah Azizan. Amir Hamzah said the pilot demonstrates how Malaysia can build on its established strengths in Islamic finance and capital markets as financial infrastructure becomes increasingly digital. “Malaysia has developed deep capabilities in both Islamic finance and the capital markets. The next step is to ensure that these strengths continue to evolve alongside changes in technology and the way financial transactions are conducted. This pilot is important because it moves tokenisation beyond theory and tests how digital financial assets and commercial bank money can work together in a controlled environment. The objective is not digitalisation for its own sake, but to explore whether technology can make financial markets more efficient, transparent and connected while preserving strong standards of governance, investor protection and shariah compliance,” he said. Novan Amirudin, group chief executive officer of CIMB Group, said the pilot provided the bank and regulators with practical insights into the operational, legal and regulatory requirements involved in tokenised financial transactions. “This pilot allows us to test how tokenised financial assets can operate alongside existing market infrastructure and, importantly, how tokenised deposits can be used for settlement. The potential benefits are practical. Greater automation and faster settlement could reduce friction in financial transactions, improve liquidity management and increase capital efficiency. The experience gained from this pilot will help us assess how these capabilities can be developed further in Malaysia and, potentially, across regional and cross-border applications,” he said. Beyond Technology: Partnership

Energy & Technology

Factories Are Getting Smarter. Far East Paper Wants Smaller Businesses In The Race.

For decades, the economics of manufacturing have favoured scale. Bigger companies could afford better factories, more sophisticated machinery and greater automation. Smaller manufacturers competed with what they had. Far East Paper Products Sdn Bhd thinks that equation needs to change. The Malaysian company has spent almost half a century making products that rarely attract much attention but quietly keep industrial supply chains moving — paper cores, angle bars, edge protectors, paper pallets and other specialised packaging components. Now, it is preparing for something considerably more ambitious: taking some of the technologies transforming its own operations and making advanced automation more accessible to other SMEs. It is an unexpected next chapter for a company whose roots stretch back to 1976.   From Paper to Technology Far East Paper began as a paper core manufacturer. Today, it operates from a 170,000 sq. ft. facility producing customised, high-performance and 100% recyclable paper packaging solutions for corporate B2B customers. Its portfolio includes seamless industrial cores designed for demanding applications, alongside protective packaging and patented construction products such as FETUBE and FEPANEL. The company has received the FMM Excellence Award and maintains ISO 9001, ISO 14001:2015 and ISO 45001:2018 certifications covering quality, environmental management and workplace safety. Yet management increasingly describes its direction using terminology that sounds closer to technology than traditional manufacturing: Industrial Technopreneurship. Behind the phrase is a fundamental change in where Far East Paper believes manufacturing advantage will come from. Producing a quality product remains essential. But producing it consistently, efficiently and predictably — while using technology and data to continuously improve the process — is becoming equally important. The company is consequently investing R&D resources in Automated Storage and Retrieval Systems (ASRS), Automated Guided Vehicles (AGVs) and enterprise software designed to create a more connected digital manufacturing environment.   When Automation Changes the Worker Introducing technology into an established factory is not simply a matter of buying machines. Processes must change. More importantly, people must change with them. As a second-generation SME, Far East Paper has decades of manufacturing knowledge embedded within its workforce and operating culture. Its challenge is to preserve that knowledge while changing how the factory functions. Management developed what it calls the “Industrial Trinity” to guide the transition, combining traditional manufacturing expertise, digital infrastructure and physical automation. Crucially, the company does not position automation primarily as a means of eliminating workers. Instead, it wants to upskill employees who once operated conventional production processes into people capable of controlling increasingly sophisticated technological systems. In Far East Paper’s vision, the factory worker does not disappear. The job evolves.   Green Is Easy to Say, Harder to Manufacture A similar discipline underpins its sustainability strategy. Paper gives the company an obvious environmental proposition: its packaging solutions are designed to be recyclable. But Far East Paper argues that sustainability cannot stop at the material itself. Its “Reduce, Reuse, Recycle” approach has been supported through investment in its manufacturing facility and internationally recognised environmental and safety systems. That has required capital and, according to the company, a refusal to compromise standards simply to obtain cheaper materials. For industrial customers, such decisions are becoming increasingly relevant. A supplier’s environmental practices, certifications and material choices can affect the sustainability commitments and reputational risks of companies further along the supply chain. Going green, in other words, is becoming part of doing business.   What If SMEs Shared the Smart Factory? Far East Paper’s next project takes its transformation beyond its own factory. Under its TKS brand, the company plans to develop a 10.5-acre smart industrial hub in Selangor built around what it calls a “Shared Utility” model. The idea is to allow multiple SME tenants to access centralised advanced infrastructure, including ASRS and AGV capabilities, rather than requiring each company to make the entire investment independently. It attempts to solve an uncomfortable problem surrounding Industry 4.0. Manufacturers are constantly told they need to automate. But sophisticated automation demands capital, technical expertise, space and maintenance — precisely the resources smaller manufacturers often have less of. If Far East Paper’s model works, part of that barrier could be reduced. Instead of every SME having to build its own smart factory, some of the technology becomes shared infrastructure. It would represent a significant evolution for Far East Paper: from modernising its own manufacturing operations to creating an ecosystem that could help other manufacturers modernise theirs.   What Comes After Paper? There is another development the company is keeping deliberately under wraps. Its R&D team is working on a new product rooted in circular sustainability that, it says, will reconsider the environmental footprint associated with the final stage of the human life cycle. Details remain confidential ahead of its planned unveiling. The secrecy adds intrigue, but the larger story is already visible. A company that started with paper cores is now developing patented products, investing in automation, building shared smart-manufacturing infrastructure and exploring entirely new applications for sustainable materials. After nearly 50 years, Far East Paper’s challenge is no longer proving that it can manufacture paper products. It is proving how far the knowledge accumulated from making them can travel. And if its shared-factory experiment succeeds, Far East Paper may not just be automating its own future. It could help smaller manufacturers afford theirs.  

ESG

One Faulty Component Can Stop A Rig. DS7 Is Paid To Find It First.

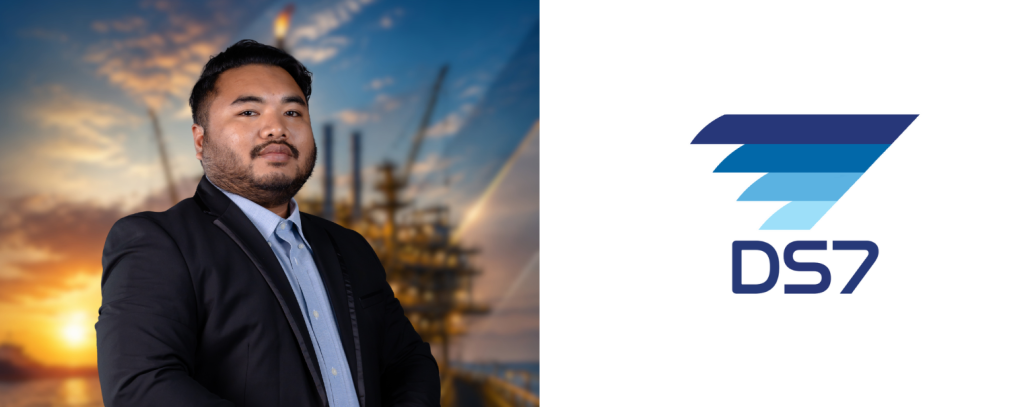
In the oil and gas industry, some of the most valuable work happens before anything goes wrong. A defect in a tubular or critical rig component may be barely visible. Left undetected, however, equipment problems can contribute to failure, interrupt drilling operations and create significant safety and operational risks. On an offshore or upstream operation where downtime is costly, prevention carries its own economics. General Manager & Director of DESA 7 Resources (M) Sdn Bhd – Syamil Arib. Finding those problems before equipment is deployed is the business of DESA 7 Resources (M) Sdn Bhd, better known as DS7. Established in 2009, the Malaysian company provides certified inspection, maintenance and asset integrity services to the upstream oil and gas sector, operating across Peninsular Malaysia, Borneo and Singapore. Its role sounds technical because it is. But the underlying proposition is straightforward: determine whether critical equipment is fit for use before it becomes a problem. DS7 inspects tubulars and rig components, helping customers identify equipment issues early, reduce the risk of failures and downtime, and maintain safer, more reliable operations throughout an asset’s lifecycle. In an industry built around increasingly sophisticated equipment and enormous capital commitments, that assurance has become progressively more valuable.   The Cost of Finding Out Too Late When DS7 entered the market, it identified a relatively practical gap: there were limited specialised local providers capable of independently inspecting critical drilling components with the accessibility and responsiveness operators required. More than 15 years later, the underlying need remains, but expectations have changed considerably. Customers still need technical competence. Now they also expect speed, traceability, transparency and increasingly digital evidence of what has been inspected and verified. Inspection itself is becoming more data-driven. DS7 has consequently been developing digital initiatives that improve the traceability and efficiency of its inspection and verification processes. The objective is not simply to tell a customer that equipment has passed inspection, but to strengthen the information and assurance surrounding that decision. The company operates with ISO 9001, ISO 29001 and ISO 45001 certifications, supporting its quality, sector-specific and occupational health and safety systems. For DS7, these disciplines matter because the product it ultimately sells is confidence.   Why Being Cheaper Isn’t Enough Growth has introduced another reality: competing on price becomes increasingly difficult as operations become more sophisticated. DS7 does not necessarily see that as a disadvantage. As upstream operations become more complex, the consequences of poor execution increase. The competitive conversation therefore shifts from the lowest inspection price towards reliability, safety, uptime and quality. It is a trade-off familiar across industrial services. A cheaper service can appear attractive when viewed as a line item. Its economics look rather different if inadequate execution contributes to disruption later. DS7 has therefore chosen to stay close to its core technical expertise rather than diversify aggressively into unrelated businesses. Its definition of growth centres on stronger technical capabilities, greater digital maturity and expansion within inspection and asset integrity, including international oil and gas markets. The company believes credibility is easier to protect when expansion remains anchored to what the organisation knows how to do well.   The Advantage Customers Rarely See Some of DS7’s differentiation is less technical than might be expected. The company says customers frequently value its responsiveness: how quickly teams adapt to changing requirements, communicate throughout an assignment and complete inspections without creating an unnecessary coordination burden. That agility becomes significant in operations where schedules can change quickly and delays cascade through other activities. Digitalisation is intended to reinforce that advantage by improving visibility, traceability and control. It also forms part of DS7’s wider approach to ESG. Rather than treating sustainability purely as a reporting requirement, the company has begun incorporating it into everyday operations. Environmental initiatives include reducing waste and managing electricity and fuel consumption. On the social side, DS7 continues to invest in employee training and development, educational contributions, CSR activities and employee engagement. Governance measures include more structured customer feedback and complaints management, stakeholder feedback, risk management and greater ESG awareness internally. The common thread is operational discipline. For DS7, responsible growth means that becoming larger cannot come at the expense of how safely or transparently the company operates.   An Oil and Gas Company Preparing for What Comes After There is, however, a larger question hanging over almost every company whose expertise has been built around hydrocarbons: what happens as the energy system changes? DS7 is not abandoning oil and gas. Quite the opposite. It intends to deepen its inspection and asset integrity capabilities within the upstream sector and expand its presence beyond Malaysia into Southeast Asia. But management is also beginning to explore opportunities in renewable energy and adjacent sectors. The strategy is gradual rather than abrupt. Instead of chasing diversification for its own sake, DS7 wants to determine where the technical disciplines it has developed — inspection, verification, safety and asset integrity — can remain relevant as the energy landscape evolves. That transition will demand internal changes. Processes will need to become more standardised if DS7 is to deliver consistent quality across multiple countries. Technical and leadership capabilities will have to deepen. Digital systems and governance structures will need to support a larger and geographically broader organisation. In other words, regional expansion will depend as much on what happens inside DS7 as where it goes next. There is an interesting irony to the company’s position. Its business has been built on finding weaknesses before they become failures. Now DS7 is applying a similar philosophy to itself: strengthening systems, developing people and preparing for changes in the energy market before they become urgent. The oil and gas industry may be changing, but equipment will still need to work, infrastructure will still need to be trusted and increasingly complex energy assets will still need to be inspected. For DS7, that creates a path forward. Because whether the asset belongs to today’s energy industry or tomorrow’s, someone still has to find the problem before the problem finds everyone else.  

Investment & Market Trends

Yinson Targets Global FPSO Leadership Amid Energy Transition

Petroliam Nasional Bhd (Petronas), the Employees Provident Fund (EPF) and the founding Lim family of Yinson Holdings Bhd (KL:YINSON) are reportedly in talks to take the oil-and-gas company private, according to sources. The three parties are said to be forming a consortium to buy out Yinson, which owns one of the world’s largest fleets of floating production storage and offloading (FPSO) vessels, according to people familiar with the matter. A deal could be announced soon. Petronas and the Lim family did not respond to requests for comment from The Edge, while the EPF declined to comment. Yinson currently operates nine floating assets, with two more on order across Southeast Asia, South America and Africa. The company’s executive chairman, Lim Han Weng, and his family hold a 27.68% stake in the firm, while the EPF owns 17.09%. Another substantial shareholder is Retirement Fund Inc, the pension fund for civil servants better known as KWAP, which holds 6.84% of Yinson. Petronas also runs its own FPSO business through MISC Bhd (KL:MISC). The 51%-owned unit operates six FPSOs, five floating storage and offloading vessels, and one floating production and storage facility across Malaysia, Thailand, Vietnam and Brazil. In 2024, MISC held talks with Bumi Armada Bhd (KL:ARMADA), which operates seven assets, to merge their respective FPSO businesses. The proposal was mutually called off in August 2025 after both parties concluded it would not fully achieve their intended objectives. Yinson has previously featured in reports over potential privatisation. In June 2025, the company said its major shareholders were in exploratory discussions with “various parties with reference to potential corporate proposals regarding their shareholdings.” At the time, reports indicated that the Lim family was in talks with New York-based investment firm Stonepeak Partners to take the company private. Those plans, however, were withdrawn earlier this year. Beyond its FPSO operations, Yinson also owns renewable energy assets with a combined 557-megawatt capacity currently in operation, along with another 148 megawatts under construction across India, Peru and New Zealand. The company additionally operates electric vehicle charging stations in Malaysia and Singapore. Yinson, which posted a net profit of RM683 million and revenue of RM5.4 billion for the financial year ended Jan 31, 2026 (FY2026), first entered the FPSO business in 2011 in Vietnam, where it builds and leases out floating vessels used in offshore oil and gas production. The company became a major FPSO player in mid-2013 after acquiring Norwegian FPSO firm Fred Olsen Production ASA for RM551.3 million, and now holds stakes in offshore assets across Brazil, Ghana, Nigeria, Angola, Malaysia and Vietnam. The EPF, which manages the retirement savings of Malaysia’s private sector employees, emerged as a major shareholder of Yinson in 2015 — the same year the company secured its first major contract with Italian oil major Eni for the supply of an FPSO vessel in Ghana, worth US$2.54 billion. Shares of Yinson closed at RM2.22 on Thursday, giving the company a market capitalisation of RM7.14 billion.

ESG

The Old Manufacturing Playbook Is Dying. Cooltec Is Already Rewriting It.

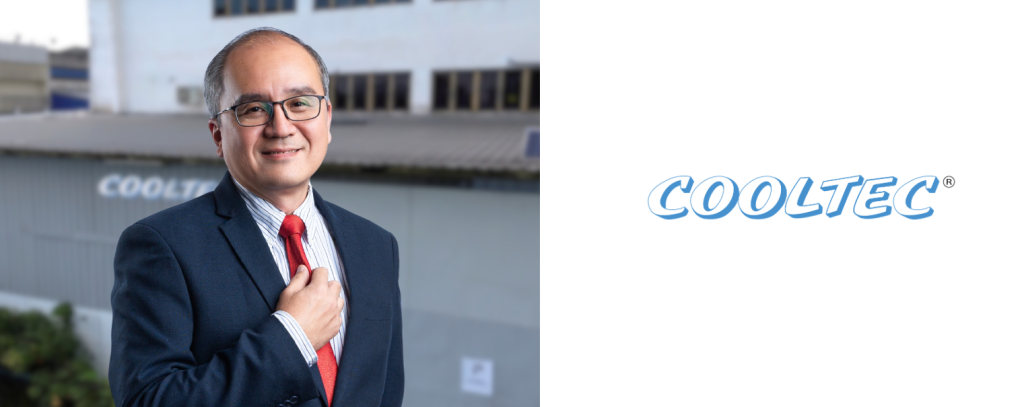
For almost 30 years, Cooltec Industries Sdn Bhd has watched the rules of manufacturing change around it. The Malaysian company began in 1996 as a modest automotive air-conditioning service provider. Today, it is an industrial group spanning manufacturing, assembly, formulation and distribution, serving automotive, consumer and household, electrical and electronics, and gifts and souvenirs markets in Malaysia and abroad. Managing Director of Cooltec Industries Sdn Bhd – Mr. KK Yeaw. But the model that helped build manufacturing businesses such as Cooltec is coming under pressure. Labour is harder to secure. Customers are relocating production. Overseas manufacturers have scale and technology advantages. Electric vehicles are changing automotive supply chains. Sustainability expectations are rising. And automation is turning from competitive advantage into industrial necessity. For Cooltec, standing still is no longer an option. The company is responding by attempting something more difficult than simply expanding: changing the kind of manufacturer it wants to become.   When Cheap Is a Losing Strategy One decision illustrates that shift particularly clearly. Cooltec is deliberately moving away from declining products and low-demand markets — and it has little appetite for competing solely on price in commoditised segments. There is a practical reason. Manufacturers in larger overseas markets can bring formidable advantages in volume, cost and technology. Trying to beat them at their own game can become a race towards thinner margins. Cooltec’s alternative is differentiation. Its strategy increasingly centres on technical capabilities, automation, process improvement, specialised products and markets where quality and reliability matter alongside price. That thinking is particularly relevant to automotive manufacturing. As the industry moves towards electric vehicles, Cooltec sees the competitive gap shifting from basic production capability towards precision, automation and smarter manufacturing. Overseas companies currently possess significant technological advantages, raising the stakes for Malaysian suppliers seeking to remain part of future automotive supply chains. Cooltec is responding with projects including automated visual inspection, fully and semi-automated production machinery and paperless data-logging systems. Automation is not simply about making the factory faster. It is becoming part of how the company manages another structural challenge: people. The Labour Problem Isn’t Going Away Manufacturing has traditionally depended heavily on manual labour, including foreign workers. Cooltec says tighter labour availability and regulatory constraints have made that dependency increasingly difficult. As the business grows, finding people with the right technical capabilities has become harder rather than easier. The company is consequently approaching the problem from both directions: automating processes where possible while investing in upskilling and reskilling the people it already has. That represents a broader change in what growth means to Cooltec. Becoming bigger is no longer enough. The company wants to become more productive, specialised and resilient — even if that means walking away from business that adds volume without strengthening its long-term position.   From Car Parts to Durian Leaves Perhaps the more unexpected expression of Cooltec’s transformation sits far away from the production of automotive components. Through its MyLEAF brand, the company has been experimenting with turning natural materials, including rubber and durian leaves, into premium gifts. It may seem an unusual extension for a precision manufacturer. But it reflects Cooltec’s attempt to combine manufacturing capability with circular-economy thinking and the commercialisation of underutilised materials. The company identified traditional rubber-leaf handicrafts as an area constrained by manual production, high costs and limited scalability. Its response has been to explore how design, production methods and branding could turn the concept into a more commercially viable product. MyLEAF has obtained SIRIM ECO 009:2019 and Circular Economy Certification, while Cooltec is also pursuing MyHIJAU recognition. The initiative sits within a much wider sustainability programme. Cooltec maintains six management and certification systems spanning automotive quality, general quality management, environmental management, occupational health and safety, eco-labelling and circular economy practices. It is also preparing sustainability reporting despite such disclosure not yet being mandatory for many SMEs. For management, the certifications are intended to be more than plaques on a wall. The company says they provide the internal discipline governing how quality, safety and environmental considerations are managed across daily operations. That discipline has commercial consequences too. Cooltec points to eight projects awarded by Perodua as evidence that its emphasis on quality, compliance and capability is being recognised by customers.   Growth Gets Expensive Transformation, however, requires capital. Automation requires machinery. Larger orders consume working capital. New capabilities require training. And expanding production eventually creates another unavoidable problem: where to put everything. Cooltec says its existing facilities are increasingly constrained by space, prompting consideration of new properties, factory reorganisation and more sophisticated layout planning. Financing those investments while protecting cash flow has made financial discipline increasingly important. It is a reminder that scaling an industrial company is very different from simply selling more products. Each stage of growth can demand another layer of capital, infrastructure, people and systems before the return becomes visible.   The Next Problem Is Succession Yet the company’s biggest long-term challenge may have little to do with machinery. Cooltec is now thinking seriously about who will lead the business next. Its ambition is to develop a capable next-generation successor while transferring knowledge and decision-making away from individuals and into a stronger institutional structure. That requires formal leadership development, better knowledge transfer and management systems capable of surviving a generational transition. For a company approaching its fourth decade, it may be one of its most consequential transformations. Cooltec has already reinvented itself once, moving from automotive air-conditioning services into a diversified manufacturing group. Now it is attempting another transition — towards automation, higher-value manufacturing, sustainability and a less labour-dependent operating model. The pressures driving that transformation are unlikely to disappear. EVs will continue reshaping automotive supply chains. Automation will accelerate. Environmental expectations will rise. And low-cost competition will remain relentless. For established manufacturers, longevity alone offers little protection. The businesses that survive the next industrial cycle may be those willing to abandon parts of the playbook that made them successful in the last one. After almost 30 years, Cooltec’s biggest challenge is no longer

Scroll to Top

Subscribe
FREE Newsletter