Investment & Market Trends

Investment & Market Trends

PublicInvest positive on Farm Price Holdings’ expansion, earnings outlook

KUALA LUMPUR: Public Investment Bank Bhd (PublicInvest) is seeing a positive outlook for Farm Price Holdings Bhd’s (FPHB) expansion plans, particularly its enlarging operational facilities to expand its market coverage for business growth and enhance its supply chain in fresh vegetables. In a report, PublicInvest highlighted several developments that are expected to fuel FPHB’s growth in the near future. These include building more facilities in Senai, Johor, expanding areas for value-added processing, buying new machinery and equipment, increasing their transportation fleet, setting up an additional regional distribution centre, and establishing a sales and marketing office in Singapore. Further, PublicInvest noted that FPHB also has several competitive advantages, which include an established track record, a broad range of products along with value-added services, well-developed supporting infrastructure, a wide network of suppliers to reduce the risk of supply disruptions, a dual-channel distribution system, and an experienced management team. The bank-backed research firm said as of March 27, 2024, FPHB had about 980 stock-keeping units (SKUs) of fresh vegetables. This inventory includes around 510 SKUs of whole fresh vegetables, 320 SKUs of pre-packed vegetables, and 150 SKUs of fresh-cut vegetables. The pre-packed vegetables are mostly sold under FPHB’s brands, Farm Price and TLC Fresh, along with some brands owned by customers. Fresh-cut vegetables are primarily sold to foodservice operators and wholesalers. A small amount of these are also marketed under the Farm Price brand, but none under third-party brands. PublicInvest said that as of March 27, 2024, FPHB’s Senai Centralised Distribution Centre spans 78,721 square feet, including 24,066 square feet of cold room facilities for storage, processing, and packing, alongside areas for ambient temperature storage. The company plans to expand this centre by building additional structures on a 1.9-acre plot purchased in 2023, directly behind the existing facilities. The planned expansion includes a 2-storey operational building with office and cold room facilities, a 4-storey accommodation block for workers, and a covered workshop. When completed, the expanded area will be approximately 84,790 square feet, which includes an extra 4,000 square feet of cold room space. This will increase the centre’s capacity from handling 29,669 pallets per year to about 40,000 pallets per year by 2026. On the same date, an architect was hired to prepare the building plan submission, and the new operational building is expected to start operations by the first quarter of 2026. Additionally, FPHB intends to grow its processing capabilities by adding around 4,000 square feet of floor space at the Senai Centre, particularly to enhance its range of value-added products such as pre-packed and fresh-cut vegetables. The related renovations, which will expand the processing area and the cold room facilities, are set to start in the third quarter of 2025 and should be completed by the end of the fourth quarter of 2025. Touching on earnings forecast, PublicInvest said while FPHB’s current facility is operating at full capacity, the research firm anticipates that the company’s growth will be supported by new distribution centres in Cameron Highlands and Nilai. These centres are expected to start operating in the fourth quarter of 2024. Additionally, FPHB can increase its production capacity by adding extra processing shifts and making more delivery trips if needed. “As a result, we are projecting that FPHB’s core net profit will grow by an average of 18 per cent in the financial years 2024-2025. “This growth is expected to come from better economies of scale, expansion into new geographical areas, and improvements in the supply chain with the start of the new distribution centres,” PublicInvest noted. “FPHB’s net gearing ratio currently stands at 0.4x. We expect the company to be in a net cash position after IPO,” the firm noted.

Microsoft chief executive officer, Satya Nadella
Investment & Market Trends, News

Microsoft Plans to Invest US$1.7 Bil in Indonesia

JAKARTA: In a significant move, US tech titan Microsoft has declared a substantial investment in Indonesia during the visit of its CEO to Jakarta for discussions with governmental representatives. The company has revealed plans to inject a hefty sum of US$1.7 billion over the next four years into the country’s infrastructure for cloud computing and artificial intelligence (AI), alongside initiatives to provide AI training for 840,000 individuals and bolster support for the burgeoning developer community. Highlighting the importance of this investment, Communications and Information Minister Budi Arie Setiadi emphasized its crucial role in Indonesia’s digital progress. He remarked that Microsoft’s commitment signals recognition of Indonesia’s significance within the global digital landscape. The establishment of a research and development center, slated for either Bali or the new capital city being developed in Kalimantan, aims to cultivate AI expertise within the nation. Minister Setiadi underscored the transformative potential of AI technology in enhancing productivity across various sectors, including agriculture and fisheries, thereby driving economic growth. Microsoft’s projections suggest Indonesia’s leading role in AI’s contribution to the national GDP by 2030 within the Southeast Asian region, contingent upon overcoming challenges such as digital proficiency gaps and data governance issues. Microsoft’s CEO, Satya Nadella, reiterated the company’s commitment to empowering individuals and organizations in Indonesia to leverage the upcoming AI advancements. Nadella announced ambitious training targets, aiming to equip 2.5 million individuals across the ASEAN region by 2025, with a significant portion allocated to Indonesia. This investment represents a milestone in Microsoft’s nearly three-decade presence in the country, marking a significant step towards fostering digital innovation and economic growth.

Investment & Market Trends, News

McDonald’s Profits Significantly Affected Due to Hampered Sales from Middle East Conflict

McDonald’s fell short of quarterly profit expectations for the first time in two years, with cost-conscious consumers overlooking its promotions and international sales hampered by the Middle East conflict. Global comparable sales growth continued its decline for the fourth consecutive quarter, settling at 1.9%, as consumers tightened their purse strings, emphasizing value in their spending habits. Analysts, relying on LSEG data, had anticipated a 2.35% increase. CEO Chris Kempczinski acknowledged the discerning nature of today’s consumers during a post-earnings call, noting that all income brackets are prioritizing value. This trend contrasted sharply with other fast-food chains, such as Burger King-owner Restaurant Brands International, which exceeded quarterly expectations, and Domino’s Pizza, which capitalized on pizza offers. Despite raising prices by mid- to high-single-digit percentages to offset rising costs, McDonald’s observed a diminishing affordability advantage in some markets. In the United States, first-quarter same-store sales growth decelerated to 2.5%, significantly lower than the previous year’s 12.6% surge. Internationally, the picture was mixed, with comparable sales from the company’s international licensees dipping by 0.2%, contrary to expectations of a 0.98% increase. McDonald’s CFO Ian Borden had forewarned of this downturn, citing the Middle East conflict and sluggishness in the Chinese economy. The Middle East conflict has put pressure on US brands like McDonald’s, leading to protests and boycotts. In response, the company bought back its 30-year-old Israel franchise and addressed legal concerns in Malaysia over allegations of supporting Israel. Analysts, such as Jim Sanderson from Northcoast Research, highlighted the uncertain impact of the Middle East conflict on US brands operating internationally, posing risks to their income streams. McDonald’s adjusted per-share profit of US$2.70 missed estimates by two cents, attributed partly to a 10% rise in selling, general, and administrative expenses, driven by investments in digital infrastructure and restructuring efforts. Despite the disappointing results, McDonald’s shares remained relatively stable on Tuesday. — REUTERS

Investment & Market Trends, News

Growth Outlook on Asia and Pacific Regions Improved to 4.5%

SINGAPORE: The International Monetary Fund (IMF) has improved its Asia and Pacific region growth forecast to 4.5% this year, up 0.3 percentage points from the previous projection in October, partially due to carryover from stronger 2023 outruns and policy support. The United Nations agency said the region remains inherently dynamic and will contribute about 60% of global growth this year. The growth forecast for Asia and the Pacific in 2025 will moderate to 4.3%, unchanged from the October projection, with the structural slowdown in China a key factor, it said. IMF also improved its 2024 outlook for Malaysia to 4.4%, up 0.1 percentage point from the previous projection. “Drivers of growth are as diverse as the region, reaching from resilient domestic consumption in most ASEAN countries to strong public investment in China and most notably, in India, as well as a sharp uptick in tourism in the Pacific Island countries,” said IMF Director for Asia and Pacific Department Krishna Srinivasan. He said this at a hybrid press conference on the release of ‘The Regional Economic Outlook, Asia Pacific: Steady Growth Amid Diverging Prospects’ report. According to the IMF, inflation is projected to converge to central bank targets by the end of 2024 in most of the region and output gaps are also expected to narrow, conditional on macroeconomic policies staying the course. “Disinflation has advanced throughout the region albeit at different speeds. In some countries, it remains above target, like Australia and New Zealand. In others, it is at or closer to central bank targets for example, in emerging markets and Japan. However, there are also risks of deflation like Thailand and China,” Srinivasan said. Meanwhile, the IMF said China continues to be a source of both upside and downside risks to the macroeconomic outlook in the region. Against this backdrop, Srinivasan noted that policies aimed at addressing stresses in the property sector and boosting domestic demand will help China and the region while sectoral policies contributing to excess capacity will hurt both. He also said that Asian central banks should continue to focus on domestic price stability and avoid making policy decisions overly dependent on anticipated interest rate moves by the US Federal Reserve as they are now better placed than before to cope with exchange rate movements. “They should continue to allow the exchange rate to act as a buffer against stocks,” he said. Meanwhile, in a related blog post, Srinivasan said that Asian governments need to pursue policies to reduce debt and deficits with greater urgency as progress last year fell behind what the agency had originally projected. “Our forecasts show that on current fiscal plans, debt ratios would stabilise for most economies, provided governments underpin these plans with concrete policies and follow through on them. But even then, debt would remain significantly higher than it was before the pandemic,” he said. Srivinasan added that governments need to streamline expenditures and raise more revenue to reduce debt levels and curtail debt service costs. He also noted that policymakers should be cautious to not aggravate trade frictions themselves as global conflict poses additional risks to trade, as proven by the rerouting of ships around Africa to avoid the Red Sea, which raises shipment costs. “For Asia’s economies, these are unfortunate developments, as many of them are deeply integrated into global supply chains and benefit greatly from trade. Pacific island countries are especially affected, as they are highly dependent on imports and poorly integrated into global shipping networks,” he added. — BERNAMA

Investment & Market Trends, News

Airbus, Positioned to Enhance Malaysia’s Defense Capabilities

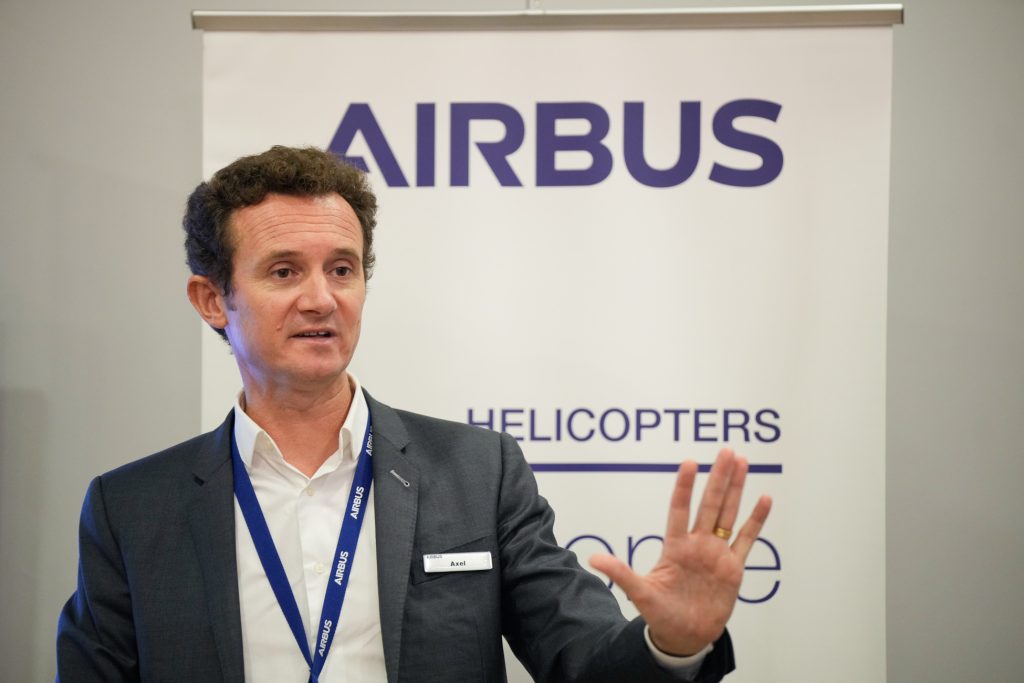
KUALA LUMPUR: Airbus Helicopters reaffirms its commitment to bolstering its current collaborations and network in Malaysia while striving to uphold its dominant position in the market. Addressing reporters at Airbus’ helicopter facility in Subang, Axel de Pascal, Managing Director of Airbus Helicopters Malaysia, emphasized the significance of Malaysia as a key market for the company. Airbus, the European helicopter manufacturer, aims to incrementally expand its market share over the next five years, particularly in the military sector. “We anticipate a rise in military requirements for specialized operations, search-and-rescue missions, and tactical transport within Malaysia and the surrounding region. Our combat-proven multi-role H225M is ideally suited to fulfill a wide spectrum of mission needs,” remarked De Pascal. The H225M is presently contracted by ten military forces globally, with over 170 units delivered, over 40 on order, and an additional 50 supporting governmental agencies in search and rescue missions. Four of these ten H225M military customers are situated in the Asia-Pacific region, including Malaysia. The extensive utilization of the H225M underscores its effectiveness as a force multiplier, enabling swift deployment in diverse weather conditions. Furthermore, numerous operators employ the versatile helicopter for various civil and parapublic missions. The Royal Malaysian Air Force (RMAF) presently operates 12 H225M helicopters from bases in Kuantan and Labuan. Tailored for the most demanding missions, these multi-role H225Ms have actively engaged in numerous military exercises and humanitarian missions over the past decade, including flood rescue operations, pandemic aid delivery, and life-saving missions. The RMAF’s H225M fleet has achieved global recognition as the highest military flyer per aircraft, accumulating over 30,000 flight hours to date. Under Budget 2024, the RMAF has been allocated funding to procure an additional 12 helicopters. Airbus stands ready to propose its H225M for consideration when the time arises. “Malaysia is already well acquainted with the capabilities of the H225M, and stands to benefit from a unified fleet with immediate operational readiness and reduced operational expenses,” added De Pascal. De Pascal reiterated that any expansion in military capabilities would inevitably lead to an expansion of the company’s existing partnerships and ecosystem. “We are confident that the additional H225M helicopters will complement the RMAF’s existing fleet. With an established ecosystem in place, the introduction of additional assets will significantly enhance the air force’s efficiency across all levels.” Airbus has continuously invested in modernizing the multi-role H225 workhorse to align with evolving mission requirements, elevating it to the highest safety standards and reducing its time to market. Recent investments have focused on upgrading the main gearbox, enhancing industrial processes, simplifying maintenance procedures, and improving cost-effectiveness. “With new infrastructural enhancements incorporated into the H225’s industrial process, production will extend beyond 2040, ensuring stability and sustained fleet support for decades to come.” “There are considerable opportunities for the H225M. Airbus is confident that this helicopter platform will become a vital enabler, complementing Malaysia’s existing fleet seamlessly.”

Investment & Market Trends, News

CIMB Group Achieves Forward23+ Targets Amid Uncertainties

KUALA LUMPUR: CIMB Group Holdings has achieved its Forward23+ targets despite external uncertainties, reaffirming its commitment to becoming the leading focused ASEAN bank. Speaking at the company’s 67th annual general meeting (AGM) virtually with shareholders, the group’s Chairman Datuk Mohd Nasir Ahmad said that with the varied challenges in the banking industry in 2023, CIMB marked an exciting phase as the Forward23+ strategic plan continued to gain strong momentum. “For the second consecutive year, we have achieved the top quartile within the global banking industry in the S&P Global Corporate Sustainability Assessment, achieving our Forward23+ targets 2 years ahead of the plan. “Among 400 international financial institutions, CIMB ranked 7th worldwide in the 2023 Financial System Benchmark. “These recognitions reinforce our ongoing sustainability agenda and leadership as we strive for sustainable growth to unlock new possibilities and opportunities into the future,” he said in a statement filed with Bursa Malaysia. Meanwhile, CIMB Group’s Chief Executive Officer Datuk Abdul Rahman Ahmad said the bank made significant progress under the Forward23+ strategic plan and is on track to deliver the targets across most profitability metrics set under the plan 4 years ago. “As we enter the final year of Forward23+, our focus is to enhance current account savings account (CASA) and deposit franchise with an emphasis on effective balance sheet management to improve net interest margin regionally. “Further, we intend to maintain non-interest income growth through wealth management and affluent segment, as well as to continue our cost discipline and improve asset quality to deliver our ambitious 2024 targets,” he added. CIMB Group saw continued positive momentum in the financial year ended 31 December 2023 (FY23), driven by strong underlying performance across all business segments and geographies. Over the past 2 years, the Group has achieved cumulatively RM86.2 billion of sustainable finance under the group’s Green, Social, Sustainable Impact Products and Services (GSSIPS) Framework, inching closer to its revised sustainable finance target of RM100 billion by 2024, tripled from the initial target of RM30 billion announced in 2021. — BERNAMA

Investment & Market Trends, News

MKH Oil Palm Berhad Makes Successful Main Market Debut

KUALA LUMPUR: MKH Oil Palm (East Kalimantan) Berhad, known as MKHOP, has successfully entered the Main Market of Bursa Malaysia Securities Berhad. The company’s stock, categorized under the plantation sector, is listed as MKHOP with the stock code 5319. Its initial share price opened at 63 sen, reflecting a 1.6% premium over the issue price of 62 sen, with an initial trading volume of 12,134,600 shares. Tan Sri Dato’ Chen Kooi Chiew, the Non-Independent Non-Executive Chairman of MKHOP, highlighted the significance of this milestone, emphasizing the company’s commitment to long-term growth. With proceeds of RM136.4 million from the IPO, MKHOP plans to expand its plantation estates, enhance operational efficiency, diversify product offerings, and invest in sustainability initiatives, including improving living conditions for its workforce and reducing reliance on diesel generators.   Given the current El Nino dry weather conditions affecting global CPO supply and supporting CPO prices, MKHOP is focusing on improving production efficiency to capitalize on favorable market conditions. The company expresses confidence in the long-term growth prospects of the oil palm industry, driven by global population growth and increasing demand for edible oils and fats.   MKHOP’s financial performance for the first six months of 2024 remained robust, with a net profit of RM26.5 million and revenue of RM168.4 million. The company also maintained healthy cash and bank balances of RM89.6 million as of March 31, 2024.   M & A Securities Sdn Bhd acted as the Adviser, Managing Underwriter, Joint Underwriter, and Joint Placement Agent for the IPO, with Kenanga Investment Bank Berhad and AmInvestment Bank Berhad serving as Joint Underwriter, Joint Placement Agent, and Joint Placement Agent, respectively.

Investment & Market Trends, News

Farm Price Holdings Berhad’s 85.4% Potential Upside

With two decades of unwavering commitment to wholesale fresh vegetable distribution, Farm Price Holdings Bhd (FPHB) stands as a pillar of reliability in the staple food industry. Positioned within the crucial narrative of food security, analysts anticipate FPHB to ride the wave of growth in the Johor-Singapore corridor. Projections for FY24-25f showcase robust bottom-line growth of 16.6-25.1%, reaching RM10.1-12.7 million, buoyed by strategic operational expansions to meet escalating customer demands. Analysts have assigned a fair value of RM0.445 for FPHB, underpinned by a forward P/E of 15.7x aligned with peers in the Packaged Foods sub-industry. Addressing current capacity constraints, FPHB is swiftly adapting to surging demand, evident in its cold room facilities operating at over 95% capacity. Short-term measures, including increased processing shifts and flexible infrastructure utilization, will ensure timely delivery of fresh produce, translating into significant top and bottom-line growth. Expansion initiatives for exponential growth include the utilization of IPO proceeds to expand SCDC, augmenting floor space by 90% by FY26. This strategic move will bolster operational efficiency, adding 54k sqft to operational areas, enhancing cold room capacity by 35%, and accommodating up to 40k pallets annually, laying a robust foundation for sustained growth. Despite challenges in FY20-22, including margin pressure due to fixed pricing contracts amidst rising vegetable costs, FPHB anticipates stable margins akin to FY23 levels, with an optimistic outlook for normalized pricing dynamics. Leveraging its track record, FPHB enjoys a competitive edge in securing new customers, particularly in Singapore. Operating from Malaysia, FPHB leverages lower production costs and SCDC’s strategic location to ensure freshness and prompt delivery, outshining its Singaporean counterparts. Ongoing discussions with potential clients underscore FPHB’s prowess in leveraging its reputation and competitive advantages for continued market penetration in Singapore. In essence, FPHB’s journey as a staple food provider epitomizes resilience and growth potential, poised to capitalize on emerging opportunities and fortify its position in the dynamic food distribution landscape.

Investment & Market Trends, News

Kawan Renergy Berhad Set to Raise RM33.0 Million in IPO En Route to ACE Market Listing

KUALA LUMPUR: Engineering solutions provider Kawan Renergy Berhad has announced the successful launch of its prospectus, marking a significant step towards its upcoming initial public offering (IPO) and listing on the ACE Market of Bursa Malaysia Securities Berhad. Kawan Renergy Group, comprising subsidiaries Kawan Engineering Sdn Bhd and Kawan Green Energy Sdn Bhd, specializes in designing, fabricating, installing, and commissioning industrial process equipment, process plants, and renewable energy and co-generation plants. Their solutions cater to diverse industries such as food processing, oleochemical and chemical processing, oil and gas, waste recovery, power plant, and utilities. Additionally, the Group is engaged in power generation and the sale of electricity.   Managing Director Ir. Lim Thou Lai noted that the prospectus launch is a significant milestone for Kawan Renergy as it progresses towards becoming a publicly listed entity. The IPO is integral to their long-term growth strategy, facilitating additional funding to support ongoing and future projects, and expand their power generation and electricity sales segment.   Based on an Independent Market Research Report by Smith Zander International Sdn Bhd, Malaysia’s industrial process equipment industry saw substantial growth from RM15.6 billion in 2020 to RM23.5 billion in 2023, with a compound annual growth rate (CAGR) of 14.6%. With increasing foreign direct investment (FDI) inflows, industries like power generation, oil and gas, and manufacturing are expected to expand, benefiting the industrial process equipment sector. The Group is optimistic about the industry’s prospects.   Ir. Lim outlined the Group’s plans for the IPO proceeds, which include allocating a significant portion towards supplementing working capital for ongoing and future co-generation plant projects. Additionally, investments are earmarked for constructing a new biomass power plant and enhancing the production output of the Bercham Plant, a landfill biogas power plant. A portion of the proceeds will also go towards repaying bank borrowings and defraying listing expenses.   Mr. Gary Ting, Head of Corporate Finance at M & A Securities Sdn Bhd, expressed confidence in Kawan Renergy’s capability to expand its market share with the successful listing. He highlighted the potential benefits of the listing, including enhancing the Group’s reputation, expanding visibility, and attracting talent.   The IPO exercise comprises a public issuance of new ordinary shares, representing 20.0% of its enlarged share capital, as well as an offer for sale of existing shares. A portion of the new shares will be available to the Malaysian public via balloting, with allocations for eligible Directors, employees, and contributors to the group’s success. Selected Bumiputera investors approved by the Ministry of Investment, Trade and Industry will also have access to a portion of the shares.   Upon listing, Kawan Renergy’s market capitalization is estimated to be approximately RM165.0 million, based on the IPO price of RM0.30 per share and its enlarged issued shares. The Group has demonstrated robust financial performance, with revenue and net profit experiencing significant growth over the past three years.   Applications for the public issue are currently open and will close on 14 May 2024, with the Group scheduled to be listed on the ACE Market of Bursa Securities on 29 May 2024. M & A Securities Sdn Bhd is serving as the Principal Adviser, Sponsor, Underwriter, and Placement Agent for the IPO exercise.

Investment & Market Trends, News

Malaysia-China Trade Strengthens 3.3%, Reaching RM112 Billion

KUALA LUMPUR: Malaysia’s total trade with China increased 3.3% year-on-year to over RM112 billion in the first quarter of this year, according to the Malaysia External Trade Development Corporation (MATRADE). Chairman Datuk Seri Reezal Merican Naina Merican said during the period, Malaysia recorded RM44.5 billion worth of exports to China with electrical and electronics (E&E) products being the biggest exports. In his keynote speech during the 21st China-ASEAN Expo (CAEXPO) promotional conference, Reezal said that E&E products made up 32.6% of the country’s total exports to the world’s second-largest economy. Meanwhile, imports were valued at RM67.78 billion comprising intermediate goods meant for the manufacture of products for exports such as E&E products, machinery, equipment and parts as well as chemicals and chemical products. Reezal said that China remained Malaysia’s largest trading partner and primary source for imports last year, while Malaysia was China’s 10 largest global trading partner as well as the second largest trading partner within ASEAN. On CAEXPO 2024, he said that MATRADE is targeting 150 Malaysian companies to join the event, which will be held from 24-28 September this year in Nanning, China. “This year would be special for Malaysia, as we have been invited to be the country of honour and the Malaysian Pavilion will be given special highlights. We will have a significantly larger pavilion to provide ample space for Malaysian companies to showcase a wider range of offerings,” Reezal announced, highlighting that the CAEXPO is a golden opportunity for Malaysian companies to tap into the China market. Last year, the Malaysia Pavilion – officiated by Prime Minister Datuk Seri Anwar Ibrahim – recorded a total sales of RM625.42 million and saw seven memoranda of understanding signed for further potential sales. — BERNAMA

Scroll to Top

Subscribe
FREE Newsletter