Investment & Market Trends

Investment & Market Trends

Public Bank To Buy Out Hong Kong Unit At HK$2.50 Per Share

Public Bank Bhd has proposed to take its Hong Kong-listed subsidiary, Public Financial Holdings Ltd (PFHL), private by purchasing the remaining shares it does not already own for HK$2.50 (RM1.29) per share. Public Bank currently holds a 73.23% stake in PFHL and plans to acquire the remaining 26.77%, representing approximately 293.9 million shares, for a total of HK$734.75 million. According to a filing with Bursa Malaysia, the bank confirmed that the offer price is final and will not be increased. The proposed privatisation will be carried out through a court-approved arrangement, under which shares held by minority shareholders will be cancelled and replaced with new shares issued to Public Bank. Once completed, PFHL will become a wholly-owned subsidiary of Public Bank. The HK$2.50 offer represents a 61.29% premium over PFHL’s last traded share price of HK$1.55 on 19 August 2026. It is also 83.82% higher than the company’s average closing price of HK$1.44 over the previous 360 trading days. However, the offer price is 64.64% below PFHL’s unaudited net asset value of HK$7.08 per share as of 30 June 2026. Trading in PFHL shares has been suspended since 20 August, pending the announcement. PFHL operates several financial businesses, including banking, stockbroking, investment property leasing and vehicle financing. Its banking operations cover 29 branches in Hong Kong and one branch in China. Public Bank said the proposal provides minority shareholders with an opportunity to sell their shares at a premium, particularly as PFHL’s shares have historically traded at significant discounts to their book value. The bank added that taking PFHL private would help reduce listing expenses, simplify the group’s corporate structure and allow greater focus on its core banking operations. It also expects the move to contribute positively to future earnings. For the first six months ended 30 June 2026, PFHL recorded a net profit of HK$25.19 million, compared with HK$2.57 million during the same period last year. Operating income increased slightly to HK$692.22 million from HK$685.16 million. For the financial year ended 31 December 2025, PFHL returned to profitability with a net profit of HK$79.65 million, reversing a net loss of HK$999.39 million in 2024. The proposed privatisation remains subject to several conditions, including approval from at least 75% of the votes cast by eligible minority shareholders at a court-convened meeting. Meanwhile, Public Bank shares closed unchanged at RM5, valuing the banking group at approximately RM97.05 billion. The proposed acquisition is expected to strengthen Public Bank’s control over its Hong Kong operations while supporting its long-term business growth and operational efficiency.
Investment & Market Trends

CapitaLand Targets US$500 Million For Third Asian Credit Fund

Singapore’s CapitaLand Investment Ltd is targeting US$500 million in commitments from investors for its third Asia-Pacific credit programme, according to people familiar with the matter. The latest fundraising effort by the Temasek Holdings Pte Ltd-controlled asset manager comes months after it secured US$320 million for its second vehicle, ACP II, which added approximately US$600 million to its funds under management. According to the people, who spoke on condition of anonymity as the matter is private, ACP III will continue the focus of its previous credit strategies on senior secured, asset-backed investments. CapitaLand Investment will primarily target existing investors for the third fund and is aiming for a first close by year-end, the people said. A spokesperson for CapitaLand Investment declined to comment. The fundraising initiative comes as private credit in Asia faces mounting scrutiny, with investors increasingly questioning whether loans backed by collateralised assets remain safe bets. The collapse of Australian property developer Bathla Group, which relied heavily on private debt, has heightened concerns that the country’s A$200 billion (US$144 billion) private credit market — where real estate accounts for as much as 60% of lending — may be beginning to show cracks. The firm’s first credit programme, ACP I, raised A$265 million, which financed two prime mixed-use developments in Melbourne and Adelaide, the company said in April. The second funding pool was allocated toward mortgage loans for logistics, office and living assets in Sydney and Seoul. The company has said its real estate credit platform has deployed more than S$10 billion (US$7.9 billion) across the Asia-Pacific region through Wingate Group Holdings, which it acquired in 2025. Wingate, one of Australia’s largest private credit managers, was among more than 40 asset managers that had lent to Bathla before its collapse, according to a report last month. CapitaLand Investment has been undergoing a series of personnel changes in recent months. In July, the firm disbanded its special opportunities team, which had been dedicated to pursuing higher-risk strategies. Separately, Jeff French joined the firm in March as chief operating officer of its alternatives business, following a stint at BNP Paribas Asset Management.

Investment & Market Trends

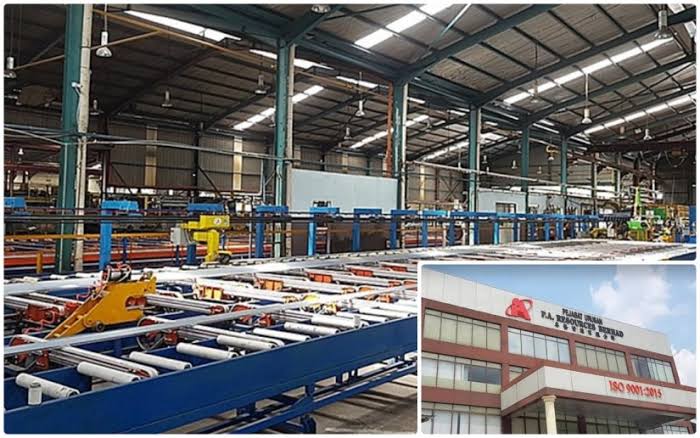
P.A. Resources Secures RM255.45mil Banking Facilities For Working Capital, New Plant

P.A. Resources Bhd (PARB), through its wholly owned subsidiaries, has accepted additional banking facilities totalling RM255.45 million to support the group’s existing operations and the development of a new plant. In a filing with Bursa Malaysia today, PARB said its wholly owned subsidiaries, P.A. Extrusion (M) Sdn Bhd (PAESB) and Professional Aluminium Smelting Sdn Bhd (PASSB), had accepted and executed separate letters of offer dated Aug 11, 2026, for the additional banking facilities. PAESB has accepted additional conventional banking facilities of RM205.45 million granted by AmBank (M) Bhd, while PASSB has secured additional Islamic banking facilities of RM50 million granted by AmBank Islamic Bhd. On the rationale behind the move, PARB said the group had, on July 14, 2026, announced the renewal of its supply agreement with First Solar for a contract value of approximately US$322.17 million (US$1 = RM4.04) for the period from July 1, 2026 to Dec 31, 2027. “This represents an increase of approximately US$90.27 million, or 38.9%, compared with the fourth renewal valued at US$231.9 million for the period from Jan 2, 2024 to July 1, 2025,” the company said, adding that the higher contract value is expected to increase the group’s production as well as its working capital requirements. Of the total banking facilities, RM50 million will be used to support anticipated increases in working capital requirements arising from higher sales value and the group’s expansion plans through product and market diversification, with utilisation expected to correspond with rising business activity and the resulting earnings potential. A further RM65.45 million will be used to finance the construction of a new plant and the acquisition of plant and machinery, while RM140.0 million will fund the new plant’s working capital requirements, including the purchase of raw materials, inventory holdings and financing on credit terms extended to customers, the company added. “The new plant is expected to increase the group’s monthly aluminium extrusion production capacity from about 3,500 tonnes to 8,500 tonnes, strengthening the group’s ability to fulfil the increase in customer orders and further its product and market diversification strategies,” it said. “Overall, the additional banking facilities will provide the group with the financial flexibility required to fulfil the renewed supply agreement, implement its capacity expansion plan and support anticipated business growth, while preserving its existing working capital resources and maintaining the group’s commitment to its dividend policy,” it added.

Investment & Market Trends

Hextar Portfolio Raises Hextar Retail Stake, Triggers Mandatory Offer

Hextar Portfolio Sdn Bhd’s conditional voluntary takeover offer for Hextar Retail Bhd has turned into a mandatory offer after the company acquired an additional 4.82% stake in the retailer. Hextar Portfolio purchased an additional 22.41 million shares on the open market, raising its overall stake in Hextar Retail to approximately 35.4%. Following this latest acquisition, Hextar Portfolio now holds a total of 164.7 million shares in Hextar Retail, according to an announcement made through RHB Investment Bank Bhd. The latest round of share purchases triggered a mandatory takeover offer for all remaining Hextar Retail shares not already owned by Hextar Portfolio, the ultimate offeror, and parties acting in concert with them, in accordance with takeover regulations governing significant shareholding thresholds. The offer notice was first served on Hextar Retail’s board on Aug 10, on behalf of Hextar Portfolio, through RHB Investment Bank. Hextar Portfolio is an investment vehicle owned by Datuk Ong Choo Meng that operates within the broader Hextar Group, a diversified conglomerate spanning multiple listed entities and a wide range of business sectors across various industries. The shift from a voluntary to a mandatory offer marks a significant development in the ongoing corporate exercise, as Hextar Portfolio’s increased stake now compels it to extend the same offer terms to all remaining shareholders of Hextar Retail, potentially paving the way for a full takeover of the company should shareholder acceptance levels prove sufficient.

Investment & Market Trends

Kerjaya Prospek Shares Rise On RM858mil Data Centre Contract Win

Kerjaya Prospek Group Bhd (KPGB) shares rose in early trade today after the group secured an RM858 million contract for mechanical, electrical and plumbing (MEP) fit-out works at a data centre in Iskandar Puteri, Johor. At 10.24am, KPGB shares had risen four sen to RM3.12, with 467,100 shares traded. In a note today, Public Investment Bank Bhd said KPGB, through its wholly owned subsidiary Kerjaya Prospek (M) Sdn Bhd, had accepted a letter of award dated Sept 1, 2026, from a data centre developer for the MEP fit-out works. The contract carries a fixed lump-sum value of RM858 million. “The project is set to begin in the third quarter of 2026 and is expected to be completed within eight months. This win brings KPGB’s year-to-date contract wins to RM3.2 billion and its total outstanding order book to RM5.9 billion, further expanding its client base,” the research house said in the note. Public Investment Bank estimated that the project would contribute approximately RM26.0 million, or 9.6% of KPGB’s forecast earnings for the financial years 2026 and 2027, reflecting the meaningful boost the contract is expected to bring to the group’s overall financial performance. The bank maintained its “Outperform” call on KPGB and raised its target price to RM3.90, up from RM3.30 previously, citing the strength of the contract win and the company’s growing order book as key drivers behind the upgraded outlook. With this latest addition, KPGB’s expanding order book underscores its continued momentum in securing high-value construction and fit-out projects, particularly within Malaysia’s fast-growing data centre segment, which has become an increasingly significant contributor to the group’s overall project pipeline.

Investment & Market Trends

Zetrix AI To Acquire 50% Stake In MYEG Ventures Philippines For RM130m

Zetrix AI Bhd is acquiring a 50% stake in Philippines-based information technology services provider MYEG Ventures Inc for RM130 million through a cash-and-share deal. In a bourse filing, the digital services provider said it had entered into a share purchase agreement with Next Lion Ltd on Sept 1 to acquire 15.25 million ordinary shares in MYEG Ventures. Next Lion’s sole shareholder and director is Yap Shon Leong. MYEG Ventures is principally involved in providing information technology services and holds a 60% stake in MYEG Philippines Inc. Upon completion of the acquisition, MYEG Philippines will become a subsidiary of Zetrix AI. Zetrix AI said the acquisition is aimed at strengthening the group’s expansion strategy in the Philippines by establishing and enhancing its presence in the market. It is also expected to broaden the group’s business operations and customer base, complement its existing business strategies, and support its long-term growth plans in the country. Zetrix AI plans to fund the acquisition through a combination of cash and the issuance of up to 360.57 million new ordinary shares in the group. Barring any unforeseen circumstances, the acquisition is expected to be completed within three months of all conditions precedent being met, on a date to be mutually agreed between Zetrix AI and Next Lion. Trading in Zetrix AI was halted for one hour and is scheduled to resume at 10am on Wednesday. The counter last traded at 26.5 sen, its lowest level in 12 years, after coming under heavy selling pressure since last week.

Investment & Market Trends

RedPlanet Signs Underwriting Deal For ACE Market Listing Transfer

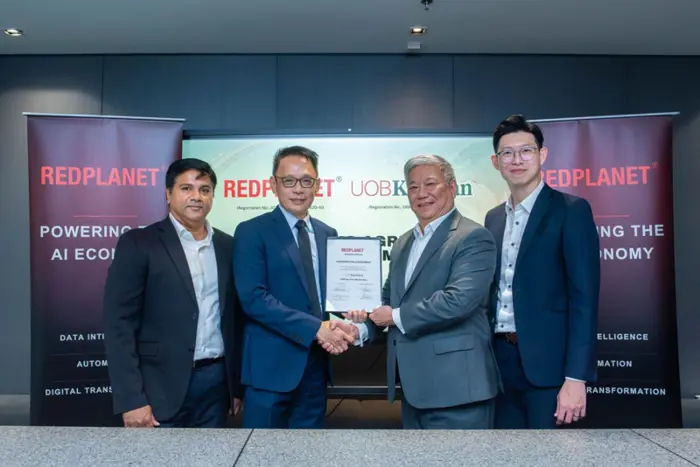
RedPlanet Bhd has signed an underwriting agreement with UOB Kay Hian (M) Sdn Bhd (UOBKH) for its proposed initial public offering (IPO) and transfer of listing from the LEAP Market to the ACE Market of Bursa Malaysia Securities Bhd. RedPlanet is an enterprise information and communication technology (ICT) solutions provider specialising in geospatial and intelligent rail solutions. According to its prospectus, the IPO comprises a public issue of 70.0 million new shares, along with an offer for sale of 10 million existing shares by way of private placement to selected investors. From left: Panjetty Kumaradevan Senthil Kumar, Non-Independent Executive Director and CEO, GIS Group of RedPlanet; Lian Wah Seng, Non-Independent Executive Director and Managing Director; David Lim, CEO of UOB Kay Hian; and Winston Loh, Director of Corporate Finance. Of the new shares on offer, 20.54 million will be allocated to the Malaysian public, while 19.71 million will be reserved for eligible directors, employees and other individuals who have contributed to the success of RedPlanet and its subsidiaries. The company added that 11.52 million shares will be offered by way of private placement to selected investors, while 18.22 million shares will be offered to Bumiputera investors approved by the Ministry of Investment, Trade and Industry (MITI). “Pursuant to the underwriting agreement, UOBKH will underwrite 40.25 million issue shares of the company, comprising the shares made available for application by the Malaysian public and eligible persons,” the company said in a statement. Executive director and managing director Lian Wah Seng said the proposed IPO and transfer of listing are expected to enhance the company’s corporate profile, broaden investor participation and provide it with a stronger platform to pursue higher-value ICT projects, supporting its long-term growth strategy. Moving forward, RedPlanet intends to undertake more complex, higher-value ICT projects and expand its intelligent rail solutions offering to include central transmission system solutions. UOBKH is acting as the principal adviser, sponsor, underwriter and placement agent for RedPlanet.

Investment & Market Trends

VSTECS To Sell Stake In Isatec For RM49mil

Vstecs Bhd is proposing to dispose of its entire 40% stake in Isatec Sdn Bhd for RM48.75 million in cash, as the group seeks to monetise the investment and redeploy capital into its core businesses. The information and communications technology distributor said the proposed disposal, to Skyform Pte Ltd, a digital and artificial intelligence transformation services provider, is expected to be completed by the first quarter of 2027, subject to conditions outlined under the share purchase agreement. VSTECS Bhd CEO JH Soong. Upon completion of the transaction, Skyform will hold a 75% stake in Isatec, following its acquisition of Vstecs’ 40% interest, alongside an additional 35% stake to be acquired from Isatec’s management shareholders. Vstecs chief executive officer JH Soong said the proposed disposal would allow the group to crystallise the value it has built in Isatec over the past seven years, marking a significant milestone in the company’s investment journey. “Together with the dividends received from Isatec, we would have realised total cash returns of RM64.97 million, which is equivalent to approximately 3.46 times the original investment cost,” he said, underscoring the strong returns generated from the investment over its holding period. The proposed disposal reflects Vstecs’ broader strategy of actively managing its investment portfolio, allowing the group to unlock value from mature investments and channel the proceeds towards strengthening its core distribution and technology-related businesses going forward.

Investment & Market Trends

Oriental Kopi Expands Into Indonesia, Mauritius In Overseas Push

Oriental Kopi Holdings Bhd, whose share price has slid nearly 30% year-to-date, has announced its overseas expansion plans into Indonesia and Mauritius. The ACE Market-listed food and beverage chain operator said in a bourse filing that it will enter Indonesia through a joint venture with PT Era Boga Nusantara to develop and operate Oriental Kopi restaurants in the country. Its indirect wholly owned subsidiary, Oriental Coffee International Sdn Bhd, will invest US$480,000 (RM1.96 million) for a 40% stake, while its Indonesian partner will hold the remaining 60%. The joint venture company, PT Era Oriental Kopi, will focus on opening restaurants across Indonesia, prioritising Jakarta while excluding Medan and airport locations. The first outlet is scheduled to commence operations within a year of the agreement being signed. Oriental Kopi said the partnership will allow it to tap its Indonesian partner’s local market knowledge and business network. The investment will be funded through internal funds and/or bank borrowings. Separately, in Mauritius, the company said in another bourse filing that it has granted Coffee Time Ltd exclusive franchise rights to develop and operate Oriental Kopi restaurants on the island, marking its entry into the market through an asset-light expansion model. Under the six-year franchise agreement, Coffee Time will pay franchise fees and monthly royalties to Oriental Kopi for each restaurant it operates, with the first outlet required to commence business within 300 days of the agreement. Both transactions are not expected to have a material impact on Oriental Kopi’s earnings, net assets or gearing for the financial year ending Sept 30, 2026, although the company expects them to contribute positively to future earnings. Oriental Kopi’s share price has been on a downward trend since early January, roughly a year after its debut on Bursa Malaysia at an initial public offering price of 88 sen. The stock has fallen from its year-high of RM1.49 on Jan 19 to a low of 88 sen in mid-July. It closed at 99.5 sen on Thursday, valuing the group at RM1.99 billion — with approximately RM800 million in market capitalisation erased since the start of 2026.

Investment & Market Trends

Keyfield Buys Mega Dredger For US$25m, Enters Dredging Business

Keyfield International Bhd is venturing into the dredging industry through the acquisition of a mega trailing suction hopper dredger (TSHD) at a price 61% below its independently assessed fair-market value. The offshore support vessel operator entered into a deal on Wednesday with Inai Rimba Sdn Bhd, which has receivers and managers appointed, to acquire the 10-year-old Inai Kenanga on an “as-is, where-is” basis for US$24.67 million (RM99.7 million), according to the group’s filing with Bursa Malaysia. Keyfield will nominate a special-purpose vehicle (SPV) to ultimately own the vessel. The SPV will eventually be held 60% by Keyfield and 40% by Singapore-based Star Naval 1 Pte Ltd (SNPL), which has an option to increase its stake to 45%. SNPL is co-owned by Starhigh Asia Pacific Pte Ltd and Naval Elite Ltd. Starhigh, founded in 2006, is involved in dredging, land reclamation, coastal protection and shoreline management across Southeast Asia. “This acquisition marks our foray into the dredging industry and accelerates our expansion beyond the oil-and-gas sector,” said Keyfield group CEO and executive director Datuk Darren Kee Chit Huei in a statement. “It is our second acquisition of a non-O&G vessel, following last year’s acquisition of Keyfield Blessing, our cable-laying barge that is currently on-hire in the Middle East.” The group added that the move forms part of Keyfield’s longer-term plan to raise contributions from non-O&G activities to as much as 20% of total group earnings. Following the acquisition, its operations will span offshore support vessel chartering, cable laying, marine infrastructure, coastal development and dredging. An independent valuation by Armal Marine and Offshore Sdn Bhd, dated April 25, placed Inai Kenanga’s fair-market value at US$63.7 million. Completed in 2016, Inai Kenanga was, at the time, the largest dredger in Asia and the third-largest in the world. The Malaysian-flagged vessel measures 197.7m in length, with a deadweight tonnage of 41,244 tonnes and a hopper capacity of 32,205 cu m. It was built by Selat Melaka Shipbuilding Corp Sdn Bhd with engineering support from Vuyk Engineering Rotterdam. Keyfield said constructing a new vessel with similar specifications would cost upwards of US$150 million, while Inai Kenanga itself was reportedly built at a cost of about RM1.2 billion. “With the former owner of Inai Kenanga having entered receivership, we were presented with a unique opportunity to acquire this asset at below market value,” Kee said. “Leveraging the strength of our balance sheet, this acquisition will be funded through our internal cash, hence not requiring any borrowings.” Keyfield will fund US$23.8 million of the purchase consideration, while SNPL will contribute US$900,000. Both parties will also make initial investments of US$400,000 and US$100,000, respectively. SNPL, meanwhile, will bear the estimated US$15 million cost of reactivating the vessel. Should the actual reactivation and pre-operating costs exceed that amount, SNPL has agreed to continue funding the excess through shareholder loans to the SPV. Keyfield will fund its portion entirely through internally generated funds, including part of the proceeds from its recent disposal of Keyfield Compassion, without taking on any additional borrowings. Following the vessel’s planned reactivation, Keyfield and Starhigh intend to pursue dredging projects across Southeast Asia, particularly in Malaysia and Singapore, Kee said. “Starhigh brings relevant industry network and expertise that complements our marine asset ownership and operational capabilities,” he added. The group expects the acquisition to begin contributing positively to earnings from FY2027, subject to the successful reactivation and commercial deployment of the dredger. Shares of Keyfield closed two sen, or 1.5%, lower at RM1.35 on Wednesday, valuing the group at RM1.09 billion. The stock has fallen more than 11% year-to-date.

Scroll to Top

Subscribe
FREE Newsletter