Investment & Market Trends

Investment & Market Trends

Keyfield Buys Mega Dredger For US$25m, Enters Dredging Business

Keyfield International Bhd is venturing into the dredging industry through the acquisition of a mega trailing suction hopper dredger (TSHD) at a price 61% below its independently assessed fair-market value. The offshore support vessel operator entered into a deal on Wednesday with Inai Rimba Sdn Bhd, which has receivers and managers appointed, to acquire the 10-year-old Inai Kenanga on an “as-is, where-is” basis for US$24.67 million (RM99.7 million), according to the group’s filing with Bursa Malaysia. Keyfield will nominate a special-purpose vehicle (SPV) to ultimately own the vessel. The SPV will eventually be held 60% by Keyfield and 40% by Singapore-based Star Naval 1 Pte Ltd (SNPL), which has an option to increase its stake to 45%. SNPL is co-owned by Starhigh Asia Pacific Pte Ltd and Naval Elite Ltd. Starhigh, founded in 2006, is involved in dredging, land reclamation, coastal protection and shoreline management across Southeast Asia. “This acquisition marks our foray into the dredging industry and accelerates our expansion beyond the oil-and-gas sector,” said Keyfield group CEO and executive director Datuk Darren Kee Chit Huei in a statement. “It is our second acquisition of a non-O&G vessel, following last year’s acquisition of Keyfield Blessing, our cable-laying barge that is currently on-hire in the Middle East.” The group added that the move forms part of Keyfield’s longer-term plan to raise contributions from non-O&G activities to as much as 20% of total group earnings. Following the acquisition, its operations will span offshore support vessel chartering, cable laying, marine infrastructure, coastal development and dredging. An independent valuation by Armal Marine and Offshore Sdn Bhd, dated April 25, placed Inai Kenanga’s fair-market value at US$63.7 million. Completed in 2016, Inai Kenanga was, at the time, the largest dredger in Asia and the third-largest in the world. The Malaysian-flagged vessel measures 197.7m in length, with a deadweight tonnage of 41,244 tonnes and a hopper capacity of 32,205 cu m. It was built by Selat Melaka Shipbuilding Corp Sdn Bhd with engineering support from Vuyk Engineering Rotterdam. Keyfield said constructing a new vessel with similar specifications would cost upwards of US$150 million, while Inai Kenanga itself was reportedly built at a cost of about RM1.2 billion. “With the former owner of Inai Kenanga having entered receivership, we were presented with a unique opportunity to acquire this asset at below market value,” Kee said. “Leveraging the strength of our balance sheet, this acquisition will be funded through our internal cash, hence not requiring any borrowings.” Keyfield will fund US$23.8 million of the purchase consideration, while SNPL will contribute US$900,000. Both parties will also make initial investments of US$400,000 and US$100,000, respectively. SNPL, meanwhile, will bear the estimated US$15 million cost of reactivating the vessel. Should the actual reactivation and pre-operating costs exceed that amount, SNPL has agreed to continue funding the excess through shareholder loans to the SPV. Keyfield will fund its portion entirely through internally generated funds, including part of the proceeds from its recent disposal of Keyfield Compassion, without taking on any additional borrowings. Following the vessel’s planned reactivation, Keyfield and Starhigh intend to pursue dredging projects across Southeast Asia, particularly in Malaysia and Singapore, Kee said. “Starhigh brings relevant industry network and expertise that complements our marine asset ownership and operational capabilities,” he added. The group expects the acquisition to begin contributing positively to earnings from FY2027, subject to the successful reactivation and commercial deployment of the dredger. Shares of Keyfield closed two sen, or 1.5%, lower at RM1.35 on Wednesday, valuing the group at RM1.09 billion. The stock has fallen more than 11% year-to-date.
Investment & Market Trends

Li Ka-shing Sticks To US$23 Billion Ports Asking Price Despite Panama Loss

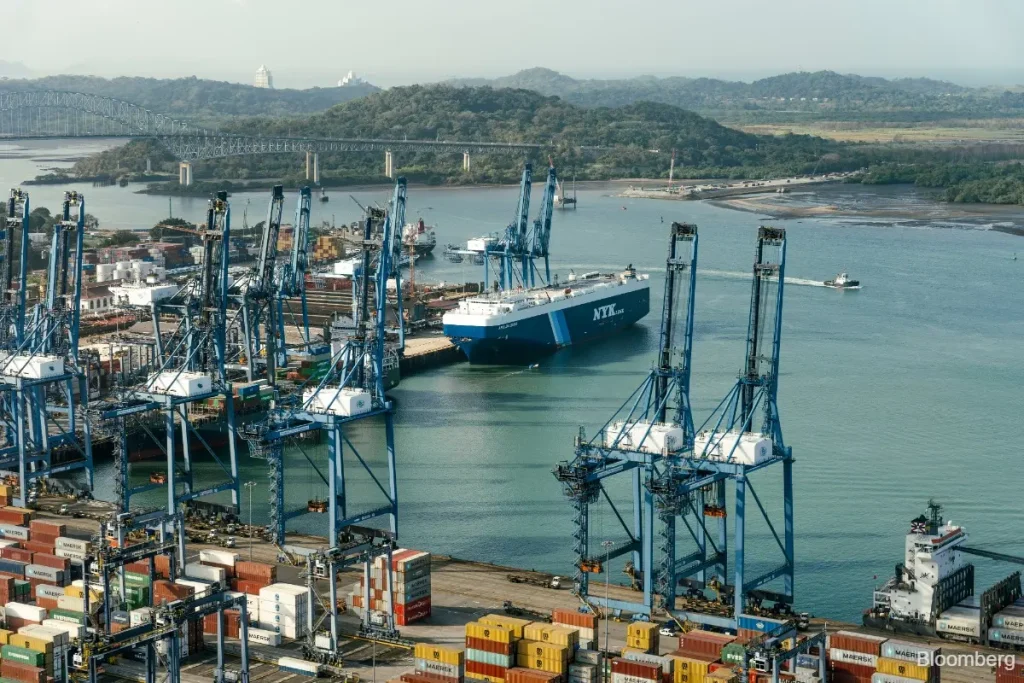
Li Ka-shing’s CK Hutchison Holdings Ltd expects to sell what remains of its global ports portfolio for its original US$22.8 billion (RM91.82 billion) valuation, even after losing two Panama terminals that had originally been included, according to people familiar with the matter. The proposed sale of 43 global ports, to a buyer consortium that includes US investment firm BlackRock Inc, was expected to net CK Hutchison more than US$19 billion in cash when it was first announced in March 2025. That expectation has not changed, even with the Panama Canal facilities excluded from the package, the people said, speaking on condition of anonymity as the deliberations are private. The talks are ongoing, and final details, including pricing, could still shift given the complexity of the deal, they added. Panama invalidated CK Hutchison’s contract to operate the ports earlier this year following pressure from US President Donald Trump. The Hong Kong conglomerate and its unit, Panama Ports Co, have since launched separate international arbitration claims challenging the decision, seeking damages of at least US$3.5 billion. Any compensation arising from those cases is expected to be shared between CK Hutchison and the buyers, one of the people said. The Panama facilities had accounted for only about 4% of the portfolio’s original price. According to one of the people, the price of the remaining 41 ports is believed to have risen enough to offset their loss, as buyers increasingly view them as logistical assets generating stable income amid rising geopolitical tension. Company representatives, bankers and lawyers continue to meet weekly to negotiate deal terms, the people familiar with the matter said. The sale has become a flashpoint in the broader US-China rivalry, with tensions running especially high over the Panama terminals, as Washington vows to protect its interests in Latin America while Beijing expands its influence in the region. Hopes for a political breakthrough have been renewed following news that Chinese leader Xi Jinping plans to meet Trump during his September trip to the US, though the parties remain cautious given that a similar high-level meeting in May between the two failed to yield results, according to the people. A spokesperson for BlackRock declined to comment. CK Hutchison and members of the buyer consortium — including China Cosco Shipping Corp, China Merchants Bank Co and Italian billionaire Gianluigi Aponte’s MSC Mediterranean Shipping Co — did not respond to requests for comment. Mired Down The deal hit roadblocks soon after it was announced, with CK Hutchison drawing Beijing’s ire over its agreement to sell ports in strategically significant global locations to a consortium backed by BlackRock. To secure China’s approval, the group invited state-owned companies, including Cosco, to join the buyer consortium. Discussions have remained bogged down as the parties navigate regulatory hurdles across the various countries where the ports are located, while also attempting to reconcile competing demands from prospective buyers. Talks have centred on a proposal to split the ports into different ownership structures, according to reports. That arrangement could give Chinese buyers larger stakes and greater control in certain locations, while other consortium members take the lead elsewhere. Panama’s forced takeover of the two terminals added further uncertainty to the deal, with Beijing warning that the country could pay a “heavy price” for the move. Parties involved in the sale are likely to seek positive signals from both China and the US before finalising the transaction’s terms, according to reports. There are signs, however, that tensions between Beijing and Panama may be easing. The two sides are reportedly moving toward renewing an agreement that gives Panama-flagged vessels favourable treatment at Chinese ports, according to local media reports in August, citing China’s ambassador to the country.

Investment & Market Trends

SBC Weighs Consolidating Singapore Operations Under Single Entity

HSBC Holdings plc is considering merging its wholesale, retail and private banking businesses in Singapore into one unified entity as part of a broader effort to simplify its structure, according to sources close to the matter who spoke on condition of anonymity. This potential restructuring is part of a larger transformation effort led by CEO Georges Elhedery, who has been streamlining the bank’s operations, closing or divesting several units, and cutting costs since taking the helm in September 2024. Earlier this year, HSBC sold its Singapore insurance arm for US$2.1 billion (RM8.46 billion). Responding to the reports, an HSBC spokesperson said the bank regularly evaluates its organizational setup for ways to simplify, while stressing that all Asia-Pacific entities remain under the oversight of The Hongkong and Shanghai Banking Corporation, with no changes planned to that arrangement. Currently, HSBC’s Singapore retail and wealth management business operates as a separately incorporated entity, HSBC Bank (Singapore) Ltd, established in 2016, alongside a separate branch under its main Asia arm, The Hongkong and Shanghai Banking Corp. Despite the potential restructuring, HSBC continues to expand its presence in Singapore, including plans for a new global AI hub and the hiring of over 100 AI specialists. The possible shake-up comes as HSBC faces scrutiny over its heavy reliance on Hong Kong, where it holds the largest exposure among global banks amid rising geopolitical tension. The bank recently expanded further in the territory through its US$14 billion buyout of Hang Seng Bank Ltd, reinforcing Hong Kong’s role as its top profit source and one of the city’s three banknote-issuing institutions. By comparison, HSBC’s Singapore business remains far smaller. In the first half of 2026, Singapore contributed US$774 million in pretax profit, against Hong Kong’s US$7.8 billion. Hong Kong also employs over 30,000 HSBC staff with US$144 billion in wholesale loans, compared to roughly 3,600 employees and US$21.8 billion in wholesale lending in Singapore. Such restructuring wouldn’t be unprecedented — in 2019, Standard Chartered plc took a similar step, consolidating into a locally incorporated subsidiary and establishing twin hubs in Singapore and Hong Kong to cut costs and simplify operations.

Investment & Market Trends

Yinson Targets Global FPSO Leadership Amid Energy Transition

Petroliam Nasional Bhd (Petronas), the Employees Provident Fund (EPF) and the founding Lim family of Yinson Holdings Bhd (KL:YINSON) are reportedly in talks to take the oil-and-gas company private, according to sources. The three parties are said to be forming a consortium to buy out Yinson, which owns one of the world’s largest fleets of floating production storage and offloading (FPSO) vessels, according to people familiar with the matter. A deal could be announced soon. Petronas and the Lim family did not respond to requests for comment from The Edge, while the EPF declined to comment. Yinson currently operates nine floating assets, with two more on order across Southeast Asia, South America and Africa. The company’s executive chairman, Lim Han Weng, and his family hold a 27.68% stake in the firm, while the EPF owns 17.09%. Another substantial shareholder is Retirement Fund Inc, the pension fund for civil servants better known as KWAP, which holds 6.84% of Yinson. Petronas also runs its own FPSO business through MISC Bhd (KL:MISC). The 51%-owned unit operates six FPSOs, five floating storage and offloading vessels, and one floating production and storage facility across Malaysia, Thailand, Vietnam and Brazil. In 2024, MISC held talks with Bumi Armada Bhd (KL:ARMADA), which operates seven assets, to merge their respective FPSO businesses. The proposal was mutually called off in August 2025 after both parties concluded it would not fully achieve their intended objectives. Yinson has previously featured in reports over potential privatisation. In June 2025, the company said its major shareholders were in exploratory discussions with “various parties with reference to potential corporate proposals regarding their shareholdings.” At the time, reports indicated that the Lim family was in talks with New York-based investment firm Stonepeak Partners to take the company private. Those plans, however, were withdrawn earlier this year. Beyond its FPSO operations, Yinson also owns renewable energy assets with a combined 557-megawatt capacity currently in operation, along with another 148 megawatts under construction across India, Peru and New Zealand. The company additionally operates electric vehicle charging stations in Malaysia and Singapore. Yinson, which posted a net profit of RM683 million and revenue of RM5.4 billion for the financial year ended Jan 31, 2026 (FY2026), first entered the FPSO business in 2011 in Vietnam, where it builds and leases out floating vessels used in offshore oil and gas production. The company became a major FPSO player in mid-2013 after acquiring Norwegian FPSO firm Fred Olsen Production ASA for RM551.3 million, and now holds stakes in offshore assets across Brazil, Ghana, Nigeria, Angola, Malaysia and Vietnam. The EPF, which manages the retirement savings of Malaysia’s private sector employees, emerged as a major shareholder of Yinson in 2015 — the same year the company secured its first major contract with Italian oil major Eni for the supply of an FPSO vessel in Ghana, worth US$2.54 billion. Shares of Yinson closed at RM2.22 on Thursday, giving the company a market capitalisation of RM7.14 billion.

Investment & Market Trends

Apparel Retailer EMPG Gets Bursa Nod For ACE Market Listing

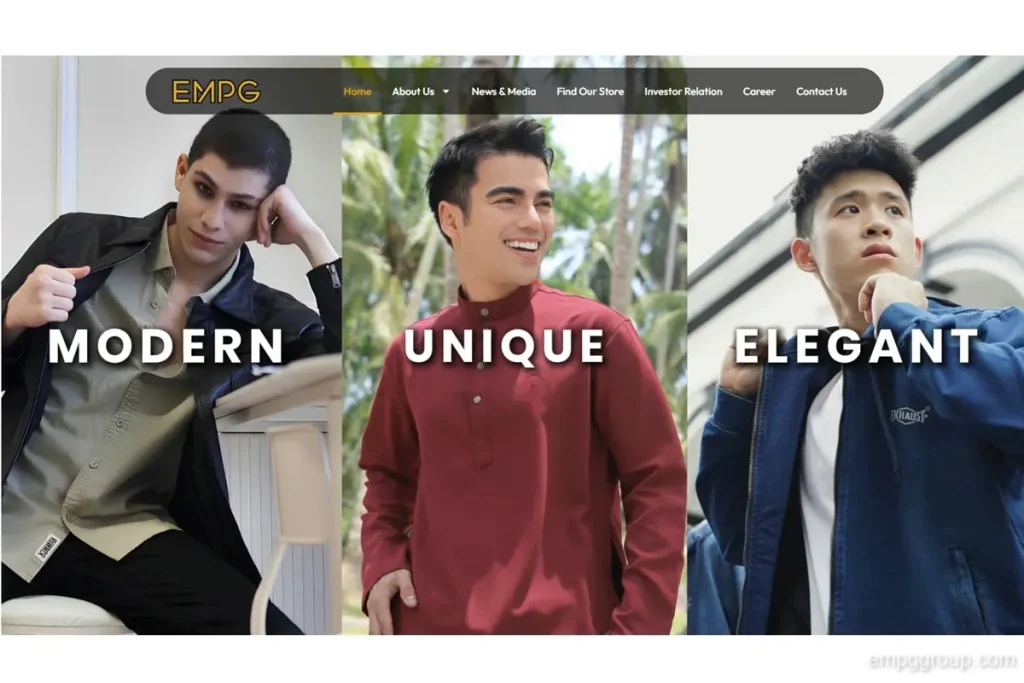
Apparel retailer EMPG Group Bhd has received approval-in-principle from Bursa Malaysia for its proposed listing on the ACE Market. The approval marks another step forward for the company’s initial public offering (IPO), EMPG managing director Loh Tau Sing said in a statement. No timeline for the IPO was disclosed, though the company will need to complete its listing within six months of approval. “The IPO will support the next phase of our growth as we accelerate the expansion of our retail network, further strengthen our multi-brands positioning, enhance our operational and logistics infrastructure and continue to broaden our product offerings,” Loh said. Based in Kedah, EMPG is primarily involved in the retail and wholesale of apparel for men, women and children. Its portfolio includes in-house brands such as Exhaust, Idexer, Silverland, Brittania and Ventine, alongside licensed brands Hummer and Pierre Cardin. EMPG’s retail network comprises consignment counters across Malaysia, stand-alone outlets in the Klang Valley, and e-commerce platforms. Proceeds from the IPO have been earmarked for the expansion of its retail network, with plans to open 100 new consignment counters and 15 boutiques within 24 months of its listing. The remainder of the proceeds will be used for working capital and to cover listing expenses. Loh and Datuk Lee Leong Hock, a co-founder and the company’s deputy chairman, are cashing out part of their stakes in EMPG through an offer for sale under the IPO. Berjaya Securities is acting as the principal adviser, sponsor, underwriter and placement agent for the IPO, while Wyncorp Advisory is serving as the corporate finance adviser.

Investment & Market Trends

Sunway Construction Wins RM1.04b Contracts From US Tech Firm

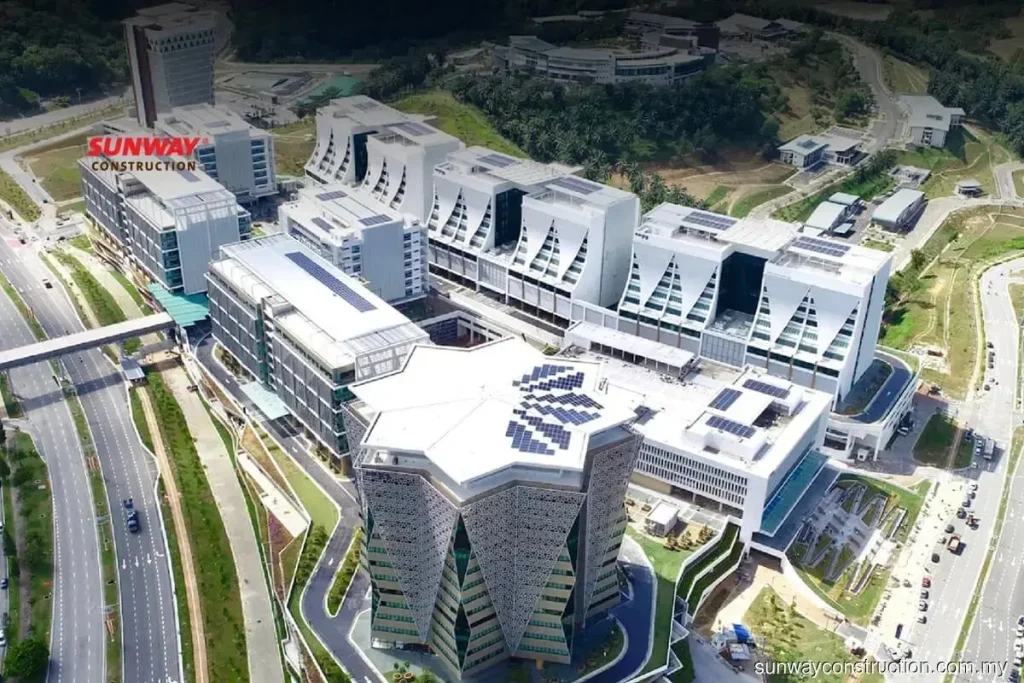
Sunway Construction Group Bhd has secured RM1.04 billion worth of orders to provide mechanical, electrical and plumbing fit-out works for two projects awarded by a multinational technology company based in the United States. The works are scheduled to commence immediately and be completed by March 2028, Sunway Construction said in a bourse filing, adding that the letter of award received on Friday also serves as the notice to commence works. The identity of the client was not disclosed, nor was the exact location of the projects, leaving some details of the contracts undisclosed for now. The latest award raises Sunway Construction’s new order wins for the financial year ending March 31, 2027 (FY2027) to RM6.85 billion, reflecting continued strong demand for the company’s construction and engineering services. The builder reported a 56.4% year-on-year jump in its first-quarter net profit, despite lower revenue, as it executed higher-margin, specialised projects, combined with a rebound in its precast concrete segment. Net profit for the quarter ended March 31, 2026 (1QFY2026) rose to RM118.41 million, up from RM75.72 million in 1QFY2025, underscoring the company’s ability to improve profitability even amid softer top-line performance. Shares of Sunway Construction closed 25 sen, or 3.07%, lower at RM7.90 on Friday. Despite the day’s decline, the stock remains up 38.84% for the year, giving the company a market capitalisation of RM10.5 billion.

Investment & Market Trends

Johor Attracts Over RM5 Billion In Investments From Singapore Visit

Johor has successfully attracted potential investments worth more than RM5 billion following a series of meetings with investors during a three-day working visit to Singapore that concluded today. Menteri Besar Datuk Onn Hafiz Ghazi said the achievement reinforces confidence in Johor as an investment destination and emerging growth hub in the region. He said the potential investments span several strategic and high-tech sectors, including high-speed optical technology, healthcare and semiconductor manufacturing equipment, bringing not only capital but also technology, expertise and new employment opportunities to the state. “Among the factors attracting investor interest is the availability of talent and a highly skilled workforce. Therefore, it is not just infrastructure and facilities that matter, but also the confidence that we have a workforce capable of meeting the needs of their respective industries,” he said in a Facebook post today. Onn Hafiz said talent development through the Johor Talent Development Council (JTDC) therefore remains a top priority. “We want training and skills development to be aligned with actual industry needs so that when investments arrive, the people of Johor are ready to fill the jobs created. At the same time, the Invest Malaysia Facilitation Centre Johor (IMFC-J) will continue to facilitate and expedite investment-related processes,” he said. He expressed hope that the potential investments would materialise, creating more quality jobs and broader economic opportunities for Johor residents. “Insya-Allah, we will continue to ensure that every investment coming into Johor brings benefits to the state and Bangsa Johor,” he said.

Investment & Market Trends

Fast Fashion Giant Shein Valued At Up To $27 Billion In Hong Kong IPO

Online fast-fashion retailer Shein’s valuation has fallen by around 70% from a near $100 billion private market peak four years ago, as it seeks to raise up to HK$13.86 billion ($1.77 billion) in its Hong Kong IPO, which launched on Monday. According to filings, Shein is selling 280 million shares priced between HK$47.60 and HK$49.50 apiece, valuing the company at close to $27 billion at the top of that range. The valuation marks a sharp decline from earlier private fundraising rounds, which valued Shein at $98.2 billion in 2022 and $64 billion in both 2023 and April 2024. The company is expected to announce its final IPO price on Aug 31, with trading set to begin on Sept 1. Known for selling $5 dresses and $10 jeans to shoppers across roughly 160 countries, Shein had initially sought an IPO valuation of between $30 billion and $40 billion when investor meetings ahead of the listing first began. The marked decline in valuation follows growing investor concerns over slowing growth, rising costs and shifting market conditions, with some investors expressing doubt that Shein could return to the growth rates that once valued it at nearly $100 billion four years ago. Cornerstone investors led by existing shareholders Boyu, Tiger Global and General Atlantic have subscribed for around $383 million worth of Shein shares, according to the prospectus. Tencent, Greenwoods, Taikang Life and UBS Asset Management are also participating as stock investors. Shein said approximately 80% of the funds raised through the IPO will be used to enhance its technology capabilities and strengthen its brand presence globally. The company has also agreed to pay up to roughly $3.5 billion in cash to certain investors who purchased special shares in earlier private funding rounds, the prospectus showed. Shares sold in the Hong Kong IPO will carry one-tenth the voting rights of shares held by the company’s founders. Co-founders Sky Yangtian Xu, Maggie Gu, Molly Miao and Tony Ren will collectively control 90% of Shein’s voting rights following the listing. Growth Slows Sharply The long-awaited listing comes at a time when slowing revenue growth and weaker core earnings are weighing on Shein’s business, with shrinking margins also raising concerns that its expansion is facing headwinds from rising trade costs, tighter regulatory scrutiny and intensifying competition across global e-commerce. Shein said in its prospectus that first-half 2026 revenue growth is expected to be broadly in line with the 1.1% growth recorded in the first quarter, while its operating margin is expected to come in slightly lower than the first-quarter level. The company attributed this to new European import charges, pricing pressure and weaker demand in the Middle East linked to the Iran war. Shein swung to a $99 million quarterly loss after the United States removed an import duty exemption on small packages, compounded by a $328 million fair-value charge on convertible redeemable preferred shares following an accounting change. Shein’s IPO stands as the largest new share sale in Hong Kong in 2026, surpassing autonomous driving firm Momenta Global’s $751 million offering in July. It ranks as the third-largest IPO in Asia this year, trailing CXMT and China Resources New Energy, which raised $9.8 billion and $3.6 billion respectively through Chinese onshore listings. Hong Kong IPOs have raised approximately $41 billion so far this year, a record for the period and more than double the $17 billion raised over the same period a year earlier, according to LSEG data.

Investment & Market Trends

Dnex Proposes Sale Of FPSO Excalibur To MISC

Dagang Nexchange Bhd (Dnex) has proposed to dispose of its floating production storage and offloading (FPSO) vessel, Excalibur, to MISC Bhd for US$35 million (RM142.2 million) in cash. In a filing with Bursa Malaysia, Dnex said its 90%-owned Ping Petroleum Ltd’s wholly-owned subsidiary, Ping Petroleum UK PLC, had entered into a memorandum of agreement with MISC for the proposed disposal. The proposed disposal is expected to generate a pro forma gain of US$5.86mil, or RM23.81mil. The proposed disposal is expected to generate a pro forma gain of US$5.86 million, or RM23.81 million, after taking into account capital gains tax and the recovery of capital allowances previously claimed on the vessel. Dnex said Excalibur currently carries a net book value of US$13.25 million, or RM53.83 million, on the company’s books. An independent valuation conducted by ABS Consulting placed the vessel’s fair value at between US$22.5 million and US$43.5 million, suggesting that the proposed disposal price falls within a reasonable range relative to its assessed worth. The FPSO, built in 2007 and designed with a capacity of 300,000 barrels, is currently laid up at the Port of Nigg in Scotland, having ceased active operations for some time. The proposed sale marks a strategic move for Dnex as it continues to streamline its portfolio of assets within its oil and gas operations, with the transaction expected to provide the group with additional cash proceeds while realising a gain from the disposal of a non-operational vessel.

Investment & Market Trends

NexG Clarifies RM7.5bil Indicative Price For Possible DTSB Acquisition By Govt

NexG Bhd today clarified that the request for an indicative price for the possible acquisition of its wholly owned subsidiary, Datasonic Technologies Sdn Bhd (DTSB), by the government was made by the Ministry of Finance (MOF) last month. “The request was conveyed to DTSB verbally at a meeting with MOF held on July 24, 2026, and was not made by way of a written document,” the security-related integrated technology solutions provider said in a reply to a query from Bursa Malaysia today. DTSB is the provider of the MyKad national identity card. Yesterday, NexG said DTSB had been valued at RM7.5 billion, citing its ownership of valuable intellectual property, along with identity technology spanning International Civil Aviation Organisation (ICAO)-compliant e-passports and biometric systems that use multimodal biometrics and facial recognition. NexG said MOF had requested DTSB, at the meeting, to provide an assessment of three potential scenarios: the compensation that might be payable in the event of a termination of the MyKad supply contract between the Ministry of Home Affairs and DTSB; the indicative price for a possible acquisition of DTSB; and the indicative price for a possible acquisition of a controlling block of shares in NexG, the holding company of DTSB. “Following an internal assessment conducted by the management of the company using the discounted cash flow method, which took into consideration various factors — this includes, amongst others, DTSB’s future earnings-generating capabilities, projected future cash flows, business sustainability and other relevant factors affecting the business and operations of DTSB — the management has assessed the indicative value of DTSB at approximately RM7.5 billion,” the group said. NexG said the board also recognises that DTSB currently represents the core business of the group and is the major contributor to its revenue and earnings. Accordingly, it said any disposal of DTSB, should it materialise, might have a material impact on the group’s business operations and financial performance, and could also affect the group’s level of operations as well as its continued listing status on the Main Market of Bursa Malaysia Securities Bhd.

Scroll to Top

Subscribe
FREE Newsletter