Author name: theexchangeasia admin

Investment & Market Trends

Grab To Buy 60% Stake In Atome For US$1.49 Billion, Plans Full Takeover

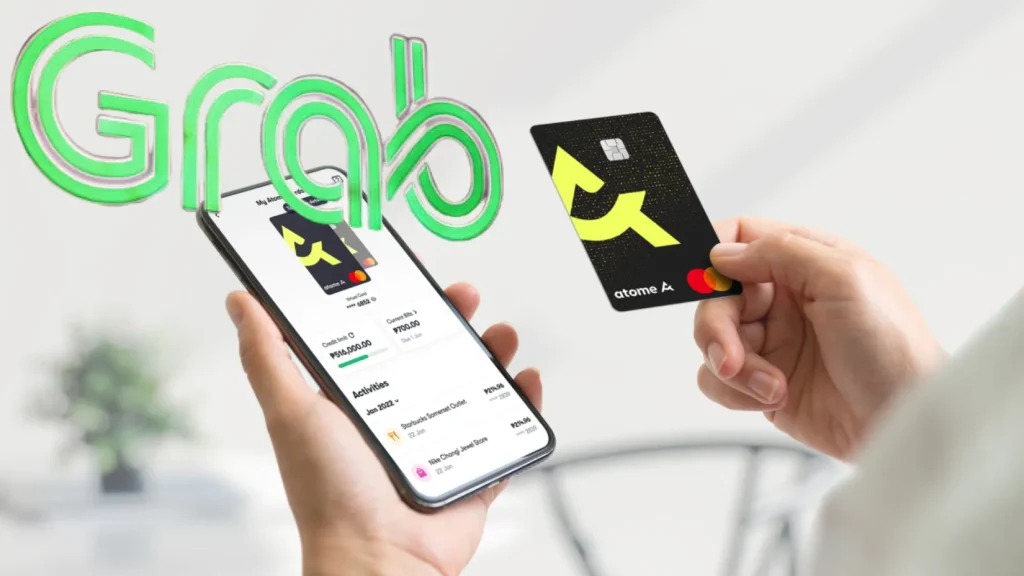
Southeast Asian technology company Grab has announced plans to acquire Atome Financial in a two-stage transaction, beginning with the purchase of a 60% stake for US$1.49 billion in cash. The acquisition is part of Grab’s strategy to expand its financial services business, particularly in consumer lending and digital financing across Southeast Asia. Under the agreement, Grab will initially acquire a controlling 60% interest in Atome Financial from Advance Intelligence Group and other shareholders. The company will then purchase the remaining 40% approximately two years after the first transaction is completed, giving Grab full ownership of Atome Financial. The proposed acquisition remains subject to regulatory approvals and other customary closing conditions. The first stage of the transaction is expected to be completed by the third quarter of 2027. The initial US$1.49 billion investment includes US$260 million in growth capital to support Atome Financial’s future expansion. The purchase price for the remaining 40% stake will depend on Atome Financial’s business performance between the two transactions. Under the agreed pricing formula, Atome Financial’s equity valuation for the second stage will range between US$2 billion and US$4.5 billion. At least half of the payment for the remaining stake will be made in cash. Atome Financial currently operates in five Southeast Asian markets, namely Singapore, Malaysia, the Philippines, Indonesia and Thailand. The company provides a range of digital financial services, including buy now, pay later (BNPL) solutions, consumer cash loans, BNPL cards and other digital lending products. Since its establishment, Atome Financial has recorded approximately 25 million cumulative transacted users and established partnerships with more than 30,000 brands. It also manages a gross loan portfolio of approximately US$1 billion, reflecting the growing demand for flexible financing solutions across the region. The acquisition is expected to strengthen Grab’s consumer lending capabilities while expanding its access to Atome Financial’s merchant network and customer base. Grab President and Chief Operating Officer Alex Hungate said Atome Financial’s use of artificial intelligence (AI) in digital lending would support the growth of Grab’s financial services ecosystem. “Atome Financial’s leading use of AI to underwrite digital lending to millions of users across the region, while managing risk effectively, will help to scale and strengthen Grab’s whole ecosystem,” he said. He added that the acquisition would help Grab improve the profitability of its financial services business and create more opportunities to serve Atome Financial’s merchant partners. Meanwhile, Advance Intelligence Group Chairman and Chief Executive Officer Jefferson Chen, who also serves as CEO of Atome Financial, said the partnership would help extend digital financing services to more underserved consumers. “Powered by AI and data, every transaction makes our underwriting smarter and our products more personalised,” he said. Chen added that combining Grab’s regional platform with Atome Financial’s AI-powered lending technology would allow both companies to reach millions of additional customers across Southeast Asia. Following the completion of the first stage, Atome Financial’s existing management team will continue overseeing its operations. Grab will also consolidate Atome Financial into its Financial Services segment, strengthening its position in the region’s growing digital lending market. The proposed transaction follows Grab’s recent acquisition activities, including its purchase of US-based investment platform Stash Financial and its agreement to acquire Foodpanda’s Taiwan operations for US$600 million. Grab said the initial acquisition would be funded entirely through its existing cash reserves. Looking ahead, the company expects its financial services business, including Atome Financial, to generate adjusted earnings before interest, taxes, depreciation and amortisation (EBITDA) of US$500 million by 2028. The segment is also projected to achieve a gross loan portfolio exceeding US$6 billion by the same year. At the group level, Grab has increased its 2028 financial targets, aiming to achieve adjusted EBITDA of US$1.7 billion. The company is also targeting compound annual revenue growth of more than 30% between 2025 and 2028. The planned acquisition reflects Grab’s continued efforts to expand beyond its core ride-hailing and delivery operations into digital banking, lending and other financial services. By combining Atome Financial’s lending technology and customer network with Grab’s existing ecosystem, the company aims to strengthen its regional financial services business and provide more financing options to consumers and merchants across Southeast Asia.
Investment & Market Trends

IFC Invests US$20 Million In Boost, Valuing Company At US$340 Million

The International Finance Corporation (IFC), the private-sector investment arm of the World Bank Group, has invested US$20 million in Malaysia’s fintech company Boost Holdings through preference shares, valuing the company at US$340 million after the investment. Boost confirmed the investment in an announcement on 28 September 2026, stating that the funding would support the development and expansion of its digital financial services. According to IFC’s project disclosure, the investment was completed on 17 August 2026 as part of efforts to strengthen financial inclusion and improve access to financing in Malaysia. The funding is expected to support Boost’s financing services for small and medium enterprises (SMEs) and individual consumers, particularly those who have limited access to traditional banking facilities. One of the key areas of focus is digital lending, including the use of alternative credit scoring methods to assess borrowers who may not have established credit histories. By using digital technology and alternative financial data, Boost aims to make financing more accessible to underserved individuals and businesses. The investment also comes as Boost continues discussions with other potential investors to secure additional funding for its future growth. According to a report by The Edge, Axiata Group chief executive officer and managing director Nik Rizal Kamil Nik Ibrahim Kamil indicated that further capital injections would provide Boost with greater flexibility to pursue its expansion plans. However, he did not disclose the identities of the potential investors or the amount of additional funding being sought. Under an agreement signed on 31 July 2026, IFC subscribed for approximately 11.7 million preference shares in Boost Holdings. The investment represents an important development in Boost’s fundraising efforts, although IFC’s exact ownership percentage and the specific terms attached to the preference shares have not been publicly disclosed. IFC had previously announced its proposed investment in December 2025, indicating its intention to lead an equity fundraising exercise for Boost. Boost Holdings operates a range of digital financial services across Malaysia and Indonesia, including digital payments, merchant solutions and financing products. The company focuses on using financial technology to provide convenient and accessible financial services to consumers and businesses. Its operations also include Boost Bank, one of Malaysia’s licensed digital banks. Boost Bank is a joint venture between Boost Holdings, which owns a 60% stake, and RHB Bank, which holds the remaining 40%. The digital bank officially began offering services to the Malaysian public in June 2024 after receiving one of the five digital banking licences issued in the country. Through its digital banking and fintech operations, Boost aims to expand financial services to a wider range of customers, including individuals and SMEs that may face difficulties obtaining conventional banking products. Before IFC’s investment, Axiata Group was the largest shareholder in Boost Holdings with a 77.76% stake. Great Eastern Digital held 19.90%, while Japanese trading company Mitsui owned the remaining 2.34%. IFC’s entry as an investor is expected to strengthen Boost’s financial position and support its plans to expand digital lending, banking and payment services. The investment also reflects growing institutional interest in Malaysia’s digital financial services industry, particularly businesses focused on improving financial accessibility through technology. With additional funding and continued investor support, Boost is seeking to strengthen its position in the regional fintech market while expanding its services to more consumers and businesses.

Property

AME Elite To Buy 176.5 Acres Of Land In Pontian For RM199.8 Million

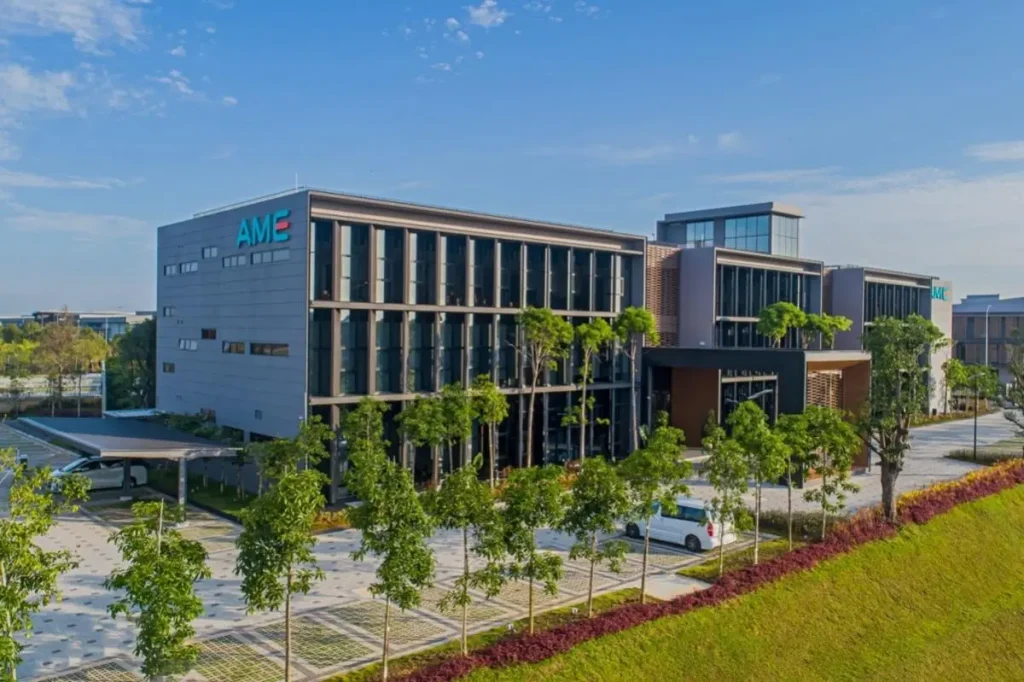
AME Elite Consortium Bhd has entered into four agreements to purchase 176.5 acres in Mukim Jeram Batu, Pontian, within the Johor-Singapore Special Economic Zone (JS-SEZ), for RM199.8 million. The land will be developed into an industrial area. In a filing with Bursa Malaysia, the company said no detailed development plans have been submitted, so it is too early to determine the project’s timeline, gross development value, development costs, expected profits or funding sources. The purchase will be made in cash and funded entirely through internally generated funds, AME Elite said in a statement. The sale and purchase agreement was entered into through AME Elite’s wholly-owned subsidiaries, Pulai Land West Sdn Bhd and Pulai Land East Sdn Bhd. AME Group’s short-term funds, cash and cash equivalents stood at approximately RM779.3 million, based on its latest interim financial report for the financial year ended June 30, 2026. The company said the purchase price represents a slight discount to the RM200 million market value ascribed by Knight Frank Malaysia Sdn Bhd. The proposed acquisition will allow AME Group to expand its land bank in a strategic location. The group expects the future development of the land to support earnings growth in the medium term, provided the development is properly planned. The lands are situated about 9km from the Malaysia-Singapore Second Link Expressway and 26km from the Tuas Checkpoint in Singapore, positioning the industrial park and manufacturing plant developer to capitalise on rising demand from foreign investors and manufacturers in the area. “The acquisition will strengthen our industrial development footprint and enable us to capitalise on the growth of foreign and domestic direct investments flowing into Johor,” said Dylan Tan Teck Eng, executive director and group CEO of AME Elite. The deal is expected to be completed by the first half of 2027. The acquisition follows a separate deal signed in March 2026 involving 31.8 acres of land in Senai for a total cash consideration of RM101.2 million. That deal is also expected to be completed by the first half of 2027. The two land banking exercises will together add more than 200 acres to the group’s remaining 295.3-acre land bank. AME Elite’s shares rose 0.8% to close at RM1.32 on Thursday, giving the company a market capitalisation of RM845.7 million.

Investment & Market Trends

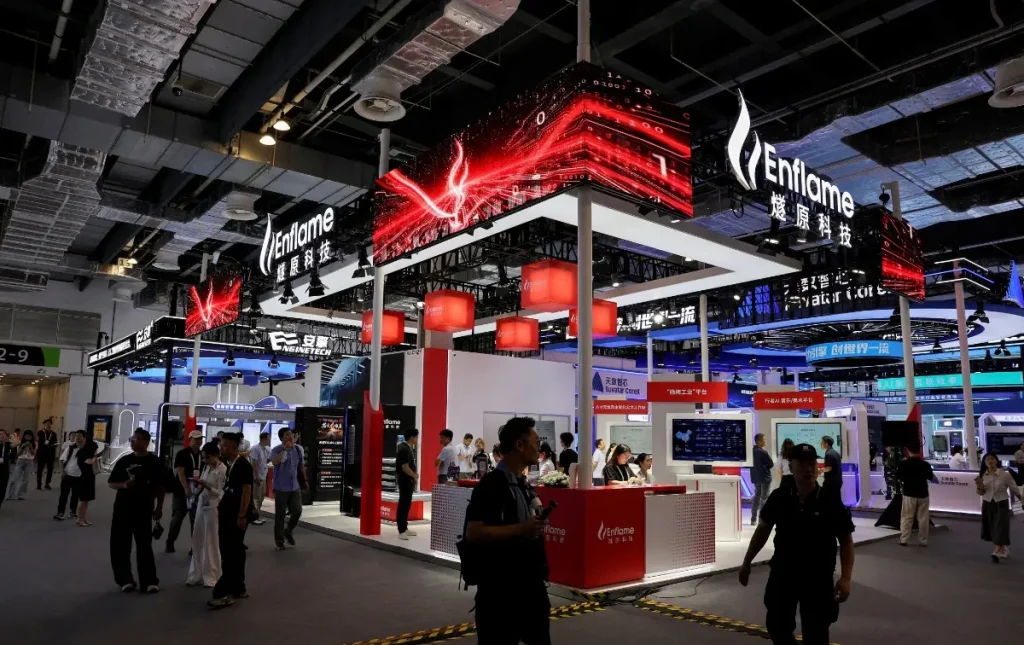
Tencent-Backed Enflame Shares Surge 179% On Shanghai Debut

Shanghai Enflame Technology Co made a strong debut on the Shanghai stock market, with its shares jumping 179% after the Chinese artificial intelligence (AI) chipmaker raised approximately 6.12 billion yuan (US$911 million or RM3.71 billion) through its initial public offering (IPO). The company’s shares closed at 397 yuan on Friday, significantly higher than its IPO price of 142.18 yuan per share. During early trading, the stock surged as much as 234%, reflecting strong investor demand for Chinese AI chip companies. The stock closed 179% higher at 397 yuan, compared with its IPO price of 142.18 yuan apiece after surging as much as 234% in early trading on Friday. Enflame sold 43 million shares in its IPO, attracting overwhelming interest from retail investors. Applications from individual investors exceeded the number of shares available to them by approximately 4,000 times. The company is the last of China’s so-called “four little dragons” of AI chipmakers to go public, following Moore Threads Technology Co, Biren Technology Co and MetaX Integrated Circuits. Although these companies initially experienced strong demand during their market debuts, their share prices have since declined significantly. Moore Threads, which recorded a 425% increase during its debut in December, has fallen more than 60% from its record high. Meanwhile, MetaX and Biren have each dropped more than 40% from their respective peaks. Despite these declines, investor interest in China’s AI semiconductor industry remains strong, supported by rising demand for advanced computing technology and continued investment in AI infrastructure. Enflame is among several Chinese technology companies developing domestic AI chips to support the country’s growing demand for computing power. The company specialises in AI accelerators used in cloud computing and data centres. Its chips support applications such as AI chatbots, recommendation systems and generative AI services. While Enflame remains smaller than major Chinese technology companies such as Huawei Technologies Co and Cambricon Technologies Corp, it has established a position in China’s expanding AI chip market. Tencent Holdings Ltd plays a major role in Enflame’s business, holding a 20% ownership stake while also serving as one of its largest customers. According to analysts at Huajin Securities, Enflame’s close relationship with Tencent is one of its key strengths. “The appeal of the company lies in its position as one of China’s leading cloud AI chipmakers, as well as Tencent’s dual role as both a key customer and major shareholder,” analysts including Li Hui said in a research note. However, the analysts also highlighted that Enflame continues to lag behind some competitors in revenue size and gross profit margins. Tencent’s contribution to Enflame’s revenue has increased substantially in recent years. In 2025, sales to Tencent accounted for approximately 84% of Enflame’s total revenue, compared with around 38% in 2024. Tencent uses Enflame’s technology across its internet and cloud computing operations, particularly in large data centres supporting AI applications and digital services. Despite its rapid expansion, Enflame has yet to achieve profitability. The company reported a net loss of 1.2 billion yuan in 2025, an improvement from the 1.5 billion yuan loss recorded in the previous year. For the first nine months of 2026, Enflame expects its net loss to be no more than 860 million yuan as it continues investing in technology development and business expansion. Revenue is also expected to increase significantly, with the company forecasting more than threefold year-on-year growth during the same period. Enflame previously recorded compound annual revenue growth of more than 80% between 2023 and 2025, reflecting growing demand for its AI computing products. The strong stock market debut highlights continued investor confidence in China’s AI chip industry, even as concerns remain over profitability, competition and the high costs of developing advanced semiconductor technology. For Enflame, its future performance will depend on maintaining strong customer demand, expanding its business beyond major clients such as Tencent and improving profitability as China’s AI industry continues to develop.

News

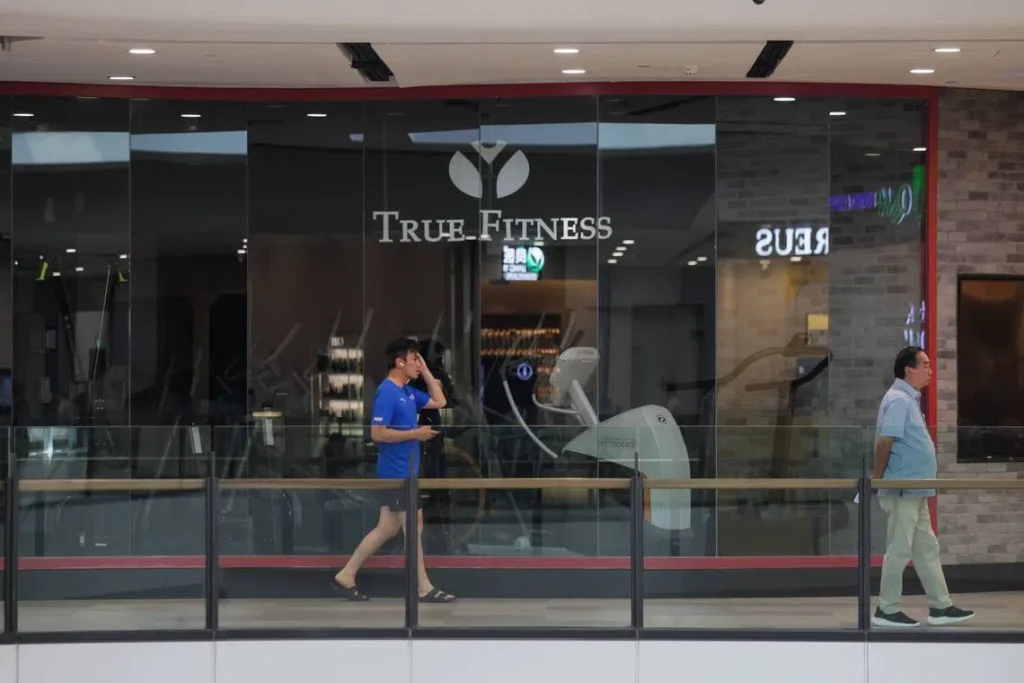
True Fitness And True Yoga Close Singapore Gyms Amid Liquidation

Singapore-based gym operators True Fitness Pte Ltd and True Yoga Pte Ltd have closed all their fitness centres across Singapore after entering provisional liquidation, marking another major setback for the country’s increasingly competitive fitness industry. The closures took effect immediately following the appointment of provisional liquidators on 10 September 2026, according to a notice published through the companies’ mobile application. “All clubs’ operations will cease with immediate effect,” the notice stated. Records filed with Singapore’s Accounting and Corporate Regulatory Authority (ACRA) also indicate that both companies have entered creditors’ voluntary liquidation, a process generally undertaken when businesses are unable to meet their financial obligations. Both True Fitness and True Yoga operate under True Yoga Holdings Pte Ltd. The sudden closures affect several fitness centres across Singapore, including True Fitness outlets at Novena Square, Tampines Junction and Ang Mo Kio. The group’s TFX-branded gyms also operate at Millenia Walk, CIMB Plaza and Funan mall. The shutdowns come amid growing financial pressure on Singapore’s fitness sector, where operators continue to face rising rental expenses, higher operating costs and intense competition for customers. Several other fitness businesses, including Ritual Gym, UFC Gym and Fenix Fitness, have also exited the Singapore market in recent years, highlighting the challenges of maintaining profitability in the industry. Financial records show that both True Fitness and True Yoga had been experiencing losses for several years before their closures. According to ACRA filings, True Yoga had accumulated losses of approximately S$82.8 million (US$65.3 million) by the end of 2025, while True Fitness recorded accumulated losses of around S$13.5 million. The financial difficulties raise concerns about the sustainability of gym operators that depend heavily on long-term membership subscriptions while managing substantial rental, staffing and maintenance expenses. Despite their financial challenges, both companies had continued promoting membership packages in the months leading up to the shutdowns. These included multi-year subscriptions offering access to gym facilities, group fitness classes, yoga sessions and reformer programmes across their network of clubs. Some membership packages extended beyond five years, with customers subsequently offered lifetime access for a monthly fee of S$49. The immediate closure of all clubs has created uncertainty for members holding active subscriptions, particularly those who had committed to long-term packages or made advance payments. It remains unclear whether affected customers will receive refunds or how outstanding membership obligations will be handled during the liquidation process. The situation also highlights the financial risks associated with prepaid fitness memberships, especially when operators experience prolonged losses or face difficulties meeting their operating expenses. For Singapore’s fitness industry, the closures add to concerns about the long-term viability of traditional gym business models in an environment where consumers have access to a growing range of boutique studios, specialised fitness programmes and alternative workout options. As liquidation proceedings continue, attention is expected to focus on the treatment of creditors and affected members, as well as the wider implications for Singapore’s fitness market. The closure of True Fitness and True Yoga demonstrates the increasing financial challenges facing established fitness operators, even those with multiple locations and an extensive customer base.

Energy & Technology

Before The Handover, There Is A Business To Run

A vehicle’s journey from factory to driver involves more than transport and a showroom handover. Accessories must be fitted, finishes inspected and vehicles maintained while awaiting delivery. For automotive brands, the quality of that work can shape a customer’s first impression before the engine is started.  Vision Automotive Technology (M) Sdn. Bhd. has built its business around these less visible stages of vehicle ownership. With more than 23 years of experience, the Malaysian company provides services that help automotive businesses prepare, maintain and restore vehicles throughout their working lives.  Managing Director & CEO of  Vision Automotive Technology (M) Sdn. Bhd. – YBhg. Dato’ Dr. Samanan Ratnam. Its portfolio covers original equipment manufacturer (OEM) automotive accessories, Pre-Delivery Inspection (PDI) installations, body and paint repair, vehicle detailing and Long Storage Maintenance (LSM). Imported vehicles and electric vehicles are areas of particular focus as it develops its capabilities.  Customers include manufacturers, authorised dealerships, multinational corporations, government agencies and fleet operators. The company names Sime Darby Group, DRB-HICOM, Johor Corporation, Bermaz Auto and the Malaysian Civil Defence Force among the organisations it has served.  The range of customers reflects a common requirement: vehicles need to be ready when they are needed. For a dealership, delays can complicate handovers. For a fleet operator, downtime can interrupt service delivery. For an automotive brand, inconsistent preparation risks undermining the experience promised by the product.  Vision Automotive Technology’s proposition is to coordinate services around that requirement. Its role extends from fitting accessories before delivery to restoring damaged bodywork and maintaining vehicles in storage. Each activity supports the condition, presentation and availability of an asset.  The company’s attention to LSM illustrates how its service mix is developing. Vehicles awaiting their next stage in the distribution process still require care. By expanding this capability for imported and electric vehicles, the business aims to address customer requirements that extend outside conventional workshop activity.  Its strategic direction follows three considerations: changes in the automotive industry, the practical needs of customers and the durability of the business itself. Investment decisions are assessed against whether they solve a customer problem, strengthen competitiveness and offer a credible route to profitable growth.  That framework imposes boundaries. The company says it avoids opportunities outside its automotive expertise and does not pursue expansion that would compromise quality or established relationships. Its preferred measure of progress combines stronger capabilities, dependable execution and continued customer confidence.  The commercial logic is rooted in repeat business. Automotive clients need partners who understand their operating requirements and can deliver consistently across assignments. Familiarity with those requirements can make coordination more effective, particularly when schedules change or unexpected work arises.  Much of the effort remains invisible to the end customer. Planning, inspections, workmanship and coordination precede the completed installation or polished vehicle. Vision Automotive Technology says its processes are intended to meet OEM standards while maintaining consistency across its services.  For a business offering several connected services, that consistency is a management task. Customers may encounter different teams at different stages, but expect the same standard of work and communication. The company’s ambition to become an integrated provider depends on making those transitions reliable.  Its next phase therefore involves organisational development alongside service expansion. It is strengthening leadership, investing in employee development and adopting digital technologies, while improving operating systems intended to support efficiency and customer experience.  The emphasis on people is particularly relevant to its positioning. Equipment and service menus can be replicated; the judgement and discipline required to deliver work consistently must be developed within teams. Accountability matters when a vehicle passes between preparation, repair, detailing and delivery.  Vision Automotive Technology wants to build a broader regional reputation from that foundation. Its immediate task is to ensure that expanding capabilities remain supported by stronger systems and skilled employees. In an industry where attention naturally gravitates towards the latest model, its opportunity lies in making every stage around the vehicle work more reliably. That is a quieter proposition than selling cars, but one closely tied to the confidence with which they reach their owners.

Energy & Technology

The Cost Of Standing Still

When a machine stops working, the problem rarely stays with the machine. A construction crew may lose hours, a warehouse may fall behind schedule, or a production team may have to reorganise its work. For companies that depend on access and material handling equipment, a quick response can be as valuable as the equipment itself.  That is the opportunity LM Equipment Sdn Bhd has built its business around. Established in 2021, the Malaysian company rents, sells and maintains Mobile Elevating Work Platforms (MEWPs), material handling equipment and industrial access solutions. Its customers span construction, manufacturing, semiconductors, logistics, warehousing and infrastructure.  Sales Manager of LM Equipment Sdn. Bhd. – Jeffrey Lim. “We often say that we are in the equipment business, but in reality, we are in the business of keeping industries moving,” the company says.  Supplying a machine is only the beginning. Customers also need it to arrive in working condition, perform safely and receive technical attention when something goes wrong. LM Equipment has made service reliability and response capability central to its offer.  That focus grew out of a gap it saw in the market. Businesses could source equipment, but many wanted a supplier that would remain accountable after delivery. As pressure to improve productivity and workplace safety has increased, expectations have become more demanding. Customers now look for well-maintained fleets, faster communication and support that helps them avoid disruption before it happens.  Much of that work is invisible. LM Equipment says every machine undergoes preventive maintenance and a pre-delivery inspection. Behind each rental are technical planning, fleet monitoring and a process for responding to breakdowns. These routines may attract less attention than a new piece of machinery, but they shape the experience customers remember when deadlines are tight.  The company is also using digital tools to manage a growing operation. Fleet and rental management systems help it track equipment, monitor performance and coordinate service. GPS monitoring supports logistics planning, reducing unnecessary travel while helping teams make better use of available assets. Online communication and process automation are intended to make the customer experience more efficient.  Expansion, however, brings a familiar challenge: the habits that work in a small team do not always survive a larger one. LM Equipment has introduced standard operating procedures, KPI monitoring and regular management meetings to make service more consistent as it grows. Its leadership is shifting from direct oversight of daily tasks towards developing teams that can make sound decisions themselves.  That discipline also guides where the company invests. Decisions about adding equipment or entering a new market are assessed against customer demand, fleet utilisation and long-term returns. LM Equipment wants to expand into key industrial regions, but says it will avoid growth that weakens service quality or financial discipline.  Its approach to sustainability follows the same practical logic. Digital processes reduce paper use, while maintenance and refurbishment help extend the useful life of equipment. Better fleet and transport planning can also limit unnecessary journeys. For LM Equipment, using resources carefully is part of running a stronger business.  The ambition is to become a leading one-stop equipment solutions provider for Malaysia’s industrial and construction sectors. That will require a larger fleet and stronger technical capabilities, alongside continued investment in people and management systems.  LM Equipment’s next test is whether it can preserve its responsiveness as its reach expands. In industries where delays carry a real cost, dependable service is more than a selling point. It is what allows customers to keep working.

News

The Next Warehouse Expansion May Be Above Your Head

For a business running out of warehouse space, moving to larger premises can appear the natural next step. It is also a decision that brings additional rent, relocation costs and operational disruption. Before committing, there is another asset worth examining: the unused space above the inventory already on the floor.  That is the commercial opportunity for Global Steel Engineering, a Malaysian industrial racking specialist serving manufacturers, warehouse operators and third-party logistics providers. Its proposition is to help customers extract more capacity from existing premises through storage systems designed around the way their businesses operate.  Marketing & Export Director of  Global Steel Engineering (M) Sdn. Bhd. – Chin Kok Yoon, Dennis  With a strong presence in Selangor and the Klang Valley, the company provides structural design, three-dimensional layouts, load specifications, supply and installation. Its portfolio includes heavy-duty pallet and cantilever racking, alongside configurations intended for denser storage requirements.  The underlying problem is often accumulated rather than sudden. As businesses grow, additional stock finds temporary positions that become permanent. Walkways narrow, retrieval becomes slower and forklift operators spend more time navigating obstacles. Eventually, a layout problem begins to look like a property problem.  Reorganising that environment can change the calculation. Using vertical space more effectively may allow a company to hold additional inventory without immediately expanding its physical footprint. The financial benefit, however, depends on whether the resulting layout also supports efficient movement.  Storage density alone is an incomplete measure of performance. A warehouse can accommodate more pallets and still become harder to operate. If retrieving one item requires repeatedly moving others, the apparent capacity gain comes with a recurring cost in labour and handling time.  Global Steel Engineering therefore places greater emphasis on planning before equipment is supplied. Product dimensions, load requirements, retrieval frequency and forklift movements inform the design. The aim is to establish how additional storage will function during an ordinary working day, rather than simply demonstrate how much steel can fit inside a building.  Different configurations involve different compromises. Double-deep and drive-in systems can suit particular storage needs, while other operations require more immediate access to individual loads. The appropriate choice depends on stock profiles, handling equipment and the pace at which goods move through the facility.  This makes the supporting infrastructure important. Racking concentrates weight at specific points, bringing floor condition and levelness into the planning process. The company describes a broader approach that considers slab integrity and floor maintenance, including epoxy coatings, alongside the storage installation.  Its CIDB Grade G3 registration forms part of its credentials as a local contractor. The wider proposition rests on coordinating design, material supply and installation, giving customers a single partner across stages that might otherwise be managed separately.  For smaller and mid-sized operators, that coordination can be commercially useful. They need technical capability, but also a supplier responsive to budgets, installation schedules and the practical constraints of an occupied warehouse.  Delivery is consequently as important as design. An installation must account for incoming goods, ongoing dispatches and the people working around the site. Poor sequencing can disrupt the operation whose efficiency the investment is meant to improve.  Global Steel Engineering’s strategic direction places greater attention on this relationship between storage equipment and facility performance. Its opportunity is to become involved earlier in customer decisions, when layouts and operating requirements can still be shaped, rather than compete solely on the price of racks.  Maintaining that position as workloads increase requires consistent execution. Clear specifications, documented procedures and communication between planning and installation teams help preserve quality when several projects are running simultaneously.  For customers, the investment case extends across the system’s working life. Purchase price matters, but so do accessibility, maintenance, potential reconfiguration and the suitability of the installation for changing stock requirements.  The most persuasive result is a warehouse that accommodates growth while remaining straightforward to operate. Before a business signs for more space, it may be worth establishing whether its existing building has reached its limit—or whether its layout has. The distinction can materially change the cost and timing of its next expansion decision.   

Energy & Technology

The Next Battle For the Grid Is In The Data

A smart meter records electricity consumption. Its commercial value, however, increasingly depends on what happens after the reading. For utilities managing extensive distribution networks, turning millions of measurements into accurate billing, operational decisions and useful customer information is a challenge that hardware alone cannot solve.  That is the opportunity GMS is pursuing as it prepares to move from manufacturing smart grid equipment towards providing the software platforms that help utilities operate it. The ambition would deepen its role in an industry where reliability, technical compatibility and execution matter as much as product specifications.  Managing Director of  Global Merge Synergy Sdn. Bhd. – Saifulbahrim bin Mamat. An MOF-accredited Bumiputera vendor, GMS supplies advanced engineering, hardware manufacturing and enterprise software solutions for utility infrastructure. Its portfolio includes single-phase and three-phase Advanced Metering Infrastructure (AMI) smart meters, STS 2.0 prepaid systems, transformers, switchgear and intelligent solar street lighting.  Its target market includes national and state electricity utilities such as Tenaga Nasional Berhad, Sabah Electricity and Sarawak Energy. Supporting its hardware capabilities is an in-house meter testing laboratory accredited to ISO 17025, giving the company local control over a critical part of product validation.  GMS identified its opening when TNB sought to introduce smart meters across a customer base the company describes as approximately 11 million. At the time, it saw a shortage of local vendors combining the technology and delivery capacity required for deployment at scale.  That opening has become more competitive. More suppliers can now provide smart meters in substantial quantities, reducing the advantage of availability alone. For GMS, defending its position increasingly depends on procurement discipline, efficient production and dependable delivery across its supply chain.  Its strategic response is to invest in areas where technical capability can sustain a longer relationship with utilities. These include software that allows equipment from different vendors to work together, expanded local manufacturing and technology transfer with international research and development partners such as Sanxing.  The distinction is commercially significant. Selling a meter generates an equipment transaction. Supporting the systems through which meters communicate, consumption is analysed and payments are administered creates a more continuous operational relationship. GMS wants growth to reflect that deeper integration.  Getting there requires more than adding software to a catalogue. Utility platforms must accommodate existing infrastructure, established workflows and demanding service requirements. GMS regards its understanding of local utility operations and fallback network arrangements as advantages in connecting new technology with conditions in the field.  Its immediate operational challenge remains capacity. Rising demand has required additional manpower, expanded production capability and more comprehensive training, while maintaining consistent quality. Scaling quickly creates little value if accuracy or delivery performance deteriorates.  Leadership has consequently shifted towards specialised divisions and more structured corporate governance. Operations work within ISO 9001:2015 and ISO 17025 frameworks, while management prioritises developing local engineering and production teams capable of handling higher demand.  The company has also committed capital to its Bukit Jelutong facility and precision testing laboratory. It presents that investment as a deliberate choice to strengthen local assembly and validation rather than rely primarily on outsourced supply.  Keeping those activities in Shah Alam gives GMS greater oversight of product quality and asset reliability. The company also sees potential environmental benefits from reducing international logistics, although its central business argument is the ability to support infrastructure intended for prolonged service.  Its next ambition extends into electricity and water platforms. Internally, that means cultivating capabilities in software engineering, Edge AI, cloud database analytics and secure automated financial settlement.  The transition will test whether manufacturing expertise can support a broader technology business. GMS has established its proposition around delivering equipment utilities can deploy. Its next phase depends on proving it can also help them interpret, manage and act on the information that equipment produces. Success would make its software and engineering teams increasingly central to the daily operation of utility networks, extending its role from supplying individual devices to supporting the decisions built around them over time. 

News

Malaysia’s Building Boom Puts Specialist Suppliers To The Test

Landmark buildings are remembered for their height, design and presence on a skyline. Less visible are the components that help them withstand movement, accommodate foot traffic and remain usable over time. For Sun Synergy, those details form the foundation of a specialist distribution business.  Operating in Malaysia since 1999, the company supplies architectural building materials to architects, interior designers, contractors and specialist installers. Its portfolio includes Latham Australia’s mechanical expansion joints, Progress Profiles Italy’s tile installation accessories and profiles, and Vexcolt’s entrance flooring and tactile indicators.  Managing Director of Sun Synergy Sdn. Bhd. – Ng Cheong Foo Its project references include the Petronas Twin Towers, Merdeka 118, TRX, Pavilion, IOI City Mall and Malaysia’s MRT and LRT networks. These projects illustrate the market it serves: buildings and infrastructure where technical performance must endure long after construction ends.  The underlying problem is straightforward. Buildings expand, contract and shift. Without properly designed joint systems, that movement can contribute to cracked finishes, water ingress and costly repairs. Entrance systems and tactile indicators address another practical requirement: helping people move safely and confidently through public spaces.  Sun Synergy says the market has changed substantially since engineered expansion joints first gained traction locally. Product awareness has improved, while cheaper alternatives have intensified competition. Availability alone offers little protection for a distributor.  Its response is to compete through technical advice. Reading architectural drawings, discussing movement requirements and helping consultants resolve details at the design stage create opportunities that a product catalogue cannot secure.  That approach also determines which opportunities it pursues. Projects offering early specification engagement receive attention and resources. Tenders decided almost entirely on price are less attractive, particularly where winning would undermine margins or relationships with established principals.  The financial record reflects that selective approach. Audited revenue rose from RM3.16 million in FY2022 to RM4.11 million in FY2023, before settling at RM4.00 million in FY2024. The company regards maintaining that position through commodity disruption, freight volatility and material cost pressures as a meaningful achievement.  Its next challenge is to broaden its offering without weakening its positioning. Sun Synergy is introducing cost-competitive Chinese product lines for budget-sensitive projects, while retaining its premium portfolio. Managing that balance will require clear product selection and consistent technical support.  The company sees infrastructure development and commercial fit-outs as sources of future demand. Accessibility and green building requirements are also influencing customer decisions. Converting those opportunities into sustainable earnings, however, depends on securing the right specifications early and maintaining the resources needed to support projects through completion and subsequent maintenance.  People remain a constraint. Technical sales staff must understand drawings and communicate credibly with consultants, skills the company says are difficult to recruit. It has sent employees to Latham Australia for factory training and plans further training with Progress Profiles Italy.  The business has consequently remained small and specialised, supported by MYOB for finance and Rework CRM for sales. Working capital demands equal attention: larger construction projects can bring longer payment cycles, making sales growth an incomplete measure of business health.  Accountability is another part of its proposition. Sun Synergy handles warranty and technical matters directly with its principals, giving customers one point of contact when problems arise. Directors remain personally accessible, an arrangement intended to simplify resolution across complex project teams.  Internally, its sustainability efforts are developing. Rooftop solar at its headquarters and electric vehicles used by three directors represent initial investments. The company acknowledges that a formal ESG policy and carbon baseline remain to be established.  Its regional ambition centres on Indonesia, Brunei and Thailand. Expansion, however, depends on building stronger foundations at home: more specification sales capability, financing suited to longer project cycles, and documented training, ESG and operating processes.  For a business built around managing movement, the next step requires careful preparation. Its ability to carry technical expertise across borders will matter as much as the products it takes with it. Regional growth will test whether its personal service model can operate consistently across a wider market.   

Scroll to Top

Subscribe
FREE Newsletter