Author name: theexchangeasia admin

ESG

M Lighting: Setting The Mood, Changing The Way We Experience Space

Walk into a restaurant and something makes you want to stay a little longer. Step into a hotel lobby and it immediately feels warm and inviting. Enter a boutique and suddenly the colours, textures and products seem more appealing. We often attribute these feelings to good interior design. But there is another element quietly working in the background: light. It can make a room feel intimate or expansive, energetic or calming, luxurious or ordinary. It can draw attention to an object, soften an environment and influence how people experience a space without them necessarily knowing why. Executive Director of M Lighting Design & Renovation Sdn Bhd – Catherine Tee Yen Fang. For M Lighting Design & Renovation Sdn Bhd, this is where lighting becomes much more than something switched on when a room gets dark. It becomes part of how a space makes us feel. Established in 2003, the Malaysian company has spent more than two decades working across commercial, industrial and residential environments. Its role has evolved from supplying lighting products into managing complete lighting projects through Engineering, Procurement, Construction and Commissioning (EPCC). The evolution reflects a changing market. Clients are no longer simply asking which light they should buy. Increasingly, the question is: What do we want this space to feel like? Consider a restaurant. Food may be the centre of the experience, but lighting affects how dishes appear on the table, how comfortable customers feel and even whether they want to stay longer. In retail, it can highlight merchandise and reinforce a brand’s identity. At home, it shapes warmth, comfort, safety and the atmosphere of everyday life. Sometimes clients know exactly what they want a space to feel like — warm, sophisticated, dramatic or comfortable — without knowing the technical formula required to create it. That formula involves decisions around colour temperature, brightness, glare control, beam angles, positioning and installation. M Lighting’s role is to translate a desired feeling into a practical technical solution, and then make sure the result on site delivers what was imagined. That last part matters. A lighting concept can look impressive on paper yet perform very differently once installed. A beam can fall at the wrong angle. Glare can make an otherwise beautiful room uncomfortable. A fitting chosen primarily for appearance or price can prove inefficient or difficult to maintain over time. M Lighting identified this disconnect between design and execution early in its business. It has since shaped the company’s move towards a more complete project-management model covering consultation, site measurement, design, procurement or production, installation, commissioning and after-sales maintenance. The objective is no longer simply to leave a client with lighting fixtures. It is to leave them with the intended experience. There is also something almost contradictory about good lighting: the better it is, the less likely we are to notice it. Instead, we notice the architecture, the food on the table, the merchandise on display or the person sitting opposite us. Lighting becomes the quiet layer holding the experience together. Behind that simplicity, however, is considerable judgement. Where should the light fall? Will it create glare? Does it complement the materials and colours? Is it suitable for how people move through the space? Will it remain practical to maintain years later? These questions have become increasingly important as sustainability changes the way businesses think about their spaces. For M Lighting, sustainability begins with practical choices rather than sweeping statements. A cheaper fitting may save money initially but prove more expensive if it consumes more energy, requires frequent maintenance or needs earlier replacement. The company therefore encourages clients to consider energy efficiency, durability and lifecycle cost alongside aesthetics and initial price. It also supports retrofits and upgrades where existing lighting can be improved rather than unnecessarily replaced. Its philosophy is straightforward: design correctly, select responsibly, install professionally and maintain for the long term. As M Lighting grows, however, another challenge has emerged — ensuring that expertise and attention to detail can be repeated consistently across more projects. The company is strengthening its processes, documentation, digital workflows, knowledge transfer and talent development. The goal is to move away from knowledge that sits primarily with experienced individuals towards standards embedded throughout the organisation. It is also taking a measured approach to expansion. Not every project needs to be accepted, particularly when unrealistic budgets, timelines or expectations could compromise delivery. M Lighting does not want its future to be defined by competing solely on price or simply completing more projects. It wants to become a long-term project partner. More than two decades after it began, M Lighting is ultimately building its next chapter around something surprisingly human for a technical business: how people feel when they enter a space. Because we may rarely look up and notice the lighting itself. But we almost always notice the mood it creates.  
ESG

Emerging EPC Is Building A Business Around What Industry Cannot Afford To Stop

In heavy industry, a machine stopping is rarely just a machine stopping. A compressor failure can interrupt production. A critical pump going offline can disrupt an entire process. Unplanned downtime can quickly become a problem involving lost output, missed delivery commitments, higher costs and, in the worst circumstances, safety. For Emerging EPC Sdn Bhd, that risk has become the foundation of a much bigger business proposition: keep industry running. The Malaysian industrial engineering company operates across mission-critical sectors including oil and gas, petrochemicals, power generation, manufacturing and future energy. Its capabilities stretch from engineering design and equipment supply to system integration, commissioning, maintenance, refurbishment, digital monitoring and lifecycle extension. But equipment is increasingly only part of the story. Emerging EPC wants to know what happens to that equipment five, ten or more years after installation — how efficiently it is performing, when intervention is needed and how its useful life can be extended. That is pushing the company from engineering supplier towards something broader: a lifecycle reliability partner.   Fixing It Before It Breaks For decades, maintenance across many industries followed a familiar pattern: something fails, then someone fixes it. The economics of modern industry are making that increasingly difficult to justify. Operators are under pressure to improve productivity while controlling costs, reducing energy consumption, meeting safety expectations and addressing sustainability requirements. Equipment cannot simply work; businesses increasingly need to understand how well it is working. Emerging EPC sees this shift as an opportunity. Through its Emerging Data Analytics (EDA) and EARS platforms, the company is adding digital monitoring and data into its engineering capabilities, helping customers move towards more informed maintenance and reliability decisions. It represents an important evolution in the company’s business model. Instead of supplying a compressor package and considering the transaction complete, Emerging EPC can remain involved throughout the asset’s operating life. The commercial logic is equally significant. Its preferred model of growth is not simply finding more customers. It is becoming more valuable to the customers it already has. A relationship might begin with compressors, expand into filtration, move into rental solutions and eventually incorporate IoT monitoring and lifecycle services. In other words, growth comes from depth, not simply volume. That philosophy also means being willing to turn business away. Emerging EPC says it is deliberately avoiding contracts where it cannot maintain its quality standards, rather than chasing revenue for the sake of a larger top line. For a company whose reputation rests on reliability, a short-term sales gain is not worth a long-term credibility problem.   Sustainability Before It Became Fashionable That longer view is also evident in Emerging EPC’s approach to sustainability. The company began its sustainability journey in 2022, treating it not simply as an ESG reporting exercise but as part of how the organisation itself needed to evolve. Investment has gone into ESG data collection, sustainability reporting, ERP development, industrial IoT capabilities, staff training, governance and operational efficiency. For an SME, those investments involve a genuine trade-off. Money and people committed to long-term capabilities cannot simultaneously be deployed towards immediate sales. Emerging EPC chose to invest anyway. Its sustainability proposition also extends directly to customers. Improving equipment reliability, reducing downtime, extending asset life and optimising energy consumption can make existing industrial operations more efficient without simply replacing assets. The company has subsequently gained recognition through PETRONAS and wider industry sustainability platforms, while sharing its experience with other SMEs through SAMENTA and industry programmes. But its next transformation could be larger still.   Malaysia Is No Longer the Finish Line Emerging EPC already has a regional footprint. Now it wants those markets to become businesses in their own right. Its ambition is to become a genuine regional energy solutions company, capable of independently securing significant projects in Vietnam, Thailand and Indonesia rather than simply being a Malaysian company with overseas offices. At the same time, the energy transition is forcing the company to think about where industrial demand will come from next. Its Emerging Zapp platform is intended to build capabilities around customers navigating the shift away from pure fossil-fuel dependency, positioning the business for an energy landscape that will look increasingly different from the one in which it was built. Technology and geography, however, are only two pieces of that expansion. The third is people. For Emerging EPC, its ability to scale across Southeast Asia will ultimately depend on developing another generation of technical and commercial leaders capable of running the business in individual markets. That may prove to be the company’s most important engineering project yet. Because equipment can be purchased, technology can be developed and offices can be opened. Building an organisation that performs reliably across borders is considerably harder. And for a company that has built its reputation around keeping critical assets running, the next test is whether it can apply that same philosophy to itself.  

Investment & Market Trends

Keyfield Buys Mega Dredger For US$25m, Enters Dredging Business

Keyfield International Bhd is venturing into the dredging industry through the acquisition of a mega trailing suction hopper dredger (TSHD) at a price 61% below its independently assessed fair-market value. The offshore support vessel operator entered into a deal on Wednesday with Inai Rimba Sdn Bhd, which has receivers and managers appointed, to acquire the 10-year-old Inai Kenanga on an “as-is, where-is” basis for US$24.67 million (RM99.7 million), according to the group’s filing with Bursa Malaysia. Keyfield will nominate a special-purpose vehicle (SPV) to ultimately own the vessel. The SPV will eventually be held 60% by Keyfield and 40% by Singapore-based Star Naval 1 Pte Ltd (SNPL), which has an option to increase its stake to 45%. SNPL is co-owned by Starhigh Asia Pacific Pte Ltd and Naval Elite Ltd. Starhigh, founded in 2006, is involved in dredging, land reclamation, coastal protection and shoreline management across Southeast Asia. “This acquisition marks our foray into the dredging industry and accelerates our expansion beyond the oil-and-gas sector,” said Keyfield group CEO and executive director Datuk Darren Kee Chit Huei in a statement. “It is our second acquisition of a non-O&G vessel, following last year’s acquisition of Keyfield Blessing, our cable-laying barge that is currently on-hire in the Middle East.” The group added that the move forms part of Keyfield’s longer-term plan to raise contributions from non-O&G activities to as much as 20% of total group earnings. Following the acquisition, its operations will span offshore support vessel chartering, cable laying, marine infrastructure, coastal development and dredging. An independent valuation by Armal Marine and Offshore Sdn Bhd, dated April 25, placed Inai Kenanga’s fair-market value at US$63.7 million. Completed in 2016, Inai Kenanga was, at the time, the largest dredger in Asia and the third-largest in the world. The Malaysian-flagged vessel measures 197.7m in length, with a deadweight tonnage of 41,244 tonnes and a hopper capacity of 32,205 cu m. It was built by Selat Melaka Shipbuilding Corp Sdn Bhd with engineering support from Vuyk Engineering Rotterdam. Keyfield said constructing a new vessel with similar specifications would cost upwards of US$150 million, while Inai Kenanga itself was reportedly built at a cost of about RM1.2 billion. “With the former owner of Inai Kenanga having entered receivership, we were presented with a unique opportunity to acquire this asset at below market value,” Kee said. “Leveraging the strength of our balance sheet, this acquisition will be funded through our internal cash, hence not requiring any borrowings.” Keyfield will fund US$23.8 million of the purchase consideration, while SNPL will contribute US$900,000. Both parties will also make initial investments of US$400,000 and US$100,000, respectively. SNPL, meanwhile, will bear the estimated US$15 million cost of reactivating the vessel. Should the actual reactivation and pre-operating costs exceed that amount, SNPL has agreed to continue funding the excess through shareholder loans to the SPV. Keyfield will fund its portion entirely through internally generated funds, including part of the proceeds from its recent disposal of Keyfield Compassion, without taking on any additional borrowings. Following the vessel’s planned reactivation, Keyfield and Starhigh intend to pursue dredging projects across Southeast Asia, particularly in Malaysia and Singapore, Kee said. “Starhigh brings relevant industry network and expertise that complements our marine asset ownership and operational capabilities,” he added. The group expects the acquisition to begin contributing positively to earnings from FY2027, subject to the successful reactivation and commercial deployment of the dredger. Shares of Keyfield closed two sen, or 1.5%, lower at RM1.35 on Wednesday, valuing the group at RM1.09 billion. The stock has fallen more than 11% year-to-date.

The Executives

Bank Islam Names Wan Mohd Fadzmi As New Chairman

Bank Islam Malaysia Bhd has named Datuk Wan Mohd Fadzmi Che Wan Othman Fadzilah as its new independent and non-executive chairman, with the appointment taking effect on Thursday, Aug 27. Chairman of Bank Islam – Wan Mohd Fadzmi. He succeeds Tan Sri Ismail Bakar, who retired from the position on Aug 22 after six years at the helm. According to a bourse filing on Wednesday, Wan Mohd Fadzmi brings more than 30 years of domestic and international banking experience, having held various senior leadership roles at Malayan Banking Bhd and RHB Bank Bhd. He also previously served as president and CEO of Agrobank. He currently sits on the boards of Zurich Takaful Malaysia Bhd, Zurich General Takaful Malaysia Bhd, Malaysian Rating Corporation Bhd, and publicly listed Hap Seng Consolidated Bhd. “His past directorships include, among others, the chairman of the Labuan Financial Services Authority and Sumitomo Mitsui Banking Corp Malaysia Bhd, as well as an independent non-executive director of Bank Pembangunan Malaysia Bhd,” the filing added. Bank Islam shares closed two sen, or 0.95%, higher at RM2.13 on Wednesday, valuing the group at RM4.83 billion.

Property

Axis REIT To Acquire Three Industrial Land Parcels In Klang For RM61m

Axis Real Estate Investment Trust is acquiring three adjoining parcels of industrial land with warehouse facilities in Taman Perindustrian Pulau Indah, Klang, for RM61 million. In a Bursa Malaysia filing on Wednesday, the REIT said its trustee, RHB Trustees Bhd, had entered into a sale and purchase agreement with Megalift Sdn Bhd, the owner of the properties, for the proposed acquisition. The 99-year leasehold land, spanning a total area of 29,101.59 sq m, houses three blocks of warehouses and ancillary buildings with a gross floor and net lettable area of approximately 16,856 sq m. The property is currently fully owner-occupied by Megalift and used for warehousing operations. Upon completion of the acquisition, Megalift will lease back the property under a five-year leaseback arrangement, providing Axis REIT with an initial monthly rental of RM316,826.90, subject to agreed rental increases over the course of the lease period. In a separate statement, Axis REIT Managers Bhd chief executive officer and executive director Leong Kit May said the proposed acquisition aligns with Axis REIT’s strategy of expanding its portfolio through industrial assets located in prominent areas. “The property is located within Taman Perindustrian Pulau Indah, an important industrial hub within Port Klang with access to major highways,” she said, adding that its close proximity to Northport, Westport and Southport — key shipping terminals serving Port Klang — further supports its strategic role in supply chain and distribution operations. The acquisition will be funded through Axis REIT’s existing bank facilities and is expected to be completed by the first quarter of 2027. Axis REIT units closed seven sen, or 3.7%, lower at RM1.85 on Wednesday, valuing the industrial-focused REIT at RM3.75 billion.

Lifestyle

The More Digital Life Becomes, The More Real Experiences Matter

Children have never had more entertainment available to them. It is instant, personalised and almost permanently within reach. Yet as screens occupy a growing share of everyday life, another market is developing around something considerably less technological: getting people out of the house. Sambill Park is betting on it. Managing Director of Sambill Park (Malaysia) Sdn Bhd – Wei Chi Wong. The Malaysian sports, entertainment and family lifestyle company creates physical experiences ranging from youth sports academies and competitions to family attractions, recreational facilities and community events. It is also the company behind Funtopia, recognised by the Malaysia Book of Records as Malaysia’s Largest Inflatable Theme Park. But management increasingly sees the business as something larger than organising events or operating attractions. Sambill Park wants to build intellectual property around real-world experiences — and eventually take those concepts across Southeast Asia.   Competing With the Screen The underlying consumer problem is difficult to ignore. Children spend significant amounts of their leisure time digitally entertained, while parents are increasingly looking for activities that provide recreation, learning and meaningful family time. Sambill Park sees an opportunity between conventional sports training and traditional family entertainment. Rather than offering a single activity, it develops concepts combining physical participation, youth development, entertainment and community engagement. That distinction has become more important as consumer expectations have evolved. Families are no longer necessarily paying simply for access to an activity. They expect convenience, value and an experience memorable enough to justify their time. The competition is therefore not always another theme park, sporting programme or event. Sometimes it is simply staying home.   Turning Experiences Into Intellectual Property For Sambill Park, that creates an interesting business challenge. Events are temporary by nature. A successful event may attract thousands of people, but when it ends, so does that particular revenue opportunity. Intellectual property changes the equation. The company is increasingly focused on developing proprietary concepts and operating models that can be repeated across different locations rather than continuously building one-off projects from scratch. When considering new opportunities, Sambill Park asks whether they strengthen its existing ecosystem, whether they can be scaled efficiently and whether they can create sustainable value for customers, partners and shareholders. That has meant being willing to turn down some shorter-term commercial opportunities. Instead, resources have been directed towards proprietary brands, recurring community programmes, strategic partnerships and concepts capable of travelling beyond a single venue. The objective is not simply to organise more events. It is to own more of what makes those events valuable.   The Difficult Part of Getting Bigger That strategy also changes the organisation required to deliver it. In a founder-led company, speed can be an advantage. Decisions are made quickly, communication is direct and the person with the vision is often closely involved in execution. Scale makes that considerably harder. As Sambill Park has grown, maintaining consistency, accountability and culture across more activities has become a bigger management challenge. The company’s leadership is consequently moving away from direct involvement in day-to-day operations towards strategy, governance and talent development. Teams need authority to make decisions. Management processes have to replace informal communication. Future leaders must understand the organisation well enough to operate without constant founder involvement. Sambill Park describes its next transition as moving from a founder-driven organisation to a systems-driven one. For many SMEs, that is one of the most difficult stages of growth. A founder can build a successful business. Building an institution capable of growing independently of that founder is a different achievement.   Why Bigger Isn’t Necessarily Better Sambill Park is also becoming more selective about what growth means. Revenue, locations and headcount are obvious measures, but the company increasingly looks at brand equity, customer loyalty, intellectual property and whether its business models can be replicated. It does not want growth that weakens culture or financial discipline simply to increase scale. That philosophy has influenced its approach to sustainability as well. Rather than defining sustainability only through environmental measures, Sambill Park includes the durability of the business and its impact on communities. Over the past 12 to 18 months, it has prioritised longer-term investment in youth development, family activities and proprietary platforms even where shorter-term projects could have produced faster revenue. The trade-off is deliberate: slower immediate returns in exchange for assets and programmes that can continue creating value.   Taking the Model Across Southeast Asia The next test is regional. Sambill Park wants to evolve from a Malaysian operator into a Southeast Asian platform for sports, entertainment and family experiences. Rather than merely opening more venues, the ambition is to build a portfolio of concepts, brands and operating systems that can be replicated through strategic partnerships in different markets. That will require stronger technology, governance, processes and a deeper management bench. But there is a broader consumer bet underpinning the expansion. Digital entertainment is unlikely to retreat. Artificial intelligence, gaming, streaming and increasingly immersive technology will continue competing for attention. Sambill Park is betting that this will not eliminate demand for physical experiences. It may make good ones more valuable. People still want places to meet. Parents still want their children to move, learn and interact. Communities still need reasons to come together. The business opportunity lies in turning those needs into experiences people are willing to leave their screens for. Because the more of life that happens online, the greater the premium may become on experiences that can only happen in the real world.  

Lifestyle

Behind Malaysia’s Japanese Food Boom

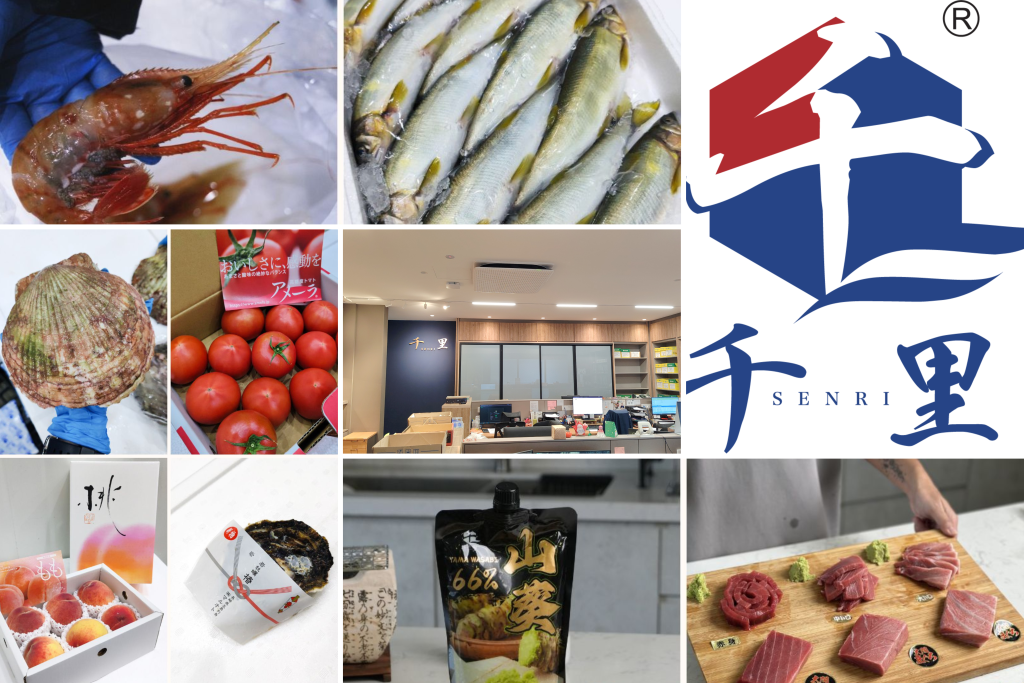
A diner ordering sashimi in Kuala Lumpur is unlikely to think about exchange rates, customs clearance, cold-room capacity or the logistics of moving fresh seafood thousands of kilometres from Japan. That is precisely the point. Behind Malaysia’s growing appetite for Japanese cuisine sits a supply chain where timing, temperature and availability can determine what a restaurant is able to put on its menu. Freshness cannot wait for a delayed shipment. A chef cannot serve an ingredient that did not arrive. And customers accustomed to consistency rarely care about the logistical explanation when something is unavailable. Senri (M) Sdn Bhd operates in that largely invisible space. Established in 2018, the Kuala Lumpur-based importer and wholesaler specialises in Japanese food products, including premium sea urchin and air-flown fish sourced from Japan’s Toyosu Fish Market, alongside frozen seafood and dried ingredients. Its customers span Malaysia’s HORECA sector — restaurants, hotels, cafés and other food-service operators — where Senri’s job extends considerably beyond selling seafood. It is about making distance disappear.   The Business Behind the Menu Malaysia’s expanding Japanese dining market has created opportunities for restaurants and suppliers alike. It has also exposed the vulnerabilities involved in sourcing authentic ingredients internationally. Availability can fluctuate. Import lead times change. Exchange rates move. Shipping disruptions happen. Regulations evolve. Fresh seafood adds another complication: time. For a restaurant, these supply-chain problems quickly become operational ones. An unavailable ingredient can disrupt a menu, while inconsistent quality risks disappointing customers who increasingly expect authenticity and consistency. Senri has therefore built its proposition around reducing uncertainty. Through relationships with Japanese producers and exporters, it coordinates sourcing, import documentation, customs clearance, quality inspection, warehousing and distribution before products reach customers. The company has also expanded beyond fresh seafood into frozen and dried products, giving food-service operators a broader one-stop sourcing platform. As competition increases, however, Senri believes supplying products alone is no longer sufficient. It increasingly works with chefs, restaurant owners and purchasing teams on seasonal offerings, product recommendations and specialty ingredients that can support menu development. In effect, the wholesaler is becoming part of the restaurant’s decision-making ecosystem.   Freshness Has an Infrastructure Problem Growth has made that role more complicated. More customers and a broader product portfolio mean more inventory to predict, store and move. Too little stock risks shortages. Too much creates its own financial and operational consequences. Senri is consequently directing capital towards areas diners will probably never see: cold rooms, warehouse capacity, inventory management and digital systems. The company has implemented a Warehouse Management System and strengthened demand forecasting and standard operating procedures as transaction volumes increase. These investments are intended to improve supply visibility, reduce errors and allow the company to react faster to changing customer requirements. Senri also monitors exchange-rate movements and global supply-chain conditions — factors capable of rapidly altering the economics of imported food. The lesson is straightforward: the promise of fresh Japanese seafood begins long before the fish reaches the chef.   Growing Up as a Business Scaling has also forced Senri to change how it is managed. What began with a more founder-led operational structure has evolved into defined responsibilities across purchasing, logistics, warehouse operations, sales, finance and administration. For management, that transition is necessary because complexity increases with scale. Decisions that could once be handled personally need to be delegated. Departments must communicate effectively. Managers need enough authority to respond quickly when circumstances change. Leadership has therefore shifted towards developing capable teams and future leaders, leaving senior management more room to concentrate on supplier relationships, business development, market expansion and long-term investment. It is a familiar challenge for growing SMEs: the systems that get a company started are rarely the systems capable of taking it much further.   What Customers Don’t See Senri considers one of its biggest competitive advantages to be something customers may barely notice when everything is working properly. Reliability. A delivery arriving on time is not dramatic. Neither is accurate inventory, correctly completed import documentation or a cold chain functioning exactly as intended. But repeat those things consistently and they become commercially valuable. Senri’s relationships with producers and exporters in Japan provide sourcing access, while procurement planning and inventory management are designed to translate that access into dependable supply in Malaysia. The company combines this with responsiveness when customers require something unusual or plans suddenly change. Trust, in this business, is accumulated through hundreds of transactions where nothing goes wrong. And that may become increasingly important as Malaysia’s Japanese food market matures. Consumers have more choices, restaurants face greater competition and expectations surrounding quality and authenticity continue to rise. The businesses serving them therefore need supply partners capable of delivering not just premium ingredients, but predictability. For Senri, the opportunity lies in becoming increasingly difficult to remove from that equation. The glamour of Japanese dining will remain at the front of the restaurant: the precision of the chef, the presentation of the plate and the quality of the ingredients. Senri’s work happens much earlier and mostly out of sight. Because behind Malaysia’s Japanese food boom is a much less visible business — the discipline of making sure the right ingredients arrive at the right place, in the right condition, at exactly the right time.  

ESG

What Consumers Want Is Constantly Changing

Consumers are notoriously difficult to stand still for. What tastes good today may feel ordinary tomorrow. Price still matters, but so do ingredients, convenience, dietary preferences and increasingly, confidence in how a product was made. Food manufacturers are not simply competing against other brands; they are trying to keep pace with customers whose expectations continue to evolve. Director of CWP Food Manufacturing – Yanice Cheong Ming Yan. For CWP Food Manufacturing Sdn Bhd, that change is shaping what comes off the production line — and what happens behind it. Established in 2008 and based in Ipoh, Perak, CWP manufactures traditional and plant-based products for domestic and export markets. Its strategy increasingly combines differentiated products with something less visible to consumers: stronger manufacturing standards. The company believes the next stage of competition will not be won on taste or price alone.   Giving the Market Something Different CWP sees an opportunity in consumers looking for alternatives to conventional products. Its Double Triple Sweet Potato product, for example, uses sweet potato and is positioned around characteristics including naturally occurring anthocyanins, higher fibre, lower oil content and no artificial colouring. Its SeaVit seaweed product approaches the market differently. The plant-based offering is positioned around higher protein and fibre content, zero cholesterol and Halal recognition. Both reflect CWP’s attempt to create products with a clearer reason to exist in an already crowded market. That distinction matters. Consumers walking through a supermarket have no shortage of choices. A new product therefore has to compete not only for taste, but for attention, perceived value and relevance to changing preferences. For CWP, product development is consequently becoming more closely connected to identifying gaps in what consumers want rather than simply producing another variation of what already sells. But getting someone to try a product is only half the challenge.   Taste Gets You In. Consistency Keeps You There. Behind CWP’s product strategy is a less glamorous problem: making sure the same product can be produced reliably at scale. Buyers expect repeatable taste and texture. Distributors need stable supply. Larger customers increasingly require documentation and traceability alongside the product itself. That makes manufacturing discipline part of the commercial proposition. CWP operates with Halal compliance as a baseline and is strengthening its Food Safety Management System through ISO 22000 implementation. Its focus includes supplier controls, standard operating procedures, quality checkpoints, documentation, traceability and staff competency. As production volumes increase, those systems become more important. Scaling creates greater opportunities for variation and human error. CWP has therefore strengthened coordination between production, quality assurance and warehousing while clarifying responsibility for inspections and approvals. The objective is simple: growth should not make the product less predictable.   The Higher Price of Bigger Markets CWP’s ambitions also explain its emphasis on compliance. The company wants to expand into new markets and ultimately reach customers with more demanding procurement requirements. ISO 22000 is part of that preparation, with CWP looking longer term towards internationally recognised schemes such as FSSC 22000 to support access to higher-requirement channels and international chain retailers. That changes how growth has to be measured. Revenue remains important, but CWP also considers repeat orders, customer retention, delivery performance, consistency and reductions in non-conformities. It is deliberately avoiding expansion that would require compromises in food safety, Halal integrity or documentation. For smaller manufacturers, that discipline can determine how far they are ultimately able to travel. Selling into more sophisticated markets does not simply require a product consumers like. Buyers need confidence that the manufacturer behind it can repeatedly meet their requirements.   Less Waste, More Discipline The same operational thinking extends to sustainability. CWP has tightened production planning to reduce material losses and improved handling processes to minimise damaged products. Waste streams are separated for appropriate disposal, while used cooking oil is handled through registered recycling vendors. None of these initiatives is particularly dramatic on its own. But reducing waste also reduces cost, while better handling can improve hygiene, efficiency and product quality. Responsible manufacturing and commercial efficiency do not necessarily have to pull in opposite directions. For CWP, both depend on better processes. That may ultimately be the more important transformation taking place inside the company. CWP started as a manufacturer responding to demand for food products. Its next phase requires it to become increasingly sophisticated in understanding not only what consumers want, but what retailers, distributors and international buyers expect from the companies supplying them. Those expectations will continue moving. Today’s differentiator can become tomorrow’s minimum requirement. Plant-based products become more common. Food safety standards rise. Traceability becomes expected. Consumers discover new ingredients and move on to the next preference. Manufacturers cannot predict every change. They can, however, build businesses capable of responding to them. For CWP, that means combining product development with stronger systems, better-trained people and manufacturing standards capable of supporting larger ambitions. Because what consumers want is constantly changing. The real competitive advantage may be building a company capable of changing with them.

Investment & Market Trends

Li Ka-shing Sticks To US$23 Billion Ports Asking Price Despite Panama Loss

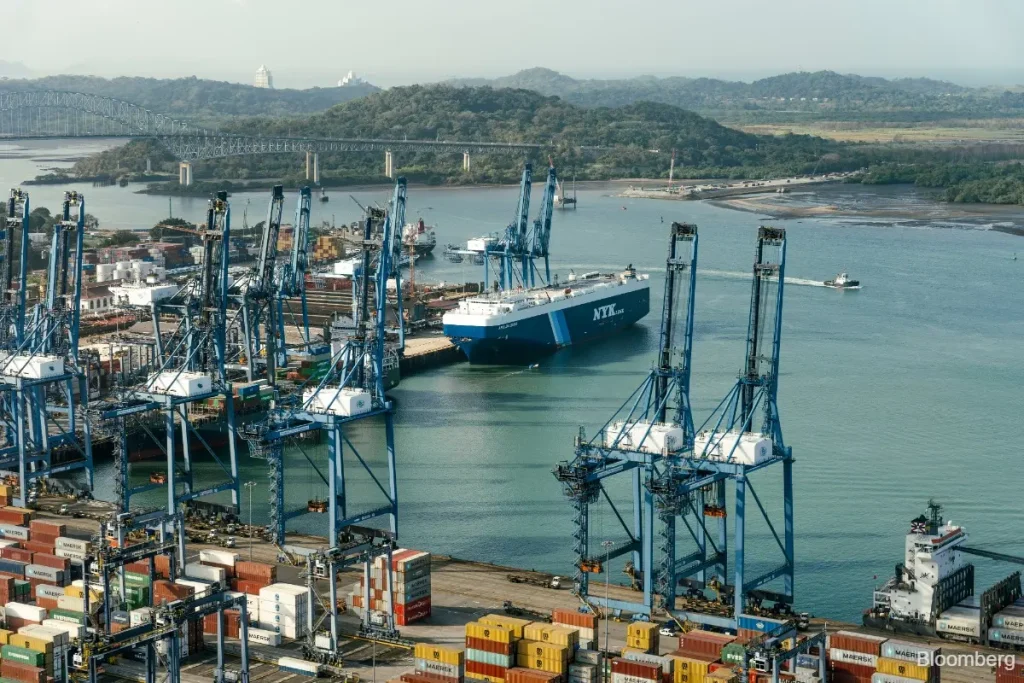
Li Ka-shing’s CK Hutchison Holdings Ltd expects to sell what remains of its global ports portfolio for its original US$22.8 billion (RM91.82 billion) valuation, even after losing two Panama terminals that had originally been included, according to people familiar with the matter. The proposed sale of 43 global ports, to a buyer consortium that includes US investment firm BlackRock Inc, was expected to net CK Hutchison more than US$19 billion in cash when it was first announced in March 2025. That expectation has not changed, even with the Panama Canal facilities excluded from the package, the people said, speaking on condition of anonymity as the deliberations are private. The talks are ongoing, and final details, including pricing, could still shift given the complexity of the deal, they added. Panama invalidated CK Hutchison’s contract to operate the ports earlier this year following pressure from US President Donald Trump. The Hong Kong conglomerate and its unit, Panama Ports Co, have since launched separate international arbitration claims challenging the decision, seeking damages of at least US$3.5 billion. Any compensation arising from those cases is expected to be shared between CK Hutchison and the buyers, one of the people said. The Panama facilities had accounted for only about 4% of the portfolio’s original price. According to one of the people, the price of the remaining 41 ports is believed to have risen enough to offset their loss, as buyers increasingly view them as logistical assets generating stable income amid rising geopolitical tension. Company representatives, bankers and lawyers continue to meet weekly to negotiate deal terms, the people familiar with the matter said. The sale has become a flashpoint in the broader US-China rivalry, with tensions running especially high over the Panama terminals, as Washington vows to protect its interests in Latin America while Beijing expands its influence in the region. Hopes for a political breakthrough have been renewed following news that Chinese leader Xi Jinping plans to meet Trump during his September trip to the US, though the parties remain cautious given that a similar high-level meeting in May between the two failed to yield results, according to the people. A spokesperson for BlackRock declined to comment. CK Hutchison and members of the buyer consortium — including China Cosco Shipping Corp, China Merchants Bank Co and Italian billionaire Gianluigi Aponte’s MSC Mediterranean Shipping Co — did not respond to requests for comment. Mired Down The deal hit roadblocks soon after it was announced, with CK Hutchison drawing Beijing’s ire over its agreement to sell ports in strategically significant global locations to a consortium backed by BlackRock. To secure China’s approval, the group invited state-owned companies, including Cosco, to join the buyer consortium. Discussions have remained bogged down as the parties navigate regulatory hurdles across the various countries where the ports are located, while also attempting to reconcile competing demands from prospective buyers. Talks have centred on a proposal to split the ports into different ownership structures, according to reports. That arrangement could give Chinese buyers larger stakes and greater control in certain locations, while other consortium members take the lead elsewhere. Panama’s forced takeover of the two terminals added further uncertainty to the deal, with Beijing warning that the country could pay a “heavy price” for the move. Parties involved in the sale are likely to seek positive signals from both China and the US before finalising the transaction’s terms, according to reports. There are signs, however, that tensions between Beijing and Panama may be easing. The two sides are reportedly moving toward renewing an agreement that gives Panama-flagged vessels favourable treatment at Chinese ports, according to local media reports in August, citing China’s ambassador to the country.

Investment & Market Trends

SBC Weighs Consolidating Singapore Operations Under Single Entity

HSBC Holdings plc is considering merging its wholesale, retail and private banking businesses in Singapore into one unified entity as part of a broader effort to simplify its structure, according to sources close to the matter who spoke on condition of anonymity. This potential restructuring is part of a larger transformation effort led by CEO Georges Elhedery, who has been streamlining the bank’s operations, closing or divesting several units, and cutting costs since taking the helm in September 2024. Earlier this year, HSBC sold its Singapore insurance arm for US$2.1 billion (RM8.46 billion). Responding to the reports, an HSBC spokesperson said the bank regularly evaluates its organizational setup for ways to simplify, while stressing that all Asia-Pacific entities remain under the oversight of The Hongkong and Shanghai Banking Corporation, with no changes planned to that arrangement. Currently, HSBC’s Singapore retail and wealth management business operates as a separately incorporated entity, HSBC Bank (Singapore) Ltd, established in 2016, alongside a separate branch under its main Asia arm, The Hongkong and Shanghai Banking Corp. Despite the potential restructuring, HSBC continues to expand its presence in Singapore, including plans for a new global AI hub and the hiring of over 100 AI specialists. The possible shake-up comes as HSBC faces scrutiny over its heavy reliance on Hong Kong, where it holds the largest exposure among global banks amid rising geopolitical tension. The bank recently expanded further in the territory through its US$14 billion buyout of Hang Seng Bank Ltd, reinforcing Hong Kong’s role as its top profit source and one of the city’s three banknote-issuing institutions. By comparison, HSBC’s Singapore business remains far smaller. In the first half of 2026, Singapore contributed US$774 million in pretax profit, against Hong Kong’s US$7.8 billion. Hong Kong also employs over 30,000 HSBC staff with US$144 billion in wholesale loans, compared to roughly 3,600 employees and US$21.8 billion in wholesale lending in Singapore. Such restructuring wouldn’t be unprecedented — in 2019, Standard Chartered plc took a similar step, consolidating into a locally incorporated subsidiary and establishing twin hubs in Singapore and Hong Kong to cut costs and simplify operations.

Scroll to Top

Subscribe
FREE Newsletter